Up To 100% Financing & *$50K ExtraWhen You Buy Or Build With Three Stone Homes
Singlewide, doublewide, and triplewide manufactured homes, plus one and two-story modular homes on a pad or a full basement, from Three Stone Homes locations in Rogersville, Harrisonville, and Lake of the Ozarks. The land, the home, and the setup, financed in one plan by a direct lender.
How Do You Finance A Manufactured Or Modular Home From Three Stone Homes In Missouri?
A new home from Three Stone Homes, placed on land you own or land you buy at closing, is financed with a construction loan that converts to a permanent mortgage. The land, the home, the foundation or basement, and the setup written into Three Stone's contract can all sit inside that one loan, and qualified buyers can access up to 100% financing on eligible programs.
There is also a step most buyers never hear about. Before a lender can fund a dealer's home, the dealer has to be approved, and a dealer asked to start over with an unfamiliar bank has to send financials, sit through calls, and learn a new draw process. Plenty of dealers stall on that. Three Stone Homes is already registered with our bank, so the only approval left is yours, which improves and speeds up the closing process.
Three Stone Homes is a family-owned, independent retailer of manufactured and modular homes with three Missouri locations: Rogersville outside Springfield, Harrisonville south of Kansas City, and Lake of the Ozarks. The company represents more than 80 home styles from manufacturers that include Commodore, Cavco, Champion, and New Castle, and reports being a three-time recipient of the "Best Home Center in the Midwest" recognition.
The company is also active on housing policy. Working with the Missouri Manufactured Housing Association, Three Stone helped place a modern modular home on site at the Missouri Capitol so legislators could walk through it, and asked lawmakers to treat modular and manufactured homes the same as site-built homes in local zoning.
Three Stone says it explains, before the contract is signed, what the home price includes, what site prep, utilities, foundations, and permits will add, and what can affect the timeline. A project coordination team then schedules delivery, setup, and foundation work with the manufacturers and contractors, which matters to a lender because the draw schedule follows that same plan.
Three Stone buyers work directly with Jessica Edwards, Top Rated® Sr. Vice President, NMLS ID# 1629864, BuildBuyRefi.com, powered by The Federal Savings Bank, from the first eligibility question through the final draw.New Construction Loan Specialist | Construction Loan Specialist | Veteran Lending Specialist
Manufactured And Modular Homes For Sale In Rogersville, Harrisonville, And Lake Of The Ozarks
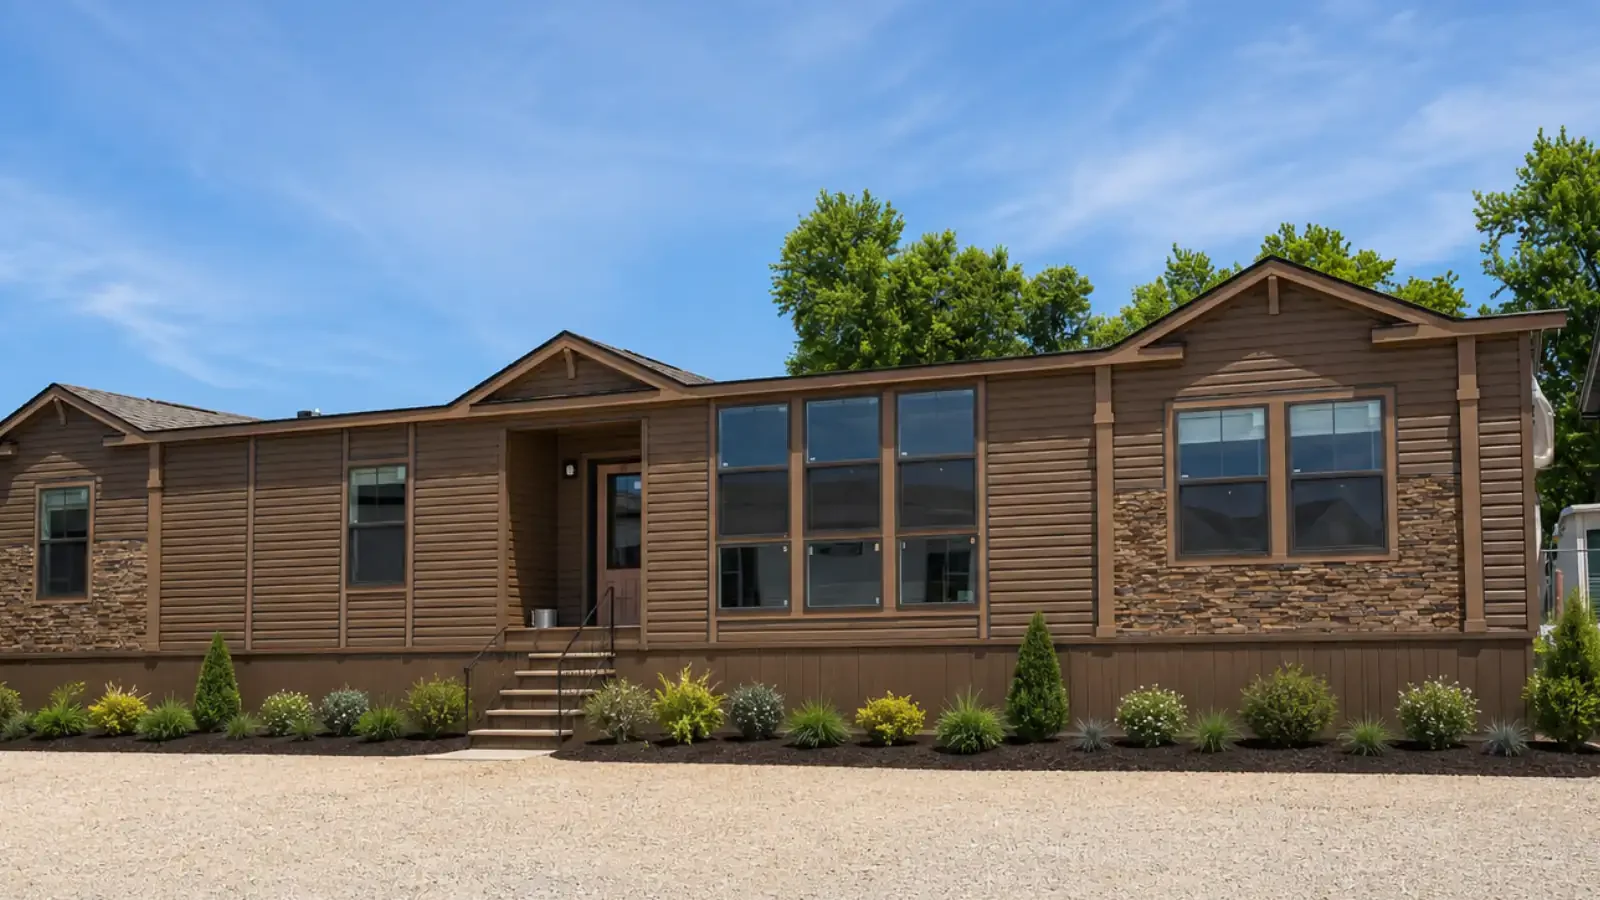
Three Stone Homes sells single-section, double-section, and triple-section manufactured homes and one and two-story modular homes, set on a pad or over a full basement. With more than 80 styles across its manufacturers, buyers can start from a display model and customize, or order a plan from the catalog.
Built To The Same Codes As A Site-Built Home
- Built to the same state and local building codes as site-built homes, and in many Missouri jurisdictions to higher standards, according to Three Stone
- Placed on a permanent foundation and inspected locally like traditional construction
- Appraised the same way as a site-built home
- Available in one and two-story plans, including over a full basement
Built To A Federal Standard, Inspected At The Factory
- Built to the federal construction standard set by the U.S. Department of Housing and Urban Development
- Inspected at the factory and, as Three Stone notes, subject to Missouri Public Service Commission oversight
- Available as singlewide, doublewide, and triplewide homes
- Financed with a mortgage once permanently affixed on land the buyer owns
Why factory-built costs less. Three Stone cites savings of roughly 20% for modular construction and 40% or more for HUD Code manufactured homes compared with site-built construction, along with shorter build timelines. A shorter build also means fewer months of interest during construction. These figures are Three Stone's and vary by home and site.
A Sample Of Three Stone Display Models
Model #03
The largest plan in this sample, for a big household or a home office setup.
- 4 Bed
- 3 Bath
- 3,000 Sq Ft
Model #09, Low Country
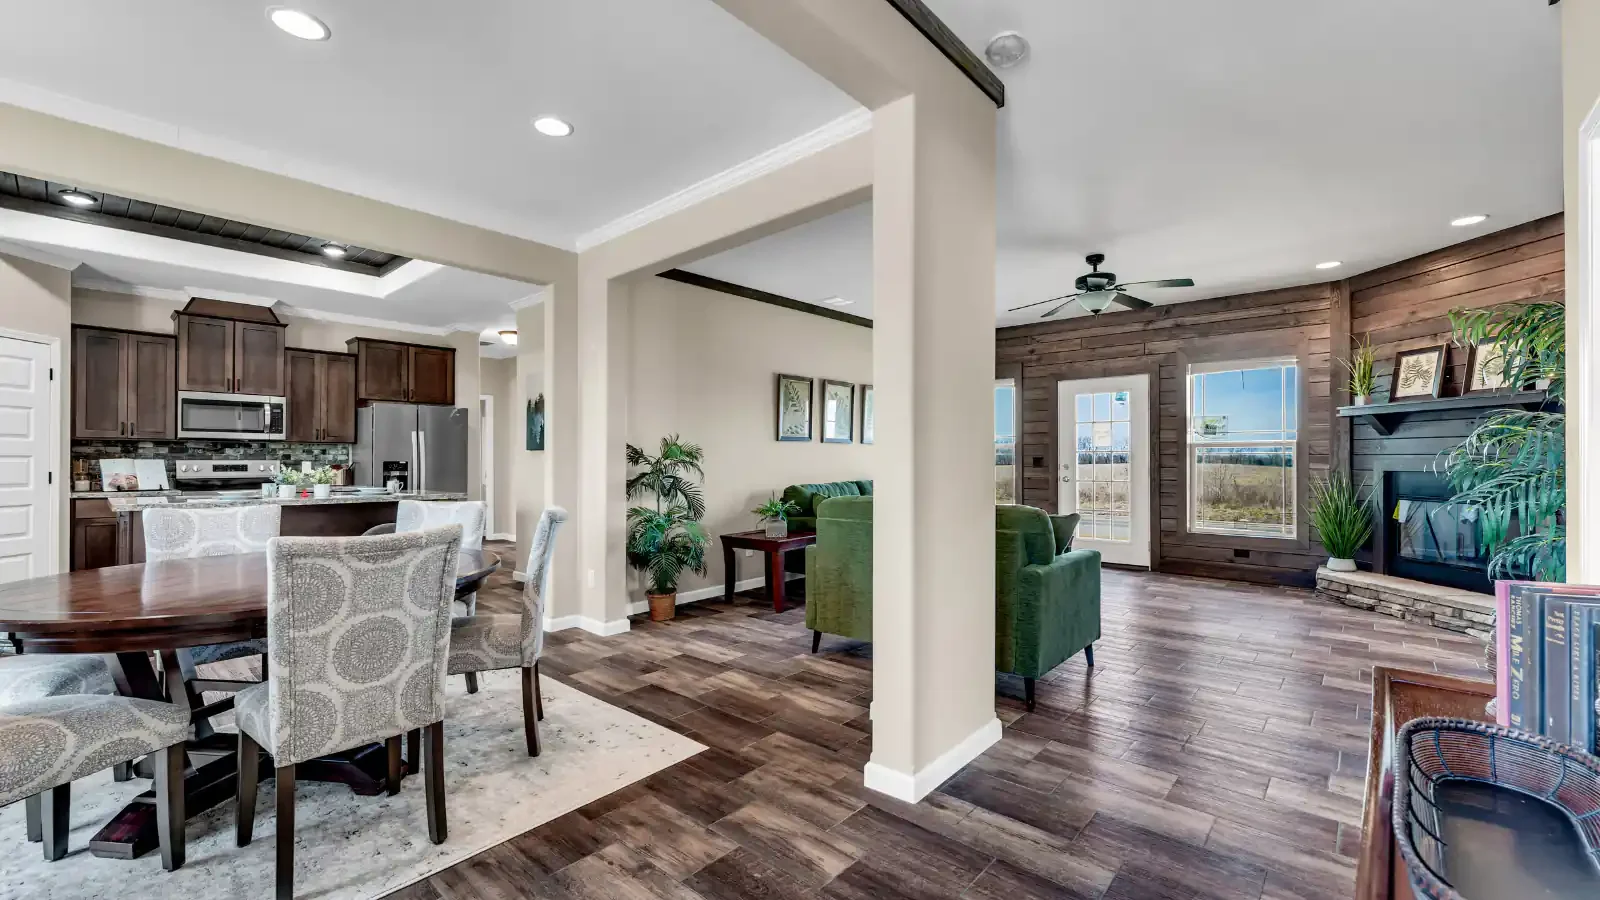
Open kitchen with a large island, a private primary suite, and a front porch. The living room is pictured at the top of this page.
- 3 Bed
- 2 Bath
- 2,100 Sq Ft
Model #10
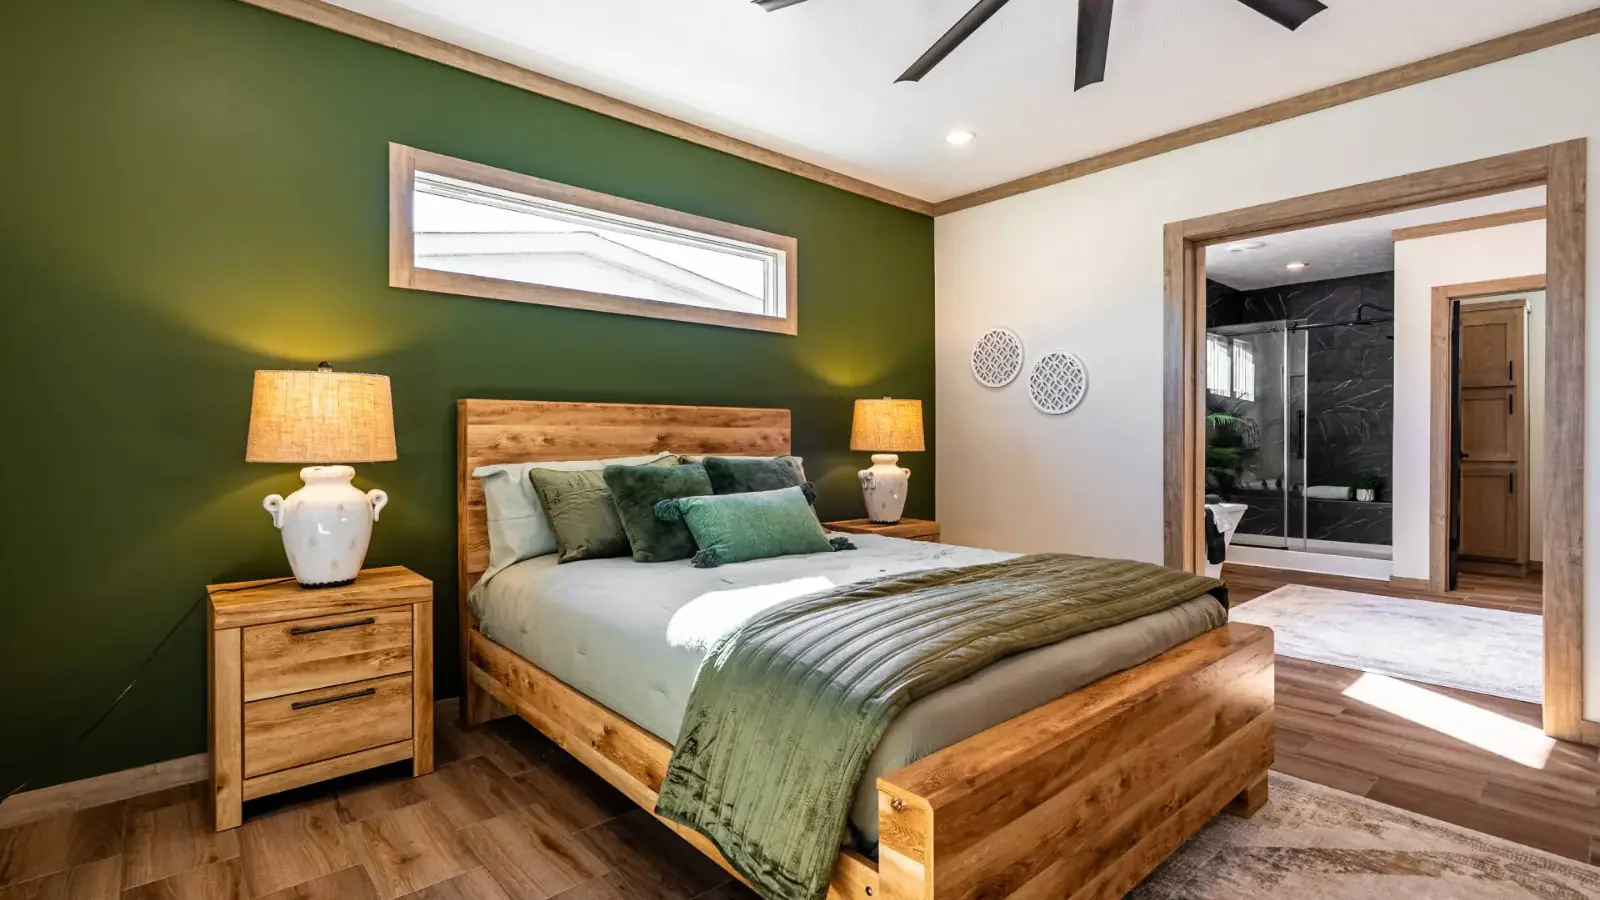
Three full baths in about 2,000 square feet. The exterior and primary bath are shown on this page.
- 3 Bed
- 3 Bath
- 2,014 Sq Ft
Model #07
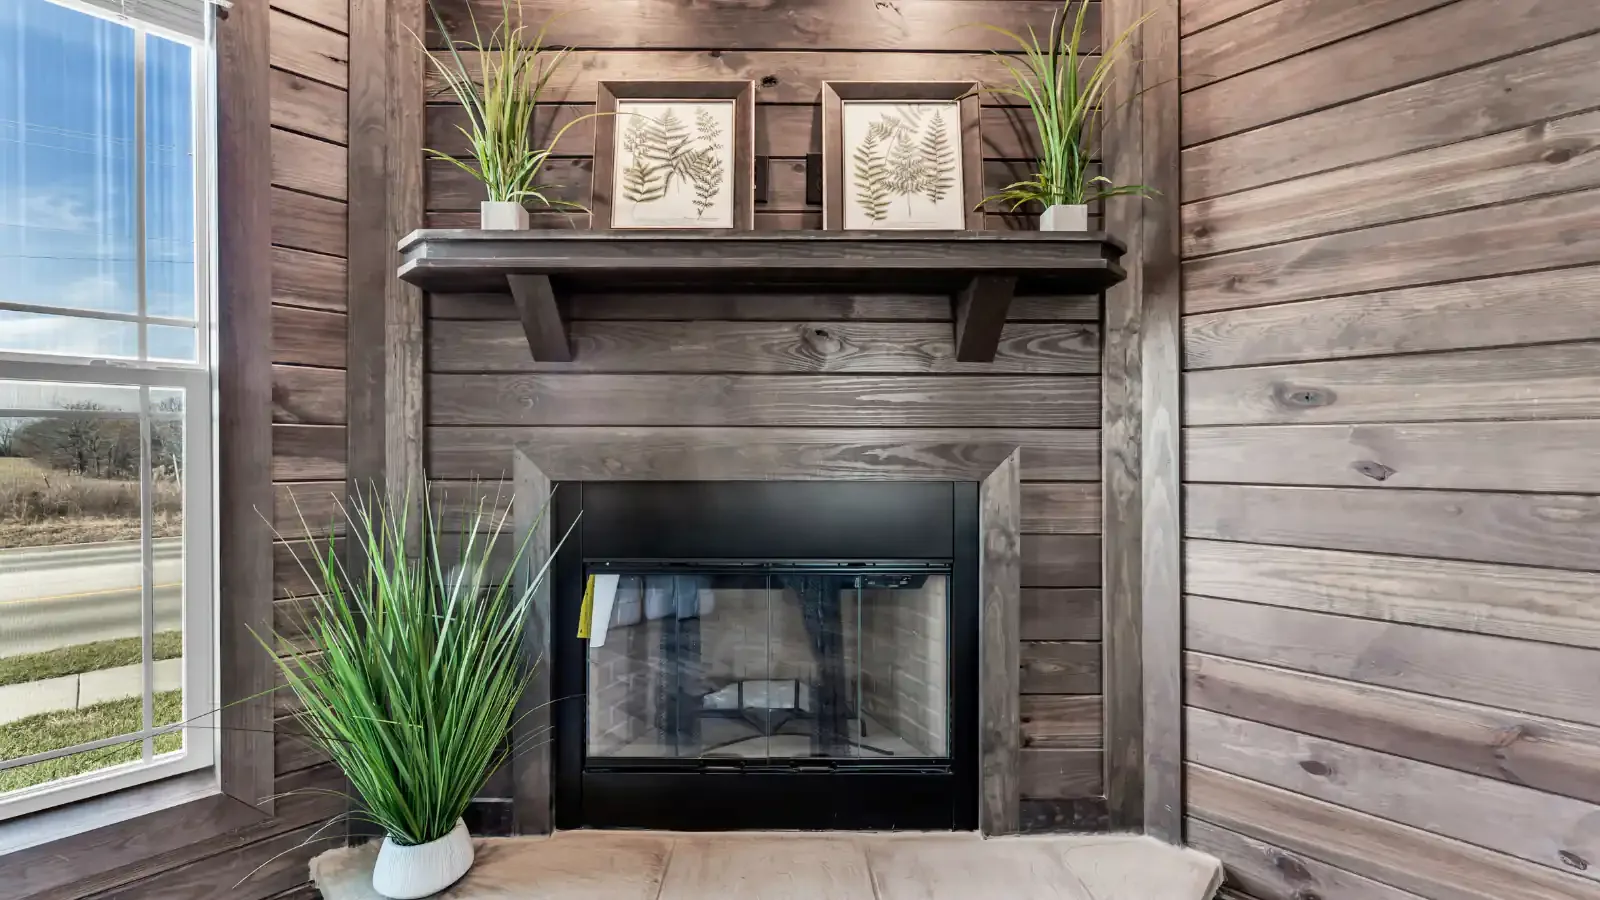
Four bedrooms with an open kitchen, dining, and living area and a fireplace feature wall.
- 4 Bed
- 2 Bath
- 1,800 Sq Ft
Model #04
A larger four-bedroom plan on the Lake of the Ozarks lot.
- 4 Bed
- 3 Bath
- 2,610 Sq Ft
The Tulip
A compact home for a first purchase, a cabin lot, or family on shared land.
- 2 Bed
- 1 Bath
- 544 Sq Ft

Models, sizes, and specifications are listed by Three Stone Homes and its manufacturers. Display inventory changes often, so check current availability with Three Stone.
Three Ways To Buy A Three Stone Home, Each Financed As A Construction Loan
Three Stone sells homes three ways, and our construction loan fits each one. Anything written into Three Stone's contract before closing can be part of the loan in qualifying scenarios.
Turnkey Land And Home
Three Stone offers land and lot packages when they are available, with the home delivered, set, and finished as one turnkey project. Ask Three Stone which lots are open now.
Turnkey On Your Land
Already own acreage? Three Stone delivers the home and handles the setup on your property, so you are not hiring and scheduling a set crew yourself.
Home, Delivery, And Install
Prefer to manage the site work yourself through licensed contractors? Three Stone can provide the home with delivery and installation, and you add the finishing touches.
Delivery Within 75 Miles And Full Setup
Three Stone says its home prices include delivery within 75 miles of each location, setup, blocking, leveling, tie-down, trim-out, air conditioning, and the options shown on the display model. Delivery farther out is available for an added fee.
Garages, Porches, Basements, And More
Three Stone also builds garages, decks, covered porches, and sunrooms, and offers full basement and second-story infill, so one company can handle the home and the additions around it.
How A Financed Three Stone Purchase Moves
Check eligibility and get a budget
Answer a few questions and talk with Jessica Edwards about programs, down payment, and land equity before you fall in love with a floor plan.
Choose the home and how to buy it
Tour models in Rogersville, Harrisonville, or Lake of the Ozarks, then pick turnkey land and home, turnkey on your land, or home only.
Put everything in the contract
Foundation or basement, garage, porch, and site work all go into Three Stone's contract before closing, so they can be part of the loan.
Close once, then build
The independent appraisal is completed, the loan closes, and the home is ordered. Draws are released after independent third-party inspections as work is completed.
Delivery, set, and move in
Three Stone coordinates delivery, setup, and finish work. When the home is complete, the loan converts to the permanent mortgage.
Building over a basement? One Commodore buyer who built over a full basement on the family farm suggests confirming basement wall heights with every party early. Settling foundation details before closing keeps the contract, the appraisal, and the loan in agreement.
Site work, foundations, basements, garages, and setup can be financed only when written into the dealer's contract before closing, supported by the appraisal, and allowed under program guidelines. Self-installation and owner-as-contractor arrangements are not eligible. Construction draws are released after independent third-party inspections. Delivery terms and included features are Three Stone's own and are not a guarantee by BuildBuyRefi.com or The Federal Savings Bank.
What We Can And Cannot Finance On A Three Stone Homes Purchase
Knowing the limits before you pick a floor plan saves time later. Here is where our financing applies and where it stops.
What We Can Finance
- New HUD Code manufactured homes and modular homes from Three Stone, permanently affixed to a foundation on land the buyer owns or buys at closing
- Manufactured homes converted to real property under ALTA 7.1 title standards
- One and two-story modular homes, financed the same way as a site-built home
- Homes set on a pad or over a full basement, plus garages, porches, decks, and sunrooms in the contract before closing
- The land, plus delivery, setup, and site work written into the contract
- Homes of 400 square feet or more, so compact plans like The Tulip can qualify
- Primary residences, and second homes in qualifying scenarios
What We Cannot Finance
- Used or previously owned mobile homes
- Moving or relocating an existing home
- Homes placed on land the buyer does not own, including rented or leased lots and land-lease communities
- Park model homes
- Manufactured homes as investment or rental properties
- Self-installed or owner-as-contractor projects
- Work left out of the contract, which cannot be added to the loan after closing
Appraisals are completed by independent appraisers, and we have no influence over the value. Draws are released after independent third-party inspections, not on a fixed calendar.
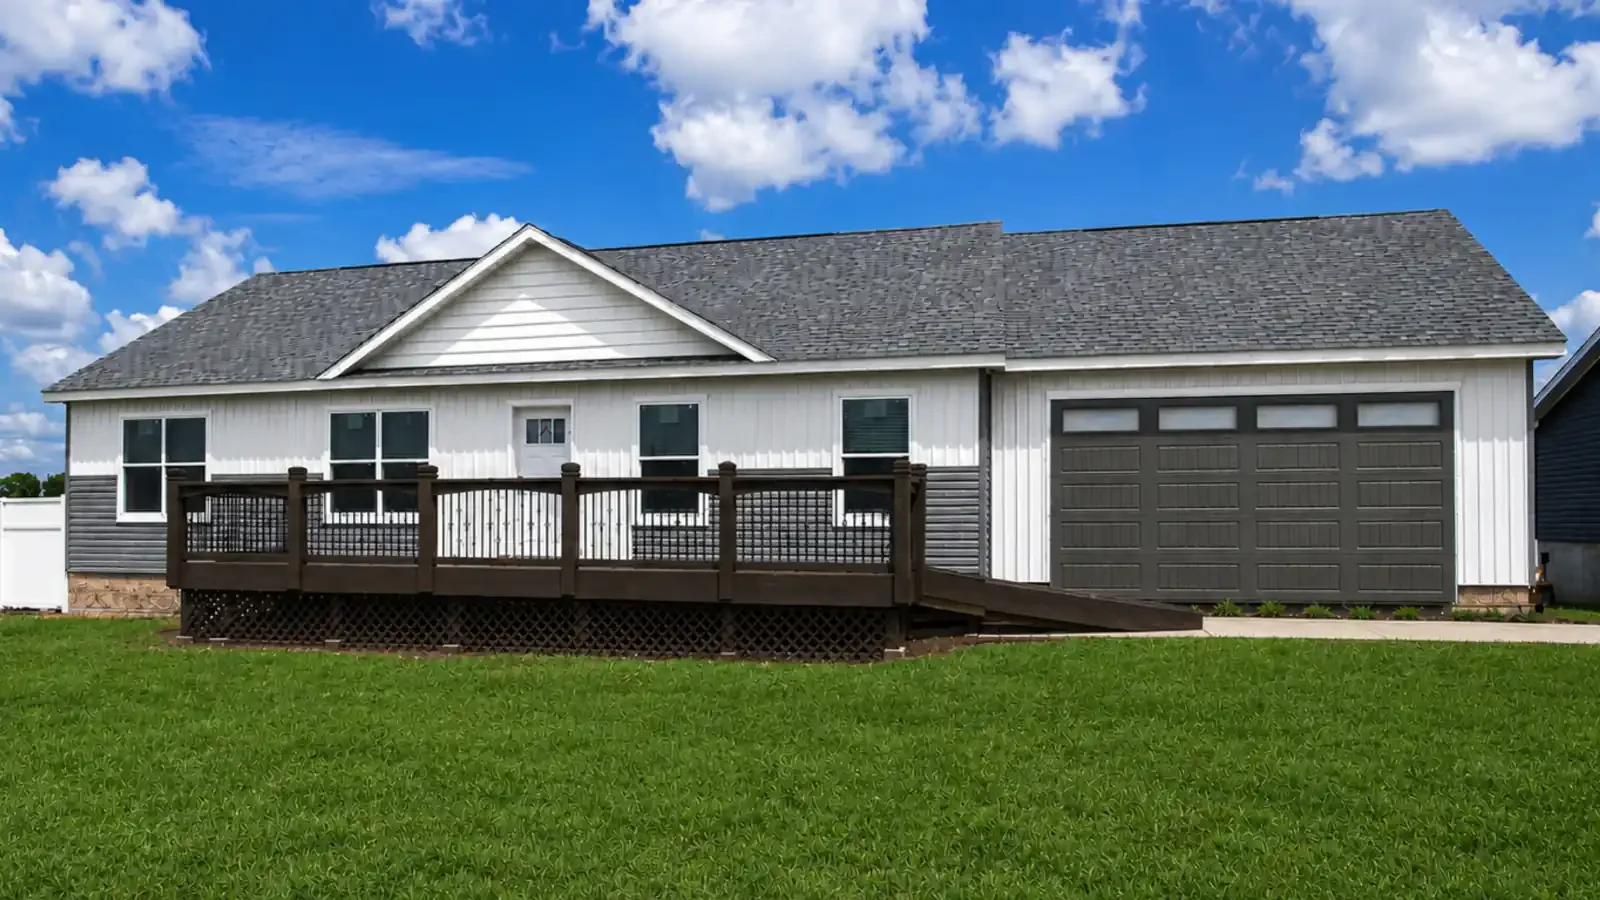
Manufactured And Modular Home Construction Loans For Springfield, Kansas City Area, And Lake Of The Ozarks Buyers
BuildBuyRefi.com is powered by The Federal Savings Bank, a federally chartered, FDIC-insured, veteran-owned direct lender licensed in all 50 states, NMLS #411500. The land, the home, the basement or foundation, and the permanent mortgage are underwritten together as one plan.
Three Construction Loan Structures
Hybrid Construction Loan
Built in-house. Both sets of documents are prepared upfront, so it runs like a single close with one set of fees, while the permanent rate stays open until the home is finished. FHA and VA streamline eligible on the permanent loan in qualifying scenarios. Brokers and correspondent lenders cannot replicate it.
One-Time Close Construction Loan
Qualify once and close once. The permanent rate is locked at that first closing, and the loan converts at completion with no re-qualification and no second appraisal.
Two-Time Close Construction Loan
Construction and permanent loans close separately, so the permanent rate is set on the market when the home is done. We cover the origination fee on the second closing, and FHA and VA borrowers can streamline the permanent loan.
Program Details Three Stone Buyers Ask About
- 640 minimum credit score on Conventional and FHA construction programs
- Up to 100% VA construction financing for eligible veterans through our Hybrid and Two-Time Close, with no monthly mortgage insurance
- Land equity applied toward the down payment, or an existing land loan paid off at closing
- Second home construction in qualifying scenarios, for buyers who want a place at Lake of the Ozarks or on family land
- ITIN construction for qualified primary residence borrowers
- Jumbo construction up to $4.5 million, and investment property construction available on modular homes but not on manufactured homes
Direct Lender, Broker, Or Correspondent
A broker hands your file to another lender. A correspondent lender closes your loan and then sells it, and the new owner's rules can change things in the middle of a build. We originate, underwrite, fund, and manage every draw in-house, so the team that approved the loan is the team paying out when the home is delivered and set.
No administrative fees on our construction programs. Broker and correspondent construction loans often carry $40,000 to $100,000 or more in layered fees, which can push the loan above what the finished home appraises for. Ask for every fee line by line on any quote you compare.
All programs are subject to credit qualification, property eligibility, and applicable program guidelines. Manufactured homes must be permanently affixed to a foundation on land owned by the borrower at closing and converted to real property. Rates, terms, and availability vary by borrower, property, occupancy, and program, and are not guaranteed. Appraisals are performed by independent licensed appraisers and construction inspections are performed by third-party inspectors. Contact your banker for applicable rates, terms, and conditions.
*$50,000
Extra Funds For What The Mortgage Does Not Cover
Qualified borrowers can access up to $50,000 in separate, unsecured funds before, at, or after closing, underwritten in-house at the same time as the mortgage. It does not rely on equity and it does not change loan-to-value. We are not aware of another lender in this space offering it.
How Three Stone Buyers Could Use It
Furnishing the new home
Furniture, appliances, and window coverings. The mortgage builds the house, it does not fill the rooms.
Finishing a basement
Framing, drywall, flooring, or a bathroom in the lower level after move-in, when the basement shell was built with the home.
A storm shelter
Southwest Missouri storm season makes a safe room or storm shelter a common add-on for families on rural acreage.
Gravel drive, fence, or shop
A long rock driveway, fencing for livestock or pets, or a small outbuilding on country land.
Lake living extras
A dock-side deck, outdoor furniture, or a golf cart for a second home at Lake of the Ozarks.
Consolidating debt to qualify
Paying down qualifying revolving balances can improve the debt-to-income ratio, which in some scenarios helps a borrower qualify for the home they want.
*Up to $50,000 is available to qualified borrowers and can be applied across our loan programs. This is a separate unsecured consumer loan underwritten in-house at the same time as the mortgage. Proceeds cannot be used for a down payment. Approval, amount, rates, and terms depend on credit qualification and are not guaranteed. Local zoning governs what may be placed on any property. Contact your banker for applicable rates, terms, and conditions.
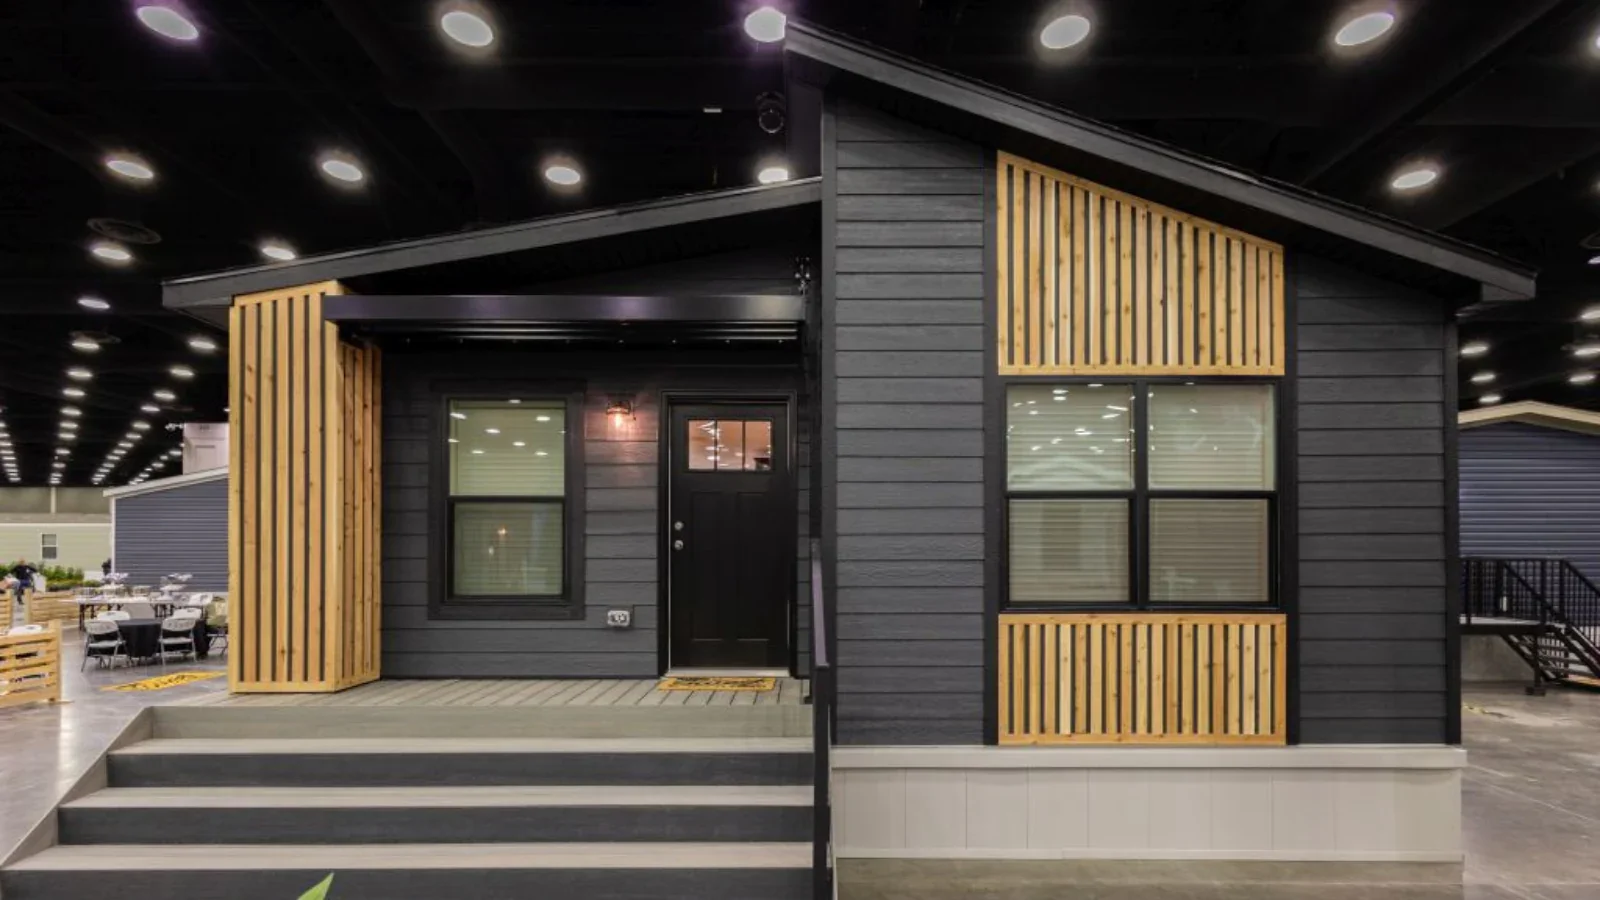
Save Up To 30% On Real Estate Commissions When You Sell A Home Or Buy Agent-Listed Land
A Three Stone purchase often comes with a second transaction: a current house to sell, or acreage to buy from a seller who listed it with an agent. Qualified borrowers can save up to 30% on real estate commissions on those agent-represented transactions through our participating agent network, applied as a closing cost credit or toward a rate buy-down.
Selling Your Current Home
Moving into a new Three Stone home usually means selling the one you have. The savings apply to that sale, in Missouri, Kansas, or any other state.
Buying Agent-Listed Land
If the acreage you want near Springfield, Harrisonville, or the lake is listed with an agent, the network can represent your side and the savings apply there.
Credit Or Rate Buy-Down
Put the savings toward closing costs or toward a lower rate. Jessica Edwards can price both so you can compare.
What this covers and what it does not. The benefit applies only to agent-represented transactions: selling an existing home, buying an existing listed home, or buying land listed with an agent. It does not apply to a new home or a land and home package bought directly from Three Stone Homes. A home bought from a dealer is a direct purchase with no listing commission to reduce.
No money changes hands between us and the participating agents in either direction. We do not pay them, they do not pay us, and we earn nothing when a borrower uses one. Paying or receiving fees for referrals of federally related mortgage loans is prohibited by law, and we do not do it.
Commission savings are available to qualified borrowers through a participating real estate agent network, subject to agent availability, program terms, and applicable state law. Savings apply to an agent-represented transaction. Actual savings vary by property, sale price, and the agreement reached with the participating agent. This benefit does not apply to the direct purchase of a new home from a builder or dealer. No referral, affiliate, or other fee is paid or received by BuildBuyRefi.com or The Federal Savings Bank in connection with this benefit. Contact your banker for details.
Add A Second Three Stone Home, A Garage, Or An Addition Without A Cash-Out Refinance
Plenty of Missouri families already own the land and the house. What they want is a second home on the farm for a parent, a place for a grown child, or a garage and sunroom on the house they have. Our 2nd Mortgage Construction-to-Permanent loan was designed for that.
Homeowners who locked first mortgage rates between 2.5 and 4.0 percent in 2020 and 2021 usually lose money on a cash-out refinance, because it moves the whole balance to today's rate. Our loan funds the project in inspected draws, then converts to a fixed-rate, closed-end second lien at completion. Your first mortgage keeps its rate, and only the new money carries a new one.
Projects It Fits On Property You Own
A Second Home For Family
A new manufactured or modular home from Three Stone, delivered and set on your acreage for a parent or adult child.
A Compact ADU
A small plan such as The Tulip, placed as an accessory dwelling unit where your county's zoning allows it.
Garage, Porch, Or Sunroom
A detached garage, a covered porch, or a sunroom on your current home, the same building services Three Stone offers.
We are not aware of another lender offering the 2nd Mortgage Construction structure. It is underwritten, funded, and draw-managed in-house, with the same inspected draws and the same 640 minimum credit score as our other construction programs. The second home must be new; used and relocated homes are not eligible. Learn more in our ADU financing guide.
Subject to credit qualification, property eligibility, lien position, available equity, and applicable program guidelines. Rates and terms vary by borrower and property and are not guaranteed. Local zoning and permitting govern what may be placed on any given property. Contact your banker for applicable rates, terms, and conditions.
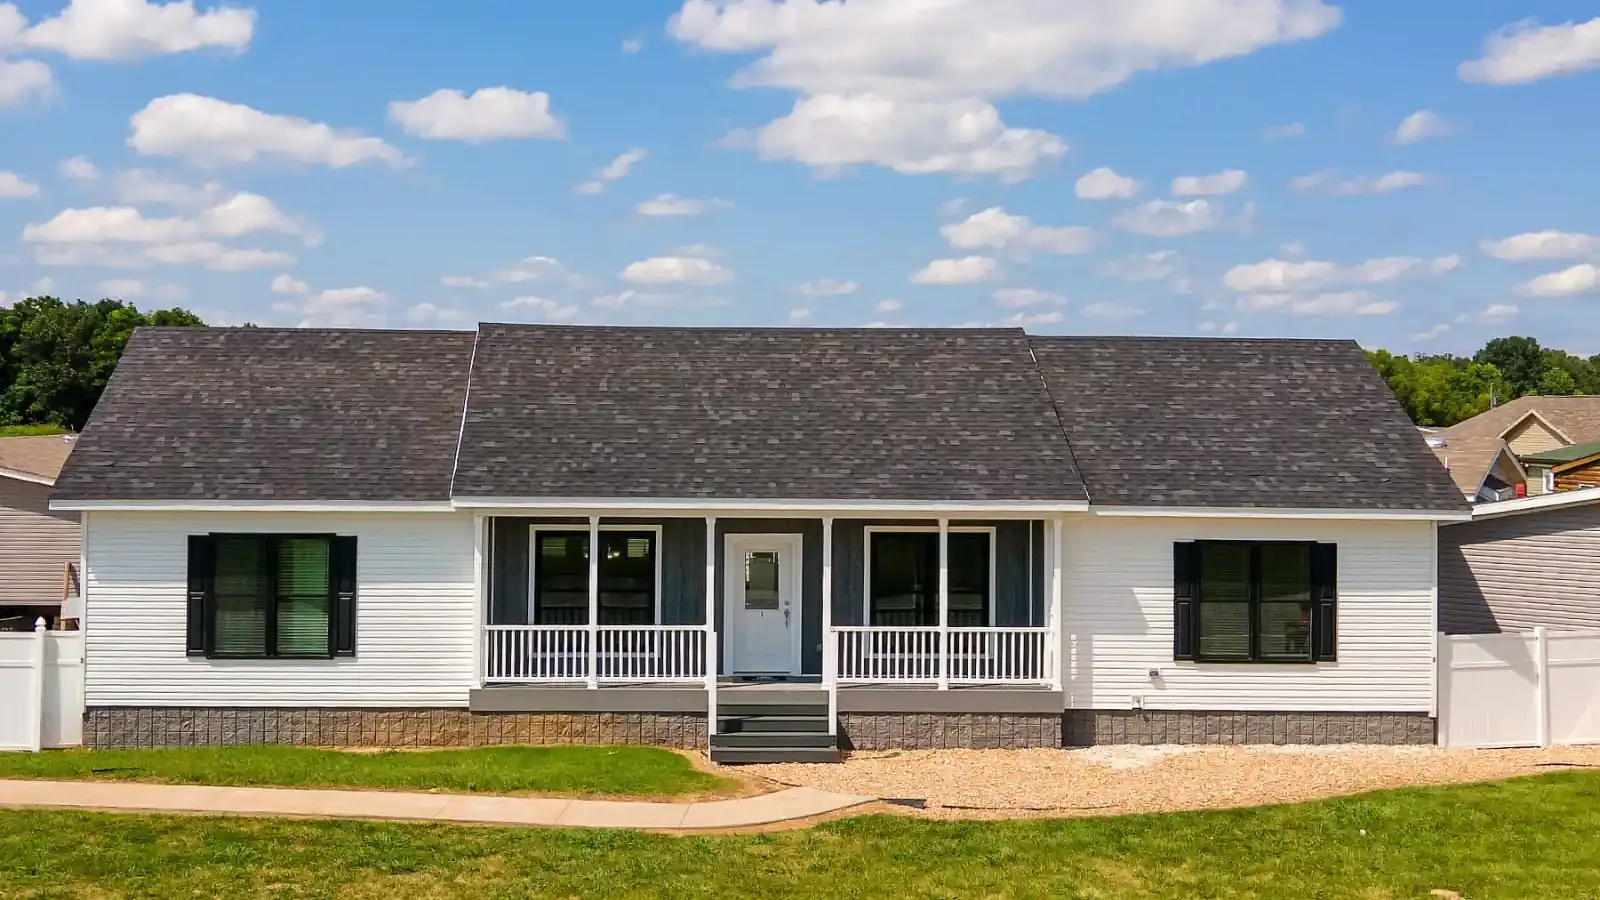
Meet Jessica Edwards, The Banker Assigned To Three Stone Homes Buyers
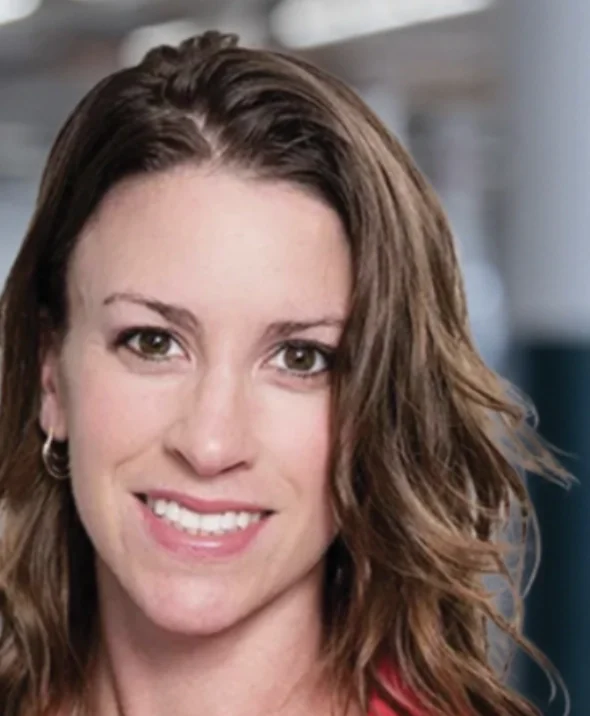
Jessica Edwards
Top Rated® Sr. Vice President
BuildBuyRefi.com, powered by The Federal Savings Bank | NMLS ID# 1629864
Three Stone buyers work with Jessica directly, from the first question to the final draw. No call center, no rotating queue, and no hand-off to someone new halfway through the build.
Her designations cover each piece of a Three Stone purchase: construction and new construction for the home, land, and setup, veteran lending for buyers using their VA benefit, and FHA 203K and FNMA HomeStyle for owners improving a house they already have.
What Jessica handles for a Three Stone buyer: comparing the Hybrid, One-Time Close, and Two-Time Close, applying land equity, confirming the full scope is in Three Stone's contract, checking that the foundation and title meet program rules, and keeping draws in step with Three Stone's delivery and setup schedule.
See her full background on Jessica Edwards' banker profile.
What Missouri And Kansas Buyers Say About Three Stone Homes
The same themes repeat: questions answered, crews that care about the details, and support that continues after move-in. Four reviews, summarized in our words.
★★★★★
Jessica says choosing Three Stone was the right call for her family. She credits the finish crew, the walkthrough team, and Allison's communication, and says the crew moved fast to get her family settled before they left for training. A welcome home package was the final touch.
Jessica M., Google review★★★★★
India's family says Randy and Allison answered every question they had, and that every crew from foundation to finish was excellent. Their finish crew came back to fix items that came up even after the final walkthrough.
India B., Google review★★★★★
Johnna and her husband built through the Harrisonville location while replacing their old home. Jim Larson helped them design the space, the exterior team worked to get every detail right, and Allison followed up after move-in. Two neighbors had built with Three Stone a year earlier.
Johnna R., La Cygne, KS, Google review★★★★★
After years in an older mobile home, Brad's family built a Commodore modular over a full basement on the family farm. He points to the 2x6 walls and 9-foot ceilings, says the home feels like a stick-built house and stays solid in storms, and praises the set and finish crews.
Brad H., Google reviewReviews are paraphrased from Three Stone Homes' public Google listing and describe the dealer's service, not BuildBuyRefi.com financing.
Check Your Eligibility For A Three Stone Homes Purchase
A few questions show which programs fit your land, your home, and your budget. No credit pull, no Social Security number, and no obligation. Your answers go to Jessica Edwards and the Three Stone Homes team.


Schedule A Free Strategy Call With Jessica Edwards
Pick a time that works for you. Bring your land details, a rough budget, or a model you liked on a Three Stone lot, and Jessica will walk through which programs fit.
Frequently Asked Questions About Three Stone Homes And Manufactured Home Financing In Missouri
What buyers around Springfield, Harrisonville, and Lake of the Ozarks ask most before buying from Three Stone, answered plainly.
What kinds of homes does Three Stone Homes sell?
Three Stone sells new singlewide, doublewide, and triplewide manufactured homes and one and two-story modular homes, set on a pad or over a full basement. The company represents more than 80 styles from manufacturers that include Commodore, Cavco, Champion, and New Castle. Display inventory at each location changes often.
Why does it matter that Three Stone Homes is already registered with BuildBuyRefi?
Dealer approval takes real work. A lender with no relationship has to collect the dealer's records, run its own review, and set the dealer up before your file can move, and dealers are often slow to repeat that with a new lender.
Three Stone Homes is already registered with our bank, so that work is done. The only approval left is yours, which improves and speeds up the closing process.
How far does Three Stone Homes deliver?
Three Stone says it delivers within 75 miles of its Rogersville, Harrisonville, and Lake of the Ozarks locations as part of the home price, and farther for an added fee. Our financing is licensed in all 50 states, so the loan follows the home wherever Three Stone delivers.
Can the land, the home, a full basement, and setup be financed in one loan?
Yes, in qualifying scenarios. The land, the home, delivery, setup, a pad or full basement foundation, and add-ons such as a garage or covered porch can be combined in one construction loan when they are in Three Stone's contract before closing and supported by the appraisal. A modular home over a basement is financed the same way as a site-built home. Work added after closing cannot be financed in the loan.
Can I use land I already own toward the down payment?
Yes. If you own the land free and clear, its value can reduce or eliminate the cash down payment in qualifying scenarios. If you still owe on it, the balance can be paid off at closing and rolled into the construction loan. Land held by family has to be deeded into your name before the loan can proceed.
What credit score do I need to finance a manufactured or modular home?
The minimum is 640 on our Conventional and FHA construction programs. Meeting the minimum does not guarantee approval, so Jessica Edwards can review where you stand before you apply.
Can veterans get 100% financing on a Three Stone home?
Eligible veterans may qualify for up to 100% VA construction financing with no monthly mortgage insurance through our Hybrid and Two-Time Close structures, when the home is permanently affixed on land the veteran owns or buys at closing. All terms are subject to credit qualification and program guidelines.
What is the difference between a manufactured home and a modular home in Missouri?
A manufactured home is built to the federal HUD Code and must be permanently affixed to a foundation and converted to real property to qualify for a mortgage. A modular home is built to state and local building codes and is appraised and financed like a site-built home. Three Stone sells both, so ask which code a given model is built to.
I already own my home. Can I add a second home or a garage on my land?
Yes, in qualifying scenarios. Our 2nd Mortgage Construction-to-Permanent loan finances a new second home, an ADU, a garage, or an addition on property you own and converts to a fixed-rate, closed-end second lien at completion, leaving your first mortgage and its rate untouched. Local zoning decides what is allowed on your parcel.
Contact Three Stone Homes In Rogersville, Missouri
Three Stone Homes, Rogersville Headquarters
7575 E US Highway 60
Rogersville, MO 65742
Phone: 417-753-HOME (4663)
Website: Three Stone Homes
Hours: Monday to Friday 9 AM to 6 PM, Saturday 10 AM to 5 PM, Sunday closed
Jessica Edwards
Top Rated® Sr. Vice President
BuildBuyRefi.com, powered by The Federal Savings Bank
NMLS ID# 1629864
The Federal Savings Bank, NMLS #411500. FDIC insured, veteran owned, federally chartered, and licensed in all 50 states.
Where Three Stone Homes Delivers
Three Stone delivers within 75 miles of Rogersville, Harrisonville, and Lake of the Ozarks, covering the Springfield area, the south Kansas City metro into nearby Kansas, and the lake region. Our financing is licensed in all 50 states.
Learn more about manufactured home loans, compare our construction loan programs, or browse nearly 2,000 registered home builders on BuildBuyRefi.com.
Other Registered Builders Serving Missouri Buyers
As Seen In