Featured Registered Builder · Oklahoma & Arkansas
Build A Cottage, Cabin Or ADU With New Candle Cottages.Up To 100% Financing & *$50K Extra.
Factory-built cottages, cabins, and ADUs from Spiro, Oklahoma, set on your land and financed by a direct lender already approved with New Candle Cottages, including a 2nd lien option that leaves your first mortgage rate alone.
How Do You Finance A New Candle Cottages Home, Cabin, Or ADU?

New Candle Cottages is a registered builder with our bank, so buyers in Oklahoma and Arkansas can finance its factory-built cottages, cabins, and ADUs through BuildBuyRefi.com. Builders often resist a new lender because it means company financials, approval calls, and an unfamiliar draw process. New Candle Cottages has already cleared that step with us, so the only approval left is yours, which improves and speeds up the closing process.
When the home is permanently affixed to a foundation on land you own, construction financing applies, with up to 100% financing for eligible veterans or when land equity covers the down payment. Placing a cottage behind a home you already own? A 2nd lien construction loan can fund it without refinancing your first mortgage.
New Candle Cottages is a family-run builder in Spiro, Oklahoma, a few miles from the Arkansas line. Homes are designed with the buyer, built at the company's Spiro facility, then delivered and set on site. The lineup runs from compact one-bedroom cottages to The Weber, an 18 × 60 two-bedroom with more than 900 square feet, plus fully custom layouts.
New Candle Cottages clients work directly with Bobby Atkisson, Top Rated® Sr. Vice President & LPO Manager, NMLS ID# 28045, BuildBuyRefi.com, powered by The Federal Savings Bank, from the first eligibility question through delivery day.Factory Built Home Specialist | Construction And VA Construction | 24+ Years In Mortgage Lending
Cottages, Cabins, And Small Homes Built In Spiro, Oklahoma
Exteriors from the New Candle Cottages lineup: The Weber with black and white board-and-batten and clerestory windows, The Poolhouse with its modern shed roof, the lofted Fenton, The Rivers Edge, and one of the company's compact tiny homes.
Tap any photo to view it larger.


A Family Builder In Spiro, Building Small Homes To Order
New Candle Cottages designs and builds tiny homes, cottages, cabins, and custom sheds for buyers in Oklahoma and Arkansas. The company says every home is built to order and designed around the buyer's needs rather than sold from a fixed catalog. Buyers come to it for full-time homes, weekend retreats, guest houses, backyard offices, and rental-ready units.
Construction standards the builder lists include 2x4 framing at 16 inches on center, spray foam insulation, mini split heating and cooling, metal roofing, and double-pane vinyl windows, with full kitchen and bath fixtures. It states that its homes are built to IRC structural standards with NEC electrical and UPC plumbing, and it offers a one-year warranty.
The company also helps buyers research local zoning, prepare permit documentation, and coordinate inspections, which matters for cottages and ADUs where county and city rules vary.
Von HolwickBuilder and Craftsman. Leads the build crews and brings more than 35 years of construction experience, from framing through finish work.
Bryce HolwickVision and Sales. Works with buyers on what a small home can do for them, from a first cottage to a rental unit.
Aaron HolwickDesign and Customer Experience. Turns client ideas into drawings and floor plans, drawing on an engineering background.
Dalton BradshawKey contact for new projects and buyer questions at New Candle Cottages.
From First Sketch To Delivery Day, With The Loan Built In
New Candle Cottages runs a short, hands-on process. Here is where the financing steps fit inside it.
- Financing
Start With Your Land And The Right Loan
Bobby Atkisson confirms which path fits: a construction loan when the home will be affixed on land you own or are buying, a 2nd lien construction loan for a cottage behind your current home, or another route for smaller or non-affixed units.
- New Candle Cottages
Discovery And A Live Sketch
A call or showroom visit covers rooms, sizes, and site basics. Your salesperson sketches the plan with you in real time, and the designer turns it into buildable prints.
- New Candle Cottages
Showroom Selections And Pricing
You pick cabinets, counters, flooring, siding, and roof colors in person. The builder then prices the base build plus your options, with an estimated delivery window.
- Underwriting
Contract, Plans, And Appraisal
The signed contract, plans, and specs go to underwriting and to an independent appraiser. Foundation, delivery, set, and utility work belong in the contract so they can be part of the loan.
- Build
Construction At The Spiro Facility
The home is built in Spiro, with progress updates at framing, rough-in, and finishes. The builder states a typical pace of about 45 days from final design and pricing to delivery, depending on site and weather.
- Delivery
Set, Walkthrough, And Permanent Loan
The crew sets, levels, and walks the home with you. Draws are released after third-party inspection, and the loan moves to its permanent phase once the home is complete.
Tiny Homes, Cottages, ADUs, And Cabins: What New Candle Cottages Builds
A lineup of named models plus fully custom builds. How you plan to use the home points to the loan, so naming the use narrows the financing quickly.
Full-Time Cottages
Two-bedroom layouts like The Weber and The Pineview, for downsizing or a first home on rural land.
How It Can Be FinancedOne-Time Close, Two-Time Close, or Hybrid construction loanBackyard ADUs And Guest Houses
A second dwelling for a parent, an adult child, or guests on property you already own.
How It Can Be Financed2nd Mortgage Construction-to-Permanent, case by caseCabins And Weekend Retreats
The Ozark Getaway is offered for lake property, hunting land, guest use, or a downsized full-time home.
How It Can Be FinancedSecond home or primary residence constructionPoolhouses
The Poolhouse pairs one-bedroom living with sliding glass doors and an outdoor shower that opens to the bath.
How It Can Be Financed2nd lien on your current property, case by caseRental-Ready Units
The builder designs units for long-term tenants, vacation rentals, and small-scale rental communities.
How It Can Be FinancedInvestment construction, 1 to 4 units, by property typeFully Custom Layouts
Plans drawn from scratch, with options the builder lists such as built-in storage, lofts, and off-grid setups.
How It Can Be FinancedSame programs, based on size, foundation, and landListed Models At A Glance
- The Weber
- 18 × 60, 2 BR, 1 BA
- The Aspen
- 16 × 50, 1 BR + office
- The Ozark Getaway
- 14 × 56, 1 BR, 1 BA
- The Poolhouse
- 16 × 42, 1 BR, 1 BA
- The Fenton
- 14 × 42, 1 BR + loft
- The Pineview
- 14 × 36, 2 BR, 1 BA
Sizes as listed by New Candle Cottages. Models and specifications are the builder's and can change; confirm details with the builder.
Off-Frame Modular, Built To Code
New Candle Cottages describes its homes as off-frame modular builds made to IRC, NEC, and UPC standards. How a home is certified decides which loan programs apply, so Bobby confirms it for your model before you sign.
Inside A New Candle Cottage, And Delivery Day
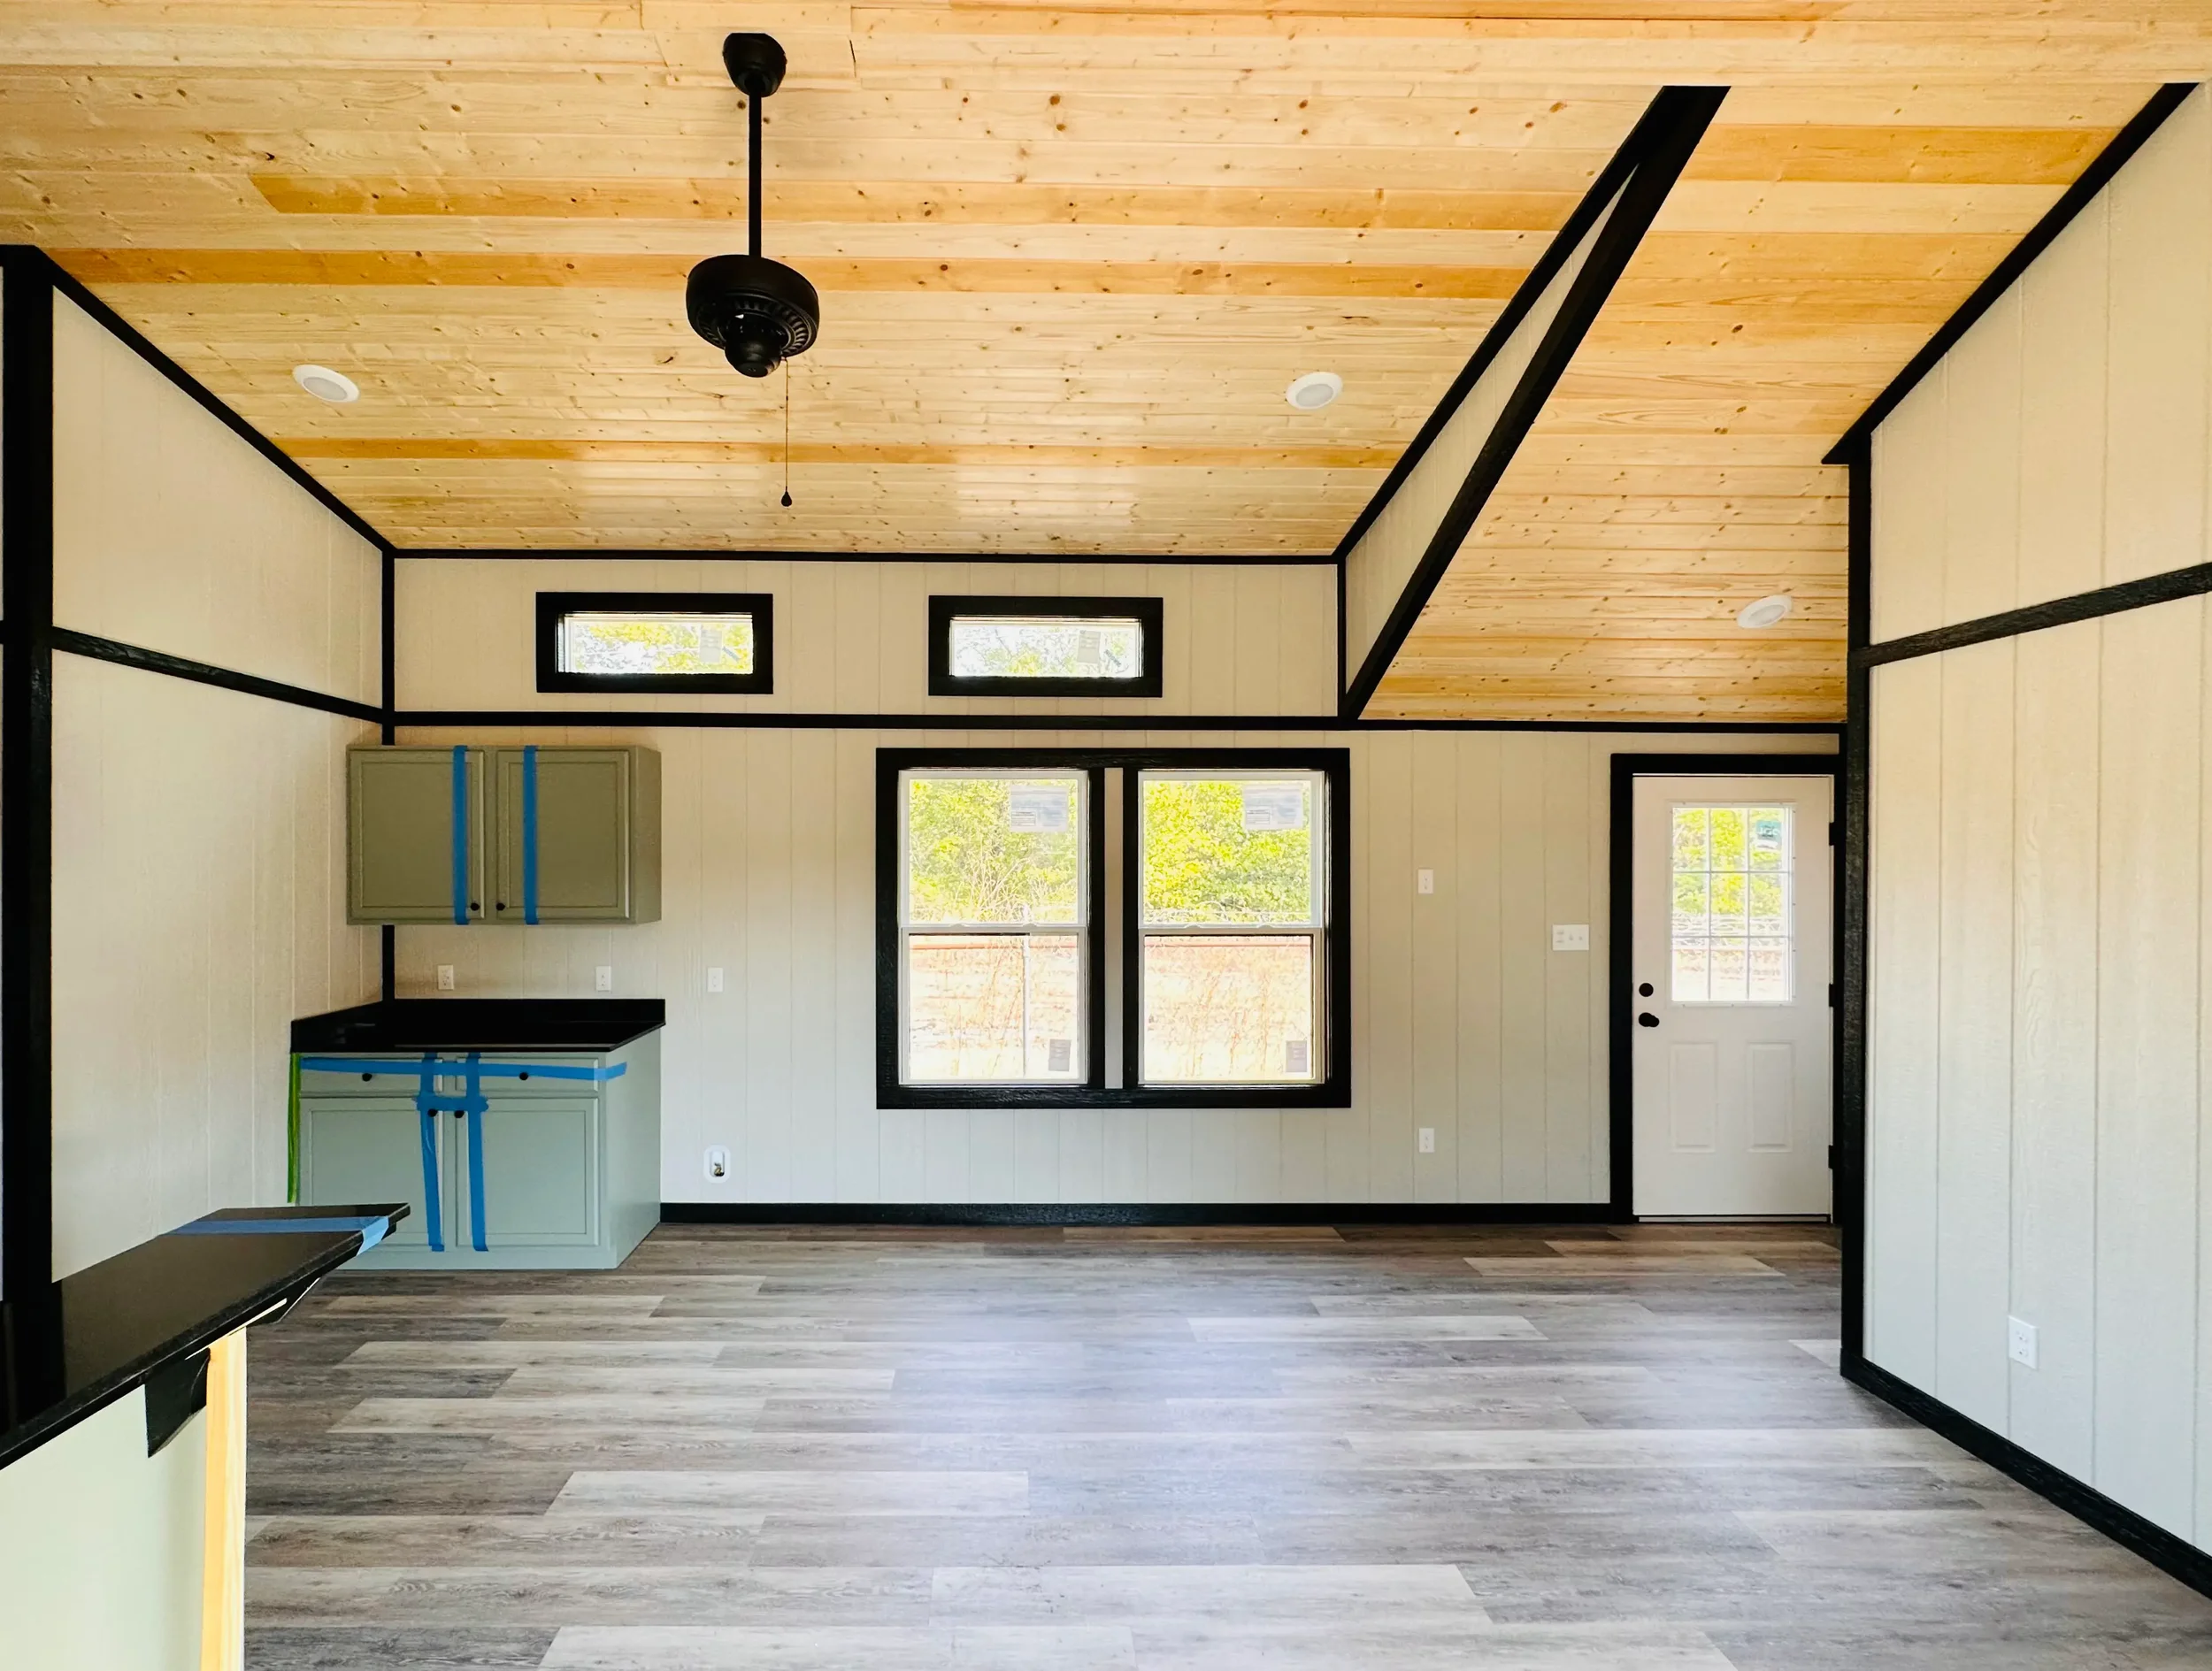
Open living and kitchen layouts, interior finishes, and a finished home on delivery day. New Candle Cottages delivers with crane service and sets the home on your prepared site.


Construction Loans For Factory-Built Cottages In Oklahoma And Arkansas
BuildBuyRefi.com is powered by The Federal Savings Bank, an FDIC-insured, veteran-owned direct lender licensed in all 50 states, NMLS #411500. A home bought from a builder like New Candle Cottages is still financed as a construction loan, because the loan pays for a home that is not built yet. See all construction loan programs and our manufactured and modular home loans.
Three Ways To Structure The Loan
One Application, One Closing
Permanent terms are locked at the first closing, and the loan converts once the home is set and finished, with no second qualification and no second appraisal.
Rate Decided At The Finish
The construction loan and the permanent loan close separately, so the permanent rate is chosen once the home is complete. FHA and VA permanent loans can streamline at that point.
Our In-House Middle Path
Both document sets are prepared upfront, so it closes like a single loan with one set of fees while the permanent rate stays flexible until completion. FHA and VA streamline eligible in qualifying scenarios. Brokers and correspondents cannot offer it.
Program Details At A Glance
- Conventional, FHA, VA minimum score
- 640
- VA construction, eligible veterans
- Up to 100%
- Minimum home size
- 400 sq ft
- Land
- Owned or bought at closing
- Second home construction
- Available
- Investment construction minimum score
- 680 to 700
- ITIN construction minimum score
- 680
- Administrative fees
- None
Homes under 400 square feet are reviewed case by case on approval. Credit, occupancy, certification, and property type determine final eligibility.
Zero Down Through Land Equity
Eligible veterans with full entitlement can finance up to 100%. For other buyers, owned land is the usual path to zero down. Land you already own, or buy at closing, can be applied to the down payment and can cover it entirely when the equity is enough, which suits the rural acreage and lake lots where many cottages end up.
Direct Lender, No Fee Layers
A broker hands your file to another lender, and a correspondent sells the loan after closing. We underwrite, fund, and manage draws in-house. Our construction programs carry no administrative fees, where broker and correspondent construction loans often stack $40,000 to $100,000 or more in fees.
All programs are subject to credit qualification, property eligibility, reserve requirements, and applicable program guidelines. Rates, terms, and availability vary by borrower, property, occupancy, and loan amount, and are not guaranteed. Appraisals are performed by independent licensed appraisers and construction inspections by third-party inspectors. Contact your banker for applicable rates, terms, and conditions.
*$50,000
Extra Funds For What A Small-Home Contract Leaves Out
Qualified borrowers can access up to $50,000 in separate, unsecured funds before, at, or after closing, underwritten in-house at the same time as the mortgage. It is never rolled into the construction loan and does not rely on home equity.
How New Candle Cottages Buyers Could Use It
A custom shed or workshop
New Candle Cottages builds storage sheds too. A shed is not mortgage eligible on its own, but these funds can cover one when paired with a primary BBR mortgage on the property.
A smaller guest unit
A bunkhouse or studio under 400 square feet, or one not on a permanent foundation, can be funded this way alongside a BBR mortgage.
Furnishing a compact home
Built-ins help, but beds, seating, rugs, and window coverings for a new cottage still add up.
Porches, decks, and steps
Outdoor living space added after move-in, when it was not written into the build contract.
Driveway and outdoor touches
Gravel, plantings, a fire pit, or a carport finished after the home is set.
Consolidating debt to qualify
Paying down revolving balances can improve debt-to-income, which in some scenarios helps a buyer qualify for the loan.
*Up to $50,000 is available to qualified borrowers and can be applied across our loan programs. This is a separate unsecured consumer loan underwritten in-house at the same time as the mortgage. Proceeds cannot be used for a down payment. Approval, amount, rates, and terms depend on credit qualification and are not guaranteed. Contact your banker for applicable rates, terms, and conditions.
What We Can And Cannot Finance With New Candle Cottages
New Candle Cottages builds a wider range of structures than a mortgage can cover. Here is where the line sits, including the paths for homes that fall outside a standard construction loan.
What We Can Finance
- Cottages, cabins, and small homes permanently affixed to a foundation on land owned or bought at closing
- Homes of 400 square feet or more, with smaller homes reviewed case by case on approval
- A New Candle Cottages ADU behind your current home through a 2nd lien construction loan
- Primary residence and second home construction
- Rental cottages under investment construction, 1 to 4 units
- Larger groups of rental units or small communities, reviewed case by case
- Chattel financing, case by case, for homes that will not sit on land you own
What We Cannot Finance
- Stand-alone sheds and storage buildings on a mortgage
- Homes classified as manufactured, when financed as investment property
- Self-build or owner-as-contractor arrangements
- Used homes, or moving and relocating an existing home
- Work left out of the build contract, which cannot be added to the construction loan after closing
The appraisal is completed by an independent appraiser from the land, plans, and specifications, and we have no influence over the value. Construction inspections are done by third-party inspectors.
 The Weber · Full Bath
Add A New Candle Cottages ADU Without Refinancing Your Home
Many homeowners locked first mortgage rates between 2.5 and 4.0 percent in 2020 and 2021. A cash-out refinance to pay for a guest cottage trades that rate on the entire balance. Our 2nd Mortgage Construction-to-Permanent loan funds the cottage in inspected draws, then converts to a fixed-rate, closed-end second lien. Your first mortgage and its rate stay as they are. More in our ADU financing guide.
New Candle Cottages Projects This Loan Fits
A Cottage For A Parent
A one-bedroom layout like The Fenton placed near the main house, so an aging parent lives close but independently.
A Second Home On Family Acreage
A full two-bedroom cottage on the back of a farm or rural parcel you own, for an adult child or relative.
A Poolside Guest House
The Poolhouse is designed for placement near a pool, with an outdoor shower that opens straight to the bath.
A Studio Or Home Office
A dedicated workspace with full systems, like the office layout in The Aspen, steps from the house.
No set maximum. Each 2nd lien project is reviewed case by case on the project, your equity, and your credit. Local zoning decides whether a second dwelling is allowed on your lot.
Subject to credit qualification, property eligibility, lien position, available equity, appraisal, and applicable program guidelines. Rates and terms vary by borrower and property and are not guaranteed. Local zoning and permitting govern what may be built on any property. Contact your banker for applicable rates, terms, and conditions.
Up To 30% Commission Savings When You Buy Land Or Sell A Home
A cottage project often comes with another transaction: land to buy first, or a current home to sell before the move. Qualified borrowers can save up to 30% on real estate commissions through our participating agent network in all 50 states, applied as a closing cost credit or toward a rate buy-down. How commission savings work.
What this covers and what it does not. The benefit applies only to agent-represented transactions: selling an existing home, buying an existing listed home, or buying land listed with an agent. It does not apply to buying a home from New Candle Cottages, which is a direct contract with the builder and involves no listing agent or commission.
No money changes hands between us and the agents in either direction. We do not pay them, they do not pay us, and we earn nothing when a borrower uses one. Paying or receiving fees for referrals of federally related mortgage loans is prohibited by law, and we do not do it.
Commission savings are available to qualified borrowers through a participating real estate agent network, subject to agent availability, program terms, and applicable state law. Savings apply to the fee received by the participating brokerage representing the borrower and are applied toward closing costs. Actual savings vary by property, sale price, and agreement. This benefit does not apply to the direct purchase or construction of a new home from a builder. No referral, affiliate, or other fee is paid or received by BuildBuyRefi.com or The Federal Savings Bank in connection with this benefit.
Meet Bobby Atkisson, The Banker Assigned To New Candle Cottages Clients
Bobby Atkisson
Top Rated® Sr. Vice President & LPO Manager
BuildBuyRefi.com, powered by The Federal Savings Bank | NMLS ID# 28045
Bobby leads the BuildBuyRefi.com team as Senior Vice President and LPO Manager at The Federal Savings Bank. He brings more than 24 years of mortgage lending experience, including more than 20 years leading sales teams, and a degree in finance with a real estate minor. He works with borrowers in all 50 states, in person or remotely.
His Factory Built Home Specialist designation fits this builder directly. A home built off site, delivered, and set on a foundation follows different steps than a house framed on the lot, from how the builder bills to how the draws are scheduled. His construction, VA construction, and veteran lending work covers the rest.
What Bobby handles for a New Candle Cottages buyer: matching the program to your model and land, applying land equity, and keeping draws in step with the build and delivery schedule. Read Bobby's full bio.
 Spiro, Oklahoma · The Weber
Check Your Eligibility To Build With New Candle Cottages
A few quick questions show which programs fit your land, your home, and how you plan to use it. No credit pull, no Social Security number, and no obligation. Your answers go to Bobby Atkisson and to New Candle Cottages.


Schedule A Call With Bobby Atkisson
Pick a time that works. Bring your land details (location, utilities, and access), the model or layout you like, and how you plan to use the home, and Bobby will walk through which programs fit.
Frequently Asked Questions About New Candle Cottages Financing
What Oklahoma and Arkansas buyers ask most before financing a cottage, cabin, or ADU from New Candle Cottages.
Where does New Candle Cottages build and deliver?
New Candle Cottages builds its homes at its facility in Spiro, Oklahoma, near Fort Smith, and delivers throughout Oklahoma and Arkansas, including the Tulsa, Oklahoma City, Fort Smith, and Little Rock areas. Our financing is available in all 50 states.
Can I get a mortgage on a New Candle Cottages home?
Yes, when the home is permanently affixed to a foundation on land you own or buy at closing and is at least 400 square feet. It is financed as a construction loan, and smaller homes are reviewed case by case on approval. How a model is certified decides which programs apply, so Bobby Atkisson confirms that before you sign.
Can I add a New Candle Cottages ADU without refinancing my first mortgage?
Yes. Our 2nd Mortgage Construction-to-Permanent loan funds the cottage during construction and converts to a fixed-rate, closed-end second lien when it is finished, so your first mortgage keeps its rate and balance. There is no set maximum; each project is reviewed case by case.
What if the home will not be on land I own, or is under 400 square feet?
Those homes fall outside a standard construction loan. Chattel financing is reviewed case by case for homes that will not sit on land you own. Smaller structures, such as a bunkhouse under 400 square feet, can be covered with our separate consumer loan of up to $50,000 when it is paired with a primary BBR mortgage on the property.
Can I build a New Candle Cottages home with zero down?
In qualifying scenarios, yes. Eligible veterans with full entitlement can finance up to 100%. For other buyers, land equity is the path to zero down: land you already own, or buy at closing, can be applied toward the down payment and can cover it entirely when the equity is sufficient.
Can I finance a rental cottage or a weekend cabin from New Candle Cottages?
Yes, in qualifying scenarios. Second home construction covers a weekend or lake cabin, and investment construction covers 1 to 4 units. A home classified as manufactured cannot be financed as investment property, so certification matters for rental plans.
Why does it matter that New Candle Cottages is already a registered builder?
A lender with no builder relationship has to collect the builder's financials, review them, and set up a draw process before your loan can move, and many builders are slow to repeat that for one buyer.
New Candle Cottages is already registered with our bank, so that work is done. The only approval left is yours, which improves and speeds up the closing process.
What credit score do I need for a construction loan?
The minimum is 640 on Conventional, FHA, and VA construction programs. ITIN construction requires 680, and investment construction requires 680 to 700 depending on loan-to-value. Bobby Atkisson can review where you stand before you apply.
Contact New Candle Cottages In Spiro, Oklahoma
Visit the showroom and build facility in Spiro, or start with the financing to learn what your land and project can support.
New Candle Cottages
Key contact: Dalton Bradshaw
Team: Von, Bryce, and Aaron Holwick
1815 E Broadway St
Spiro, OK 74959
Phone: (918) 962-0023
Email: sales@newcandlecottages.com
Website: newcandlecottages.com
Hours: Monday to Friday, 8:30 AM to 5 PM. Closed Saturday and Sunday.
Bobby Atkisson
Top Rated® Sr. Vice President & LPO Manager
BuildBuyRefi.com, powered by The Federal Savings Bank
NMLS ID# 28045
The Federal Savings Bank, NMLS #411500. FDIC insured, veteran owned, federally chartered, and licensed in all 50 states.
Designed With You, Built In Spiro, Set On Your Land
A family team, a showroom for in-person selections, and plans sketched around your list. New Candle Cottages answers the design and building questions. Bobby Atkisson answers the financing questions, and both can happen before you sign anything.
Where New Candle Cottages Builds And Delivers
From Spiro, in Le Flore County near Fort Smith, New Candle Cottages delivers throughout Oklahoma and Arkansas. These are the areas the builder names on its site.
Oklahoma
Arkansas
For buyers searching for a tiny home builder near Tulsa or Oklahoma City, ADU and cottage builders near Fort Smith, cabin builders in the Arkansas River Valley or Hot Springs, or off-frame modular homes in Eastern Oklahoma, this is New Candle Cottages' territory.
On the lending side there is no geographic limit. BuildBuyRefi.com is licensed in all 50 states, so financing works anywhere New Candle Cottages delivers, including for buyers relocating to Oklahoma or Arkansas.
More Registered Builders For Cabins, Cottages, And Factory-Built Homes
New Candle Cottages is one of nearly 2,000 builders and dealers registered with our bank.
Financing Resources
As Seen In