Featured Registered Builder · Greater Los Angeles
Design, Build Or Rebuild With Letter Four.Up To 100% Financing & *$50K Extra.
Jumbo construction loans up to $4.5 million, fire rebuild and ADU financing, and remodel loans that leave your first mortgage untouched, from a direct lender already approved with Letter Four's licensed architects and general contractors.
How Do You Finance A Custom Home, Fire Rebuild, Or Remodel With Letter Four?

Letter Four, Inc. is a registered builder with our bank, so homeowners across Greater Los Angeles can finance a new custom home, a ground-up fire rebuild, an ADU, or a major remodel with Letter Four through BuildBuyRefi.com. That includes jumbo construction up to $4.5 million, remodel financing up to $2.5 million on a first lien, and up to 100% financing for eligible veterans or for borrowers whose land equity covers the down payment.
The builder side of the approval is already finished. Most builders resist a new lender because it means another round of company financials, approval calls, and a draw process they have never used. With Letter Four already approved, the only approval left is yours, which improves and speeds up the closing process.
Letter Four is a design-build firm based in Los Angeles, founded in 2010 by architect Lauren Adams and general contractor Jeremy Baker. Architecture, construction, interior design, and landscape design run under one roof, so the people who draw the home are the same people who build it.
That structure fits construction lending well. A lender underwrites a build from three things: the plans, the specifications, and an all-in budget. Letter Four produces all three inside one firm, and our bank underwrites, funds, and manages the draws inside one bank. Nothing on either side gets handed to an outside party.
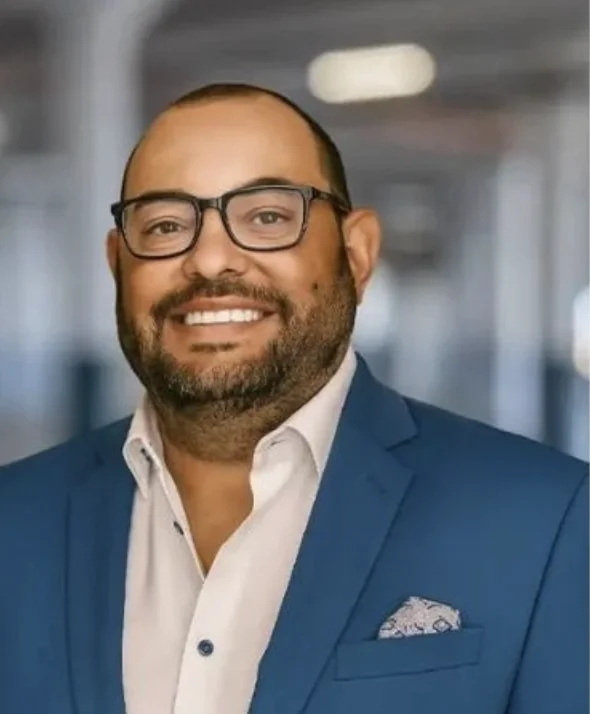
Letter Four clients work directly with Bobby Atkisson, Top Rated® Sr. Vice President & LPO Manager, NMLS ID# 28045, BuildBuyRefi.com, powered by The Federal Savings Bank, from the first eligibility question through the final draw.Jumbo, Construction, And Renovation Financing | 24+ Years In Mortgage Lending
Malibu English Country Home, Designed And Built From The Ground Up
A new English Country residence in Malibu with a backyard pool, a glass-walled sunroom, and interiors carried through the living room and primary suite. Letter Four drew it, engineered it, and built it with one team.
Tap any photo to view it larger.


An Architect And A General Contractor, Running One Firm
Letter Four was built around a problem anyone who has hired an architect and a contractor separately will recognize. The architect prices the design without knowing what it costs to build. The contractor quotes a price per square foot with no design behind it. The gap between those two numbers is where budgets break.
Letter Four closes that gap by putting licensed architects, licensed general contractors, interior designers, and landscape designers on one team from the first conversation. The firm's stated aim is an all-in budget known on day one, covering surveys, engineering, consultants, permitting, finishes, and landscaping, not only hard construction costs.
The work runs from new custom homes and full-scale remodels to additions, seismic retrofits, ADUs, and ground-up fire rebuilds, plus commercial and hospitality projects across Los Angeles. Styles range from Craftsman and Mid-Century to Mediterranean, Tudor, and Contemporary, and the firm says no two of its designs are repeated.
This is masterful work, and it sits in a different class from the typical tract or production builder. The galleries on this page show why.
Lauren AdamsLicensed Architect and Co-Owner. Leads the architectural design team. Clients in Letter Four's reviews repeatedly mention her eye for design and finish selections.
Jeremy BakerLicensed General Contractor, CEO and Co-Owner. Runs construction, project management, and the build team, and is the contact clients describe when problems surface mid-project.
Licensed In CaliforniaArchitecture License #C30146 and Contractor License #B1028949, as listed by Letter Four. Office at 12822 Washington Blvd. in Los Angeles.
 BBB A+ AccreditedAccredited with the Better Business Bureau since 2025
The Letter Four Design-Build Process, With The Construction Loan Built In
Six stages, in order. The financing steps sit inside Letter Four's own planning sequence, so the design budget, the loan amount, and the draw schedule all describe the same project.
- Financing
Set The Budget Ceiling With Bobby Atkisson
Before design starts, Bobby reviews which structure fits: Jumbo One-Time Close, Jumbo Two-Time Close, our Hybrid Construction Loan, VA, or a renovation program, and how much land equity applies.
- Letter Four Action Plan
Due Diligence On The Site
Letter Four reviews the property, past permit records, code limits, and project constraints so surprises surface before drawings, not during construction.
- Letter Four Action Plan
Conceptual Design And Preliminary Pricing
Design options are sketched against the site and the budget, followed by an all-in pricing assessment. This is the number that should match the loan.
- Design And Permits
Schematics, Construction Documents, Permits
3D modeling, engineering coordination, the construction drawing set, and agency approvals, handled in-house. The finished plans, specs, and contract go to underwriting and to the independent appraiser.
- Close And Build
Loan Closes, Construction Starts
Land equity is applied at closing. During the build, each draw releases only after a third-party inspection confirms the work, and our bank funds every draw in-house. Letter Four's design team stays on site through construction administration.
- Completion
Final Walkthrough And Permanent Loan
Once the home is complete, the loan moves to its permanent phase, automatically on a One-Time Close or through the second closing on a Two-Time Close or Hybrid.
Custom Home Builder, Architect, And Remodeling Contractor In Los Angeles
Letter Four takes on six kinds of residential work. Each points to a different loan, so naming the project narrows the financing quickly.
New Custom Homes
Ground-up homes designed for the specific site, from English Country and Mediterranean to modern three-story builds with pools and outdoor living.
How It Can Be FinancedJumbo construction up to $4.5 million, or conforming, FHA, and VA constructionFire Rebuilds
Ground-up rebuilds in Altadena, Pacific Palisades, and Malibu, using concrete, all-steel framing, steel modular, and fire-resistant design methods.
How It Can Be FinancedConstruction loan with lot and land equity applied, all programsMajor Remodels And Additions
Whole-home remodels, relocated kitchens, rear extensions, roofline changes, and primary suite additions on existing homes.
How It Can Be FinancedJumbo Renovation, FHA 203K, HomeStyle, VA Renovation, or 2nd lienADUs And Guest Houses
Detached accessory dwelling units, like the modern Scandinavian ADU shown below, for family, guests, or rental use.
How It Can Be Financed2nd Mortgage Construction loan that keeps your first mortgage rateSeismic Retrofits
Structural upgrades to older Los Angeles homes, often paired with a larger remodel while walls and foundations are open.
How It Can Be FinancedIncluded in a renovation or 2nd lien project, case by caseMulti-Unit Residential
Apartment and condo buildings and other commercial residential work, alongside Letter Four's retail and hospitality projects.
How It Can Be Financed1 to 4 unit construction, larger multi-unit and subdivisions case by caseInterior design and landscape architecture are part of the same contract. On a financed build, that matters: finishes and landscaping written into the build contract can be part of the construction budget, instead of out-of-pocket costs after move-in.
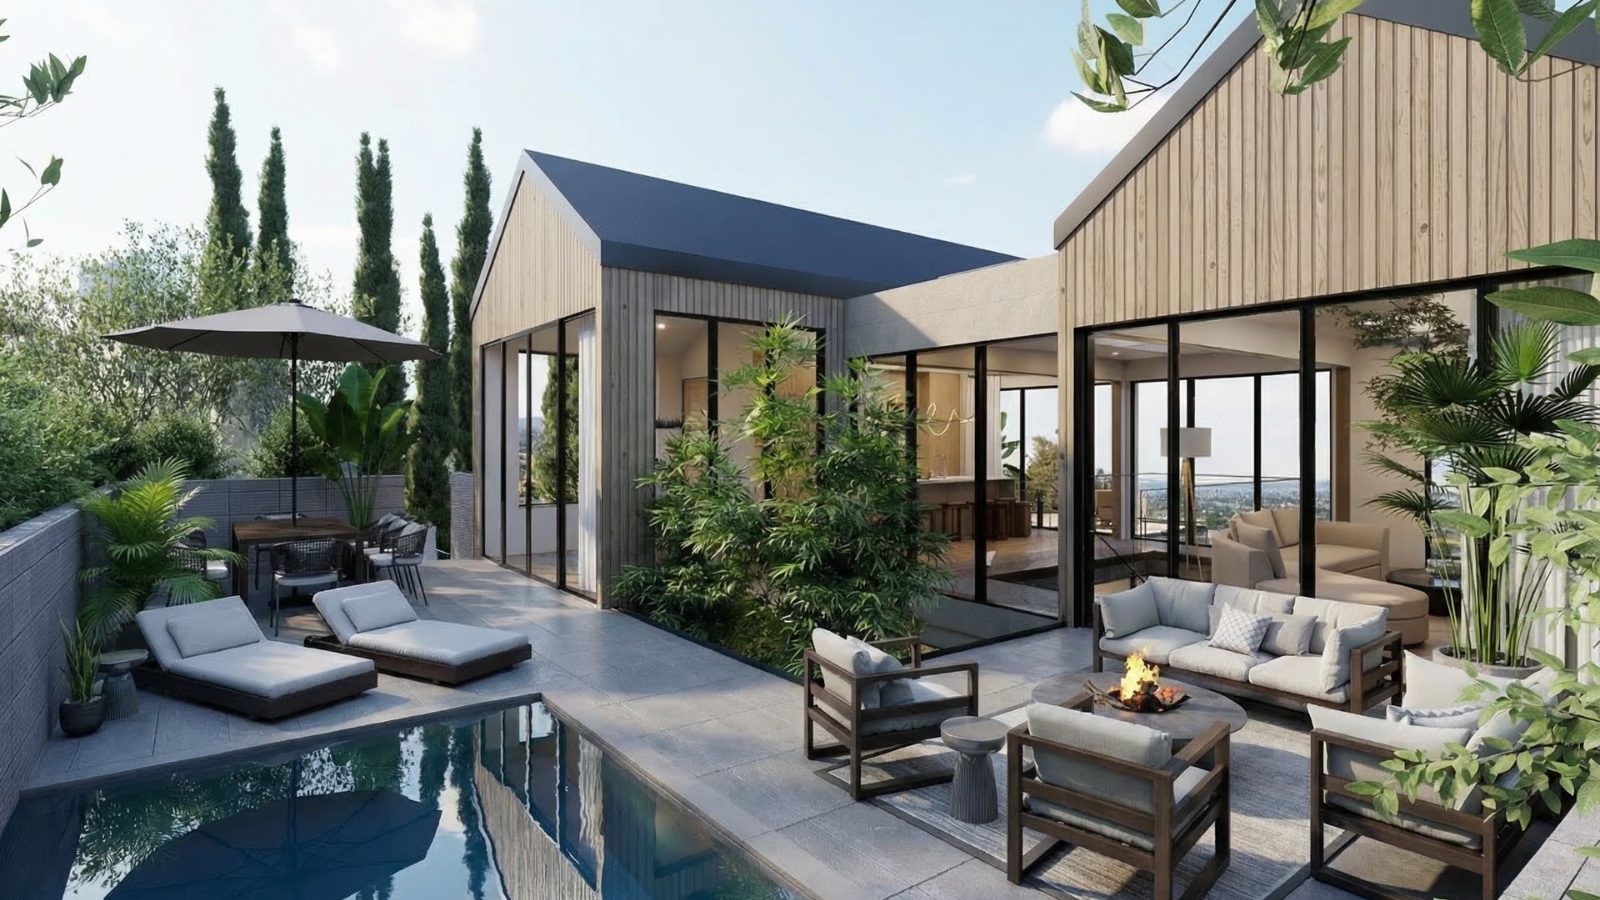
Modern Three-Story California Home With Pool And Skylit Great Room
A new three-story modern home with a sculptural entry stair, a skylit living and kitchen space opening to wide views, a rear pool with outdoor living, and a primary bath built as a place to unwind.
Every room here came out of the same design set and the same build team.




Jumbo Construction Loans Up To $4.5 Million For Los Angeles Custom Homes
BuildBuyRefi.com is powered by The Federal Savings Bank, an FDIC-insured, veteran-owned direct lender licensed in all 50 states, NMLS #411500. Most construction lenders stop well short of Los Angeles price points, and many that offer jumbo construction broker it out. Ours is underwritten, funded, and managed in-house.
Three Ways To Structure The Loan
Qualify Once, Close Once
The permanent terms are set at closing, and the loan converts at completion with no re-qualification and no second closing. Our One-Time Close Jumbo is available for primary residence construction, with an interest-only construction period of up to 18 months.
Set The Rate At Completion
Construction and permanent financing close separately, so the permanent rate is set when the home is finished. The Jumbo Two-Time Close covers primary residences and second homes, with a 6-month extension option at no cost when requested in advance.
One Closing Feel, Flexible Rate
Built in-house. Both sets of loan documents are prepared upfront, so it runs like a single close with one set of fees while the permanent rate stays open until completion. FHA and VA streamline eligible in qualifying scenarios. A broker or correspondent lender cannot offer it.
Program Details At A Glance
- Jumbo construction loan amount
- Up to $4.5M
- Jumbo minimum credit score
- 720
- Credit Committee review
- Above $2.5M
- Conventional and FHA minimum score
- 640
- VA construction, eligible veterans
- Up to 100%
- VA loan size
- $1.5M, up to $3M by exception
- ITIN construction minimum score
- 680
- Investment construction
- 1 to 4 units
- Administrative fees
- None
Jumbo reserve requirements scale with loan size. Credit, occupancy, and property type determine final eligibility.
Zero Down Without Being A Veteran
Up to 100% financing is available to eligible veterans with full entitlement. For everyone else, land equity is the path to zero down. Lot and land you own, including a lot cleared after a fire, can be applied toward the down payment, and in qualifying scenarios it can cover the down payment entirely.
Why A Direct Lender Matters At This Size
A broker passes your file to another lender. A correspondent closes your loan, then sells it, and an outside investor's rules take over. We originate, underwrite, fund, and manage every draw in-house, so a question halfway through framing gets answered by people who work here.
No administrative fees on our construction programs. Fee layers of $40,000 to $100,000 or more appear on many broker and correspondent construction loans, and on a large build they can push the loan past what the home appraises for. Ask for every fee line by line on any quote you compare.
All programs are subject to credit qualification, property eligibility, reserve requirements, and applicable program guidelines. Rates, terms, and availability vary by borrower, property, occupancy, and loan amount, and are not guaranteed. Appraisals are performed by independent licensed appraisers and construction inspections by third-party inspectors. Contact your banker for applicable rates, terms, and conditions.
*$50,000
Extra Funds For What Even A Large Build Contract Leaves Out
Qualified borrowers can access up to $50,000 in separate, unsecured funds before, at, or after closing, underwritten in-house alongside the mortgage. It does not rely on equity and it does not affect loan-to-value. We are not aware of another lender in this space offering it.
How Letter Four Clients Could Use It
Furnishing a larger home
A construction loan builds the house. It does not fill it. Furniture, rugs, art, and window treatments for a custom home add up fast.
Living costs during a rebuild
Rent and storage while a fire rebuild is under way, especially after insurance living-expense coverage runs short of the build schedule.
Selections decided late
The tile, plumbing fixtures, or decorative lighting chosen during Letter Four's interior design phase that ran past the original allowance.
Landscape and outdoor additions
Plantings, outdoor furniture, an outdoor kitchen, or a fire feature added after the first season in the home.
A cushion for change orders
Separate funds already approved keep a mid-build decision from stalling the project while a change order is priced.
Consolidating debt to qualify
Paying down revolving balances can improve the debt-to-income ratio, which in some scenarios helps a borrower qualify for the loan size the project needs.
*Up to $50,000 is available to qualified borrowers and can be applied across our loan programs. This is a separate unsecured consumer loan underwritten in-house at the same time as the mortgage. Proceeds cannot be used for a down payment. Approval, amount, rates, and terms depend on credit qualification and are not guaranteed. Contact your banker for applicable rates, terms, and conditions.
Fire Rebuild Financing With A Builder Who Specializes In Non-Combustible Construction
Letter Four focuses its rebuild work on fire resistant and non-combustible construction for homeowners who lost homes in Altadena, the Palisades, and Malibu. The firm presents four construction methods, each of which it says has been built, permitted, and occupied in Los Angeles.
Cast-In-Place Concrete
A fully non-combustible structure. Letter Four describes concrete walls as recognized by California insurers as a reduced-risk build.
All-Steel Framing
Framing that Letter Four says meets California's High Fire Severity Zone standards.
Steel Modular
Fire-hardened modular shells built offsite while permits are processed, which Letter Four uses to compress rebuild timelines.
Fire-Resistant Design
Ember-resistant vents, Class A roofing, fire-rated assemblies, and defensible landscape planning.
How We Finance A Fire Rebuild
Your Lot And Land Equity Count Together
After a total loss, the lot itself still carries value. Lot equity and land equity together count toward the down payment, and in qualifying scenarios that equity can cover it entirely, with no cash down.
Insurance Settlement Funds
Dwelling coverage set aside for rebuilding can be applied toward the project in qualifying scenarios. How the funds are handled is reviewed against your policy and settlement terms.
A Remaining Mortgage On The Lot
Insurance often pays off the existing mortgage after a fire. If a balance does remain, it can be paid off at closing and rolled into the construction loan, so the lot and the new home end up in one loan.
Every Structure And Method Qualifies
One-Time Close, Hybrid, Two-Time Close, Jumbo, second home, and investment construction all apply to a rebuild. Concrete, steel frame, and modular construction are all eligible property types.
A rebuild has two clocks: permits and insurance. Talking to Bobby Atkisson while Letter Four is still in due diligence lets the loan amount, the settlement, and the all-in budget be lined up before plans go to the city or county.
Fire rebuild financing is subject to credit qualification, appraisal, title review, insurance settlement terms, and applicable program guidelines. Use of insurance proceeds depends on the policy, the settlement, and any lienholder requirements. Construction methods, insurability claims, and timelines described here are Letter Four's and are not guaranteed by the bank.
A Pacific Palisades Home, Rebuilt From The Ground Up After The Fire
A complete ground-up rebuild in Pacific Palisades: new front elevation, a backyard deck and patio, an open kitchen and dining room, and a calm primary bedroom.
This is the work Letter Four now centers on, for families who want a home that is safer and more insurable than the one they lost.


What We Can And Cannot Finance With Letter Four
Letter Four builds more than our bank finances. Its restaurants, hotels, offices, and retail spaces are proof of the firm's range, but they are not residential mortgages. Here is where the line sits.
What We Can Finance
- New custom homes as a primary residence, second home, or investment property, on land owned or bought at closing
- Ground-up fire rebuilds, with lot and land equity applied
- Jumbo construction up to $4.5 million, case by case
- Teardown and rebuild projects under our construction programs
- Remodels up to $2.5 million on a first lien, higher with Loan Committee approval
- ADUs and remodels on a 2nd lien, case by case, keeping your first mortgage in place
- 1 to 4 unit residential, with larger multi-unit residential and subdivisions reviewed case by case
- Concrete, steel frame, and modular construction, and pools written into the build contract when the appraisal supports them
What We Cannot Finance
- Retail, office, restaurant, and hospitality projects, even though Letter Four builds them
- Mixed-use properties that combine commercial and residential space
- Self-build or owner-as-contractor projects of any kind
- Land titled to someone else that is not being transferred to the borrower
- Work left out of the build contract, which cannot be added to the construction loan after closing
A design-build advantage worth knowing. Our construction underwriting looks at the total cost to build, including hard costs, soft costs, land, and closing costs. With Letter Four, design, engineering, and permitting are documented in the same contract as the construction, which gives underwriting one clear, complete budget to review.
The appraisal is completed by an independent appraiser from the land, plans, and specifications, and we have no influence over the value. Anything you want financed belongs in the contract before closing.
ADU Financing For A Letter Four Guest House, Without Refinancing Your Home
This modern Scandinavian ADU shows what a backyard unit can be in Letter Four's hands: an open living and kitchen floor plan, a full primary bedroom, and a bath with a walk-in shower and vanity.
Most Los Angeles homeowners who want an ADU already have a first mortgage at a rate they will not get again. Our 2nd Mortgage Construction-to-Permanent loan builds the ADU without touching that first lien.


Keep Your First Mortgage Rate
The ADU is funded in inspected draws, then converts to a fixed-rate, closed-end second lien. Your first mortgage keeps its original rate and balance.
Family, Guests, Or Rental Income
A parent nearby, an adult child at home, a home office, or a long-term rental unit. How you plan to use it shapes the review, so tell Bobby up front.
Or Build It With The Main House
Planning a new home or a fire rebuild? An ADU drawn into the same plans can be financed in the same construction loan, in qualifying scenarios.
Home Remodel Financing Up To $2.5 Million, Or A 2nd Lien That Keeps Your Rate
Letter Four's remodels are not cosmetic. Its clients describe moved kitchens, rebuilt rooflines, enclosed decks turned into primary baths, extended rear halves, and homes taken back to new plumbing and electrical. Work at that scale needs real construction financing, and we offer two paths as a direct lender.
Jumbo Renovation And Renovation Loans
Our Jumbo Renovation program finances up to $2.5 million in first lien position, and higher with Loan Committee approval, for primary residences and second homes. It fits a home you are buying to remodel or a refinance you were planning anyway.
For conforming amounts, Bobby Atkisson is an FHA 203K, FNMA HomeStyle, and VA Renovation Specialist and can compare those programs side by side.
2nd Mortgage Construction-To-Permanent
A large share of homeowners locked first mortgage rates between 2.5 and 4.0 percent in 2020 and 2021. A cash-out refinance trades that rate on the entire balance, which can cost more over time than the remodel itself.
Our 2nd lien construction loan funds the remodel in inspected draws and converts to a fixed-rate, closed-end second lien. Only the new money carries a new rate. Jumbo-size projects are reviewed case by case.
Letter Four Projects These Loans Fit
Kitchen And Dining Remodels
Relocated kitchens, opened walls, custom cabinetry, and dining spaces joined to the kitchen.
Mid-Century Modern Restorations
1940s and 1950s homes updated for the first time in decades, keeping the character.
Rear And Second-Story Additions
Extended back halves, new rooflines, and added bedrooms without giving up the yard.
Primary Suite And Bath Additions
A deck enclosed into a primary bath, or a new suite with its own closet and bath.
Whole-Home Systems Replacement
New plumbing, electrical, and interiors coordinated under one contract and one schedule.
Seismic And Structural Upgrades
Retrofit and structural repair folded into a larger remodel while the house is open.
Subject to credit qualification, property eligibility, lien position, available equity, appraisal, and applicable program guidelines. Loan amounts above standard program limits require Loan Committee approval. Rates and terms vary by borrower and property and are not guaranteed. Local zoning and permitting govern what may be built on any property. Contact your banker for applicable rates, terms, and conditions.
Remodels, Kitchen Upgrades, And Commercial Residential Work
A Mid-Century Modern home remodeled outside and in, two kitchens taken from dated to custom, and a multi-unit apartment and condo building from Letter Four's commercial residential portfolio.
Multi-unit residential and subdivision projects can be financed case by case. Retail and hospitality projects cannot.


Save Up To 30% On Real Estate Commissions When You Sell A Home Or Buy A Lot
Many Letter Four projects come with another transaction attached: a current home to sell, or a lot to buy first. Qualified borrowers can save up to 30% on real estate commissions on those transactions through our participating agent network, applied as a closing cost credit or toward a rate buy-down.
Selling Your Current Home
Moving into a new custom home usually means selling the one you are in. On a Los Angeles sale price, a share of the commission is real money.
Buying An Agent-Listed Lot
Buying a buildable or fire-cleared lot listed with an agent? The network can represent that purchase, and the savings apply there too.
Credit Or Rate Buy-Down
Take the savings as a credit toward closing costs or put it toward a lower rate. Bobby can run both and show which helps more.
What this covers and what it does not. The benefit applies only to agent-represented transactions: selling an existing home, buying an existing listed home, or buying land listed with an agent. It does not reduce the cost of a home designed and built by Letter Four. A design-build contract is a direct agreement with the builder, with no listing agent and no commission involved.
No money changes hands between us and the agents in either direction. We do not pay them, they do not pay us, and we earn nothing when a borrower uses one. Paying or receiving fees for referrals of federally related mortgage loans is prohibited by law, and we do not do it.
Commission savings are available to qualified borrowers through a participating real estate agent network, subject to agent availability, program terms, and applicable state law. Savings apply to the fee received by the participating brokerage representing the borrower and are applied toward closing costs. Actual savings vary by property, sale price, and agreement. This benefit does not apply to the direct purchase or construction of a new home from a builder. No referral, affiliate, or other fee is paid or received by BuildBuyRefi.com or The Federal Savings Bank in connection with this benefit.
What Letter Four Clients Say About Working With Them
Summaries of public reviews on Google and Facebook. The same themes repeat: careful design, itemized budgets, clear communication when problems turn up, and builds that hold their value.
A late-1940s West LA house was rebuilt almost entirely: new plumbing and electrical, the kitchen moved from front to back, a new roofline, a deck enclosed into a primary bath, and an extended rear. The owners say every cost was itemized and communicated, the build team was precise, and when they sold a few years later the home drew multiple offers over asking in the first week.
Jaime B. · West LA Rebuild · GoogleA Santa Monica Canyon renovation took a dated early-90s house room by room, opening it to light and making it work for kids. When the crew found hidden shortcuts from the original builder, including undersized plumbing and a staircase support issue, the owners say Jeremy explained each problem clearly and solved it within their budget and timeline.
Andrei M. · Santa Monica Canyon · GoogleNew homeowners with no renovation experience hired Letter Four to remodel a mid-century home untouched since the 1950s, including kitchens, baths, and structural work. They say the team handled permits, vendors, subcontractors, and ordering for them, and that they took nearly every one of Lauren's design selections.
Rebecca S. O. · Mid-Century Remodel · GoogleA homeowner who rarely writes reviews says the remodel finally gave the family a space that feels like theirs, as comfortable as it is stylish, and that they plan to hire Letter Four again.
Matt D. · Home Remodel · GoogleOne recent reviewer describes a hardworking team with impressive designs and outstanding build quality, and recommends the firm without reservation.
Local Guide · Google ReviewA client on Facebook says the job was done on time and well, with steady progress updates throughout, and calls the firm a very professional organization.
Andrew R. · Facebook RecommendationMeet Bobby Atkisson, The Banker Assigned To Letter Four Clients
Bobby Atkisson
Top Rated® Sr. Vice President & LPO Manager
BuildBuyRefi.com, powered by The Federal Savings Bank | NMLS ID# 28045
Bobby leads the BuildBuyRefi.com team as Senior Vice President and LPO Manager at The Federal Savings Bank. He brings more than 24 years of mortgage lending experience and a degree in Finance with a Real Estate minor, and he works with borrowers in all 50 states, in person or remotely.
His range fits Letter Four's. The construction and jumbo work covers new custom homes and fire rebuilds. The FHA 203K, FNMA HomeStyle, and VA Renovation designations cover remodels and additions. Veteran Lending covers VA construction with up to 100% financing. And his background in commercial-residential development financing covers the multi-unit side.
What Bobby handles for a Letter Four client: setting the budget ceiling before design, comparing One-Time Close, Two-Time Close, and Hybrid against the specific project, applying lot and land equity, coordinating insurance funds on a rebuild, choosing between Jumbo Renovation and a 2nd lien on a remodel, and keeping draws in step with Letter Four's schedule. Read Bobby's full bio.
Malibu · New Custom HomeCheck Your Eligibility To Build, Rebuild, Or Remodel With Letter Four
A few questions show which programs fit your land, your project, and your loan size. No credit pull, no Social Security number, and no obligation. Your answers go to Bobby Atkisson and to Letter Four.


 California · Three-Story New Home
Schedule A Call With Bobby Atkisson
Pick a time that works. Bring your lot details, insurance settlement status, a rough budget, or Letter Four's preliminary pricing if you have it, and Bobby will walk through which programs fit.
Frequently Asked Questions About Letter Four And Construction Financing In Los Angeles
The questions Los Angeles homeowners ask most before building, rebuilding, or remodeling with Letter Four, answered plainly.
Where does Letter Four build in Los Angeles?
Letter Four serves Greater Los Angeles, including Altadena, Pacific Palisades, Malibu, Brentwood, Santa Monica, Venice, Culver City, the South Bay beach cities, Pasadena, Silver Lake, Los Feliz, Bel Air, Beverly Hills, Hancock Park, Glendale, Burbank, and Downtown Los Angeles. Our financing is available in all 50 states, so buyers relocating to Los Angeles can qualify too.
Can I finance a fire rebuild in Pacific Palisades, Altadena, or Malibu?
Yes. A ground-up fire rebuild can be financed through our One-Time Close, Hybrid, Two-Time Close, Jumbo, second home, and investment construction programs. Your lot equity and any other land equity count together toward the down payment, insurance settlement funds can be applied toward the build in qualifying scenarios, and any remaining mortgage on the lot can be paid off at closing.
How large a construction loan can I get for a custom home in Los Angeles?
Jumbo construction is available up to $4.5 million, case by case, with a 720 minimum credit score. The One-Time Close Jumbo covers primary residences and the Two-Time Close Jumbo covers primary residences and second homes. Loan amounts above $2.5 million go to Credit Committee review, and reserve requirements increase with loan size.
Can I build with zero down if I am not a veteran?
In qualifying scenarios, yes. Up to 100% financing is available to eligible veterans with full entitlement. For other borrowers, land equity is the path to zero down: lot and land you own, or buy at closing, can be applied toward the down payment and can cover it entirely when the equity is sufficient.
Can I finance an ADU or remodel without refinancing my first mortgage?
Yes. Our 2nd Mortgage Construction-to-Permanent loan funds the project during construction and converts to a fixed-rate, closed-end second lien at completion, so your first mortgage keeps its original rate. There is no set maximum; each project is reviewed case by case, including jumbo-size projects, subject to credit and available equity.
How much can I borrow for a major remodel with Letter Four?
Our Jumbo Renovation program finances up to $2.5 million in first lien position, and higher with Loan Committee approval, for primary residences and second homes. For conforming amounts, FHA 203K, FNMA HomeStyle, and VA Renovation programs are also available. A 2nd lien construction loan is the alternative when you want to keep your current first mortgage.
Do you finance multi-unit or commercial projects built by Letter Four?
We finance 1 to 4 unit residential construction, and larger multi-unit residential buildings and subdivisions are reviewed case by case. We do not finance retail, office, restaurant, hospitality, or mixed-use projects, even though Letter Four designs and builds them.
Are concrete, steel frame, and modular homes eligible for a construction loan?
Yes. Concrete, concrete block, steel frame, and modular construction are all eligible property types under our construction programs. Modular homes are treated the same as site-built homes. These are the methods Letter Four uses for fire resistant and non-combustible rebuilds.
Why does it matter that Letter Four is already a registered builder?
Builder approval is a real step. A lender with no relationship has to collect the builder's financials, run its own review, and onboard the builder before your file can move, and many builders are slow to repeat that for a new lender.
Letter Four is already registered with our bank, so that work is done. The only approval left is yours, which improves and speeds up the closing process.
What credit score do I need for a construction loan?
The minimum is 640 on Conventional, FHA, and VA construction programs. Jumbo construction requires 720, ITIN construction requires 680, and investment construction requires 680 to 700 depending on loan-to-value. Bobby Atkisson can review where you stand before you apply.
Contact Letter Four In Los Angeles
Letter Four offers a free introductory call and a longer free call with its principals. Or start with the financing and learn what your project can support first.
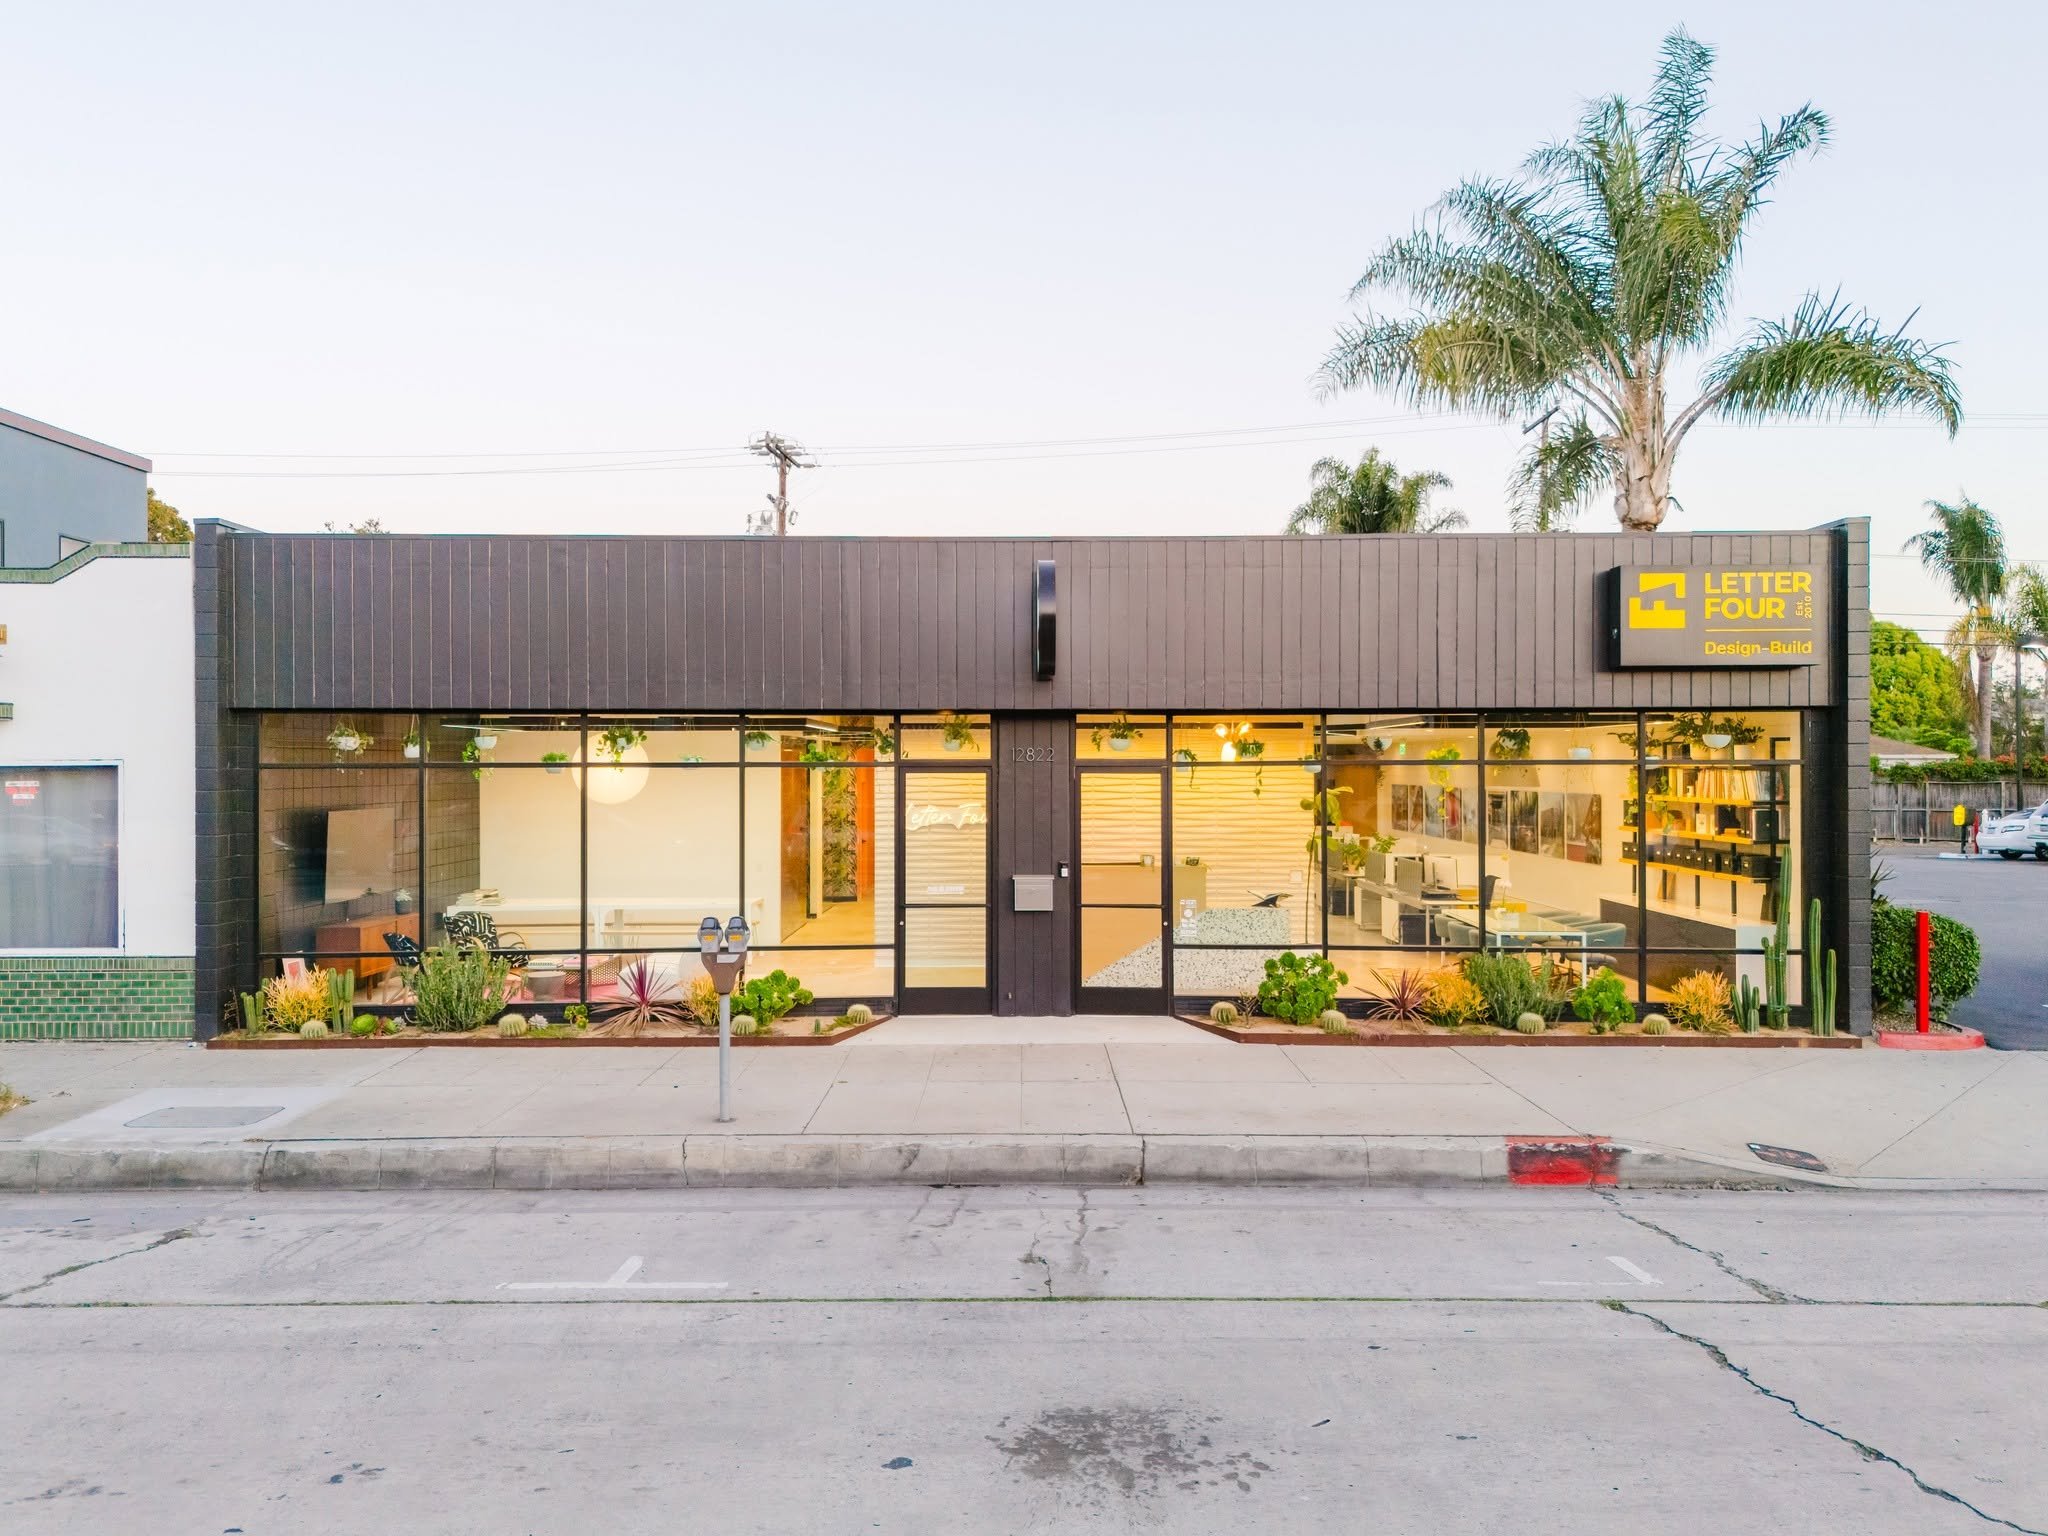
Letter Four, Inc.
Co-owners: Lauren Adams, Architect, and Jeremy Baker, General Contractor
12822 Washington Blvd.
Los Angeles, CA 90066
Phone: (323) 275-1140
Email: hello@letterfour.com
Website: letterfour.com
Licenses: Architecture #C30146, Contractor #B1028949
Bobby Atkisson
Top Rated® Sr. Vice President & LPO Manager
BuildBuyRefi.com, powered by The Federal Savings Bank
NMLS ID# 28045
The Federal Savings Bank, NMLS #411500. FDIC insured, veteran owned, federally chartered, and licensed in all 50 states.
One Team, One Budget
More than fifteen years of Los Angeles design-build, an architect and a contractor who own the firm together, itemized all-in budgets, and a growing body of fire resistant rebuild work.
Letter Four answers the design and building questions. Bobby Atkisson answers the financing questions, and both conversations can happen before a dollar is committed.
Where Letter Four Designs, Builds, And Rebuilds
Letter Four's licensed architects and general contractors work across 34 Greater Los Angeles communities, with its fire rebuild work concentrated in Altadena and Pacific Palisades.
For homeowners searching for a custom home builder in Malibu or Brentwood, a fire rebuild contractor in Pacific Palisades or Altadena, an architect for a remodel in Santa Monica or Pasadena, or ADU builders in the Westside and South Bay, this is the area Letter Four covers.
On the lending side there is no geographic limit. BuildBuyRefi.com is licensed in all 50 states, so financing works anywhere in Letter Four's service area and for buyers relocating from anywhere in the country.
More Registered Builders Serving California
Letter Four is one of nearly 2,000 builders and dealers registered with our bank. Bobby Atkisson can narrow the options quickly once he knows the land, the plan, and how the home will be used.
Financing Resources
As Seen In