Featured Registered Builder · Temple, Texas
Build Your Barndominium With Barn House Co.Up To 100% Financing & *$50K Extra.
Construction loans for turnkey barndominiums built by Barn House Co. on your own acreage or a community homesite, from a direct lender that already has their team approved.
How Do You Finance A Barn House Co. Barndominium?

Barn House Co. is registered with our bank, so a Signature, Elite, Casita, or Custom series barndominium can be financed through BuildBuyRefi.com with a single construction loan covering the land, the build, and the permanent mortgage. Eligible veterans can borrow up to 100%, and other borrowers can reach zero down when land equity covers the down payment.
Getting a builder approved is the step that stalls many construction loans. A builder new to a lender has to hand over company financials, take approval calls, and learn an unfamiliar draw system, and plenty would rather skip it. Barn House Co. has already finished that with our bank, so the only approval left is yours, which improves and speeds up the closing process.
Barn House Co. is a family-owned barndominium builder based in Temple, Texas, with completed homes across Central Texas and in Kentucky. It builds from 15 stock plans or custom designs drawn in-house, pairing steel and timber barn construction with modern interiors.
The company says it prepares detailed plans, specifications, and fixed-price contracts with lenders in mind. Those documents are what our underwriters and the independent appraiser review, and our bank funds and manages every draw in-house.
Barn House Co. clients work directly with Joe Montgomery, Top Rated® Nationwide Mortgage Banker, NMLS ID# 406818, BuildBuyRefi.com, powered by The Federal Savings Bank, the banker Barn House Co. already features on its own financing page.Barndominium Construction Loan Specialist | Veteran Lending Specialist | 20+ Years In Mortgage Lending
Completed Barn House Co. Barndominiums In Texas And Kentucky
A white estate wrapped in covered porches in Seguin, a red barndominium with its own workshop, a cedar-porch homestead in Shelbyville, and a black two-story estate in Russellville with a separate garage and shop.
Select a photo to enlarge it.

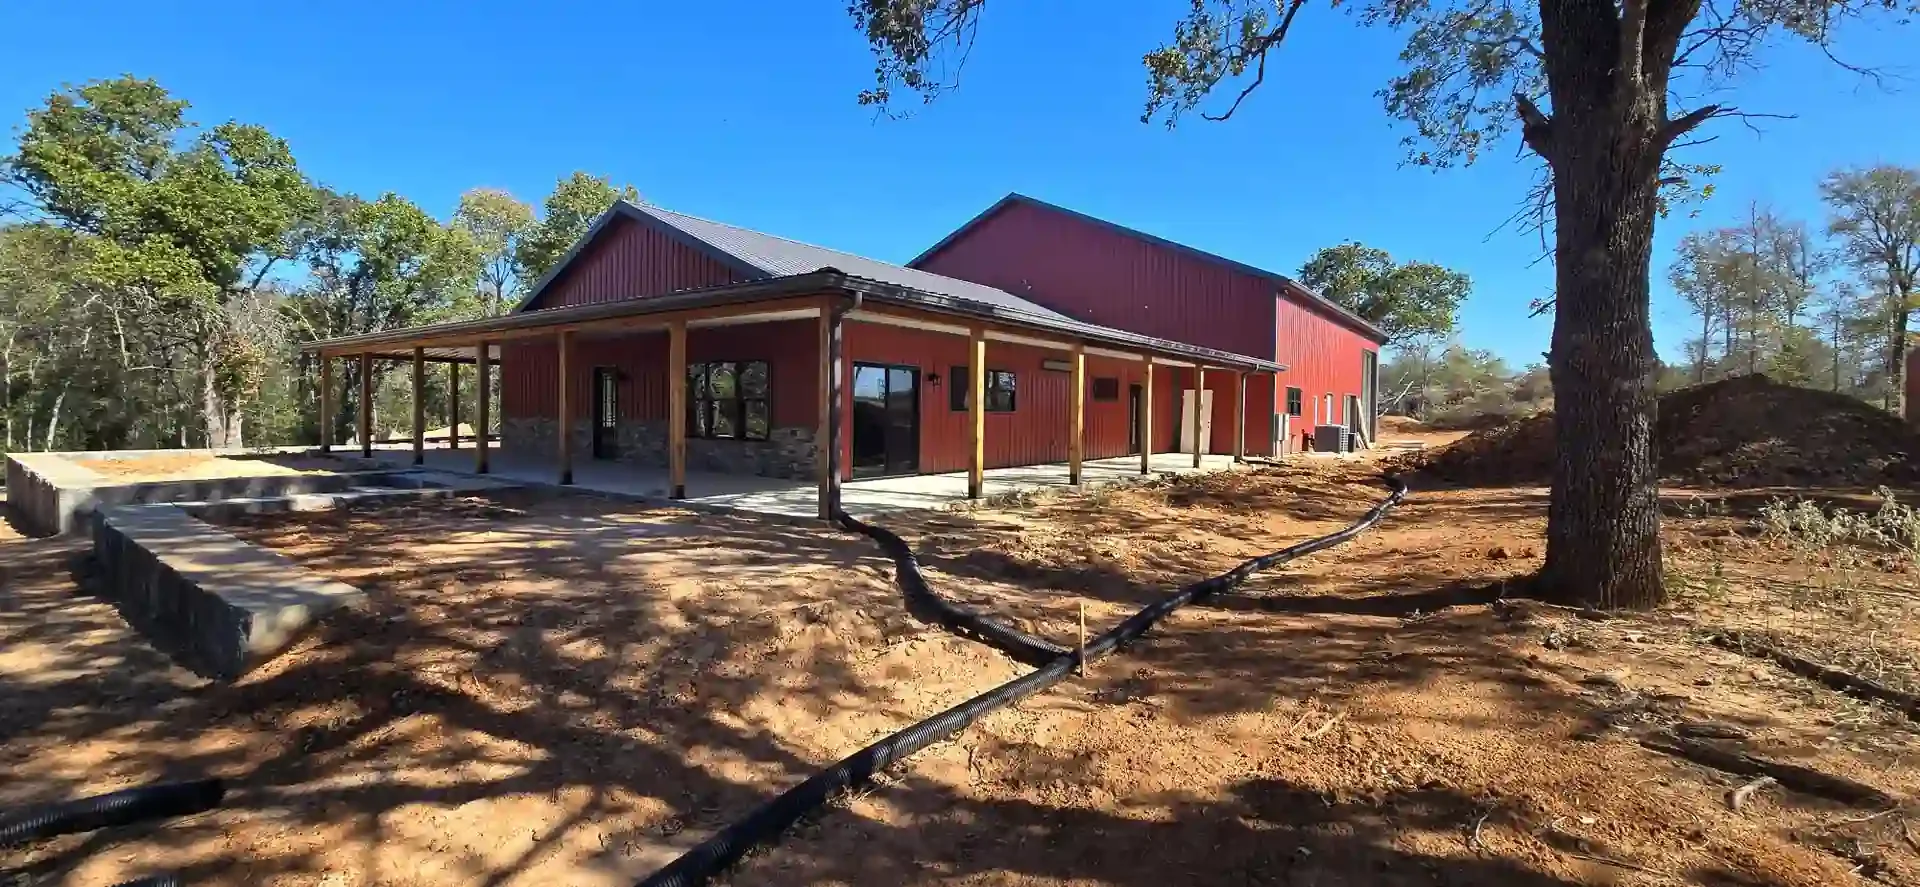
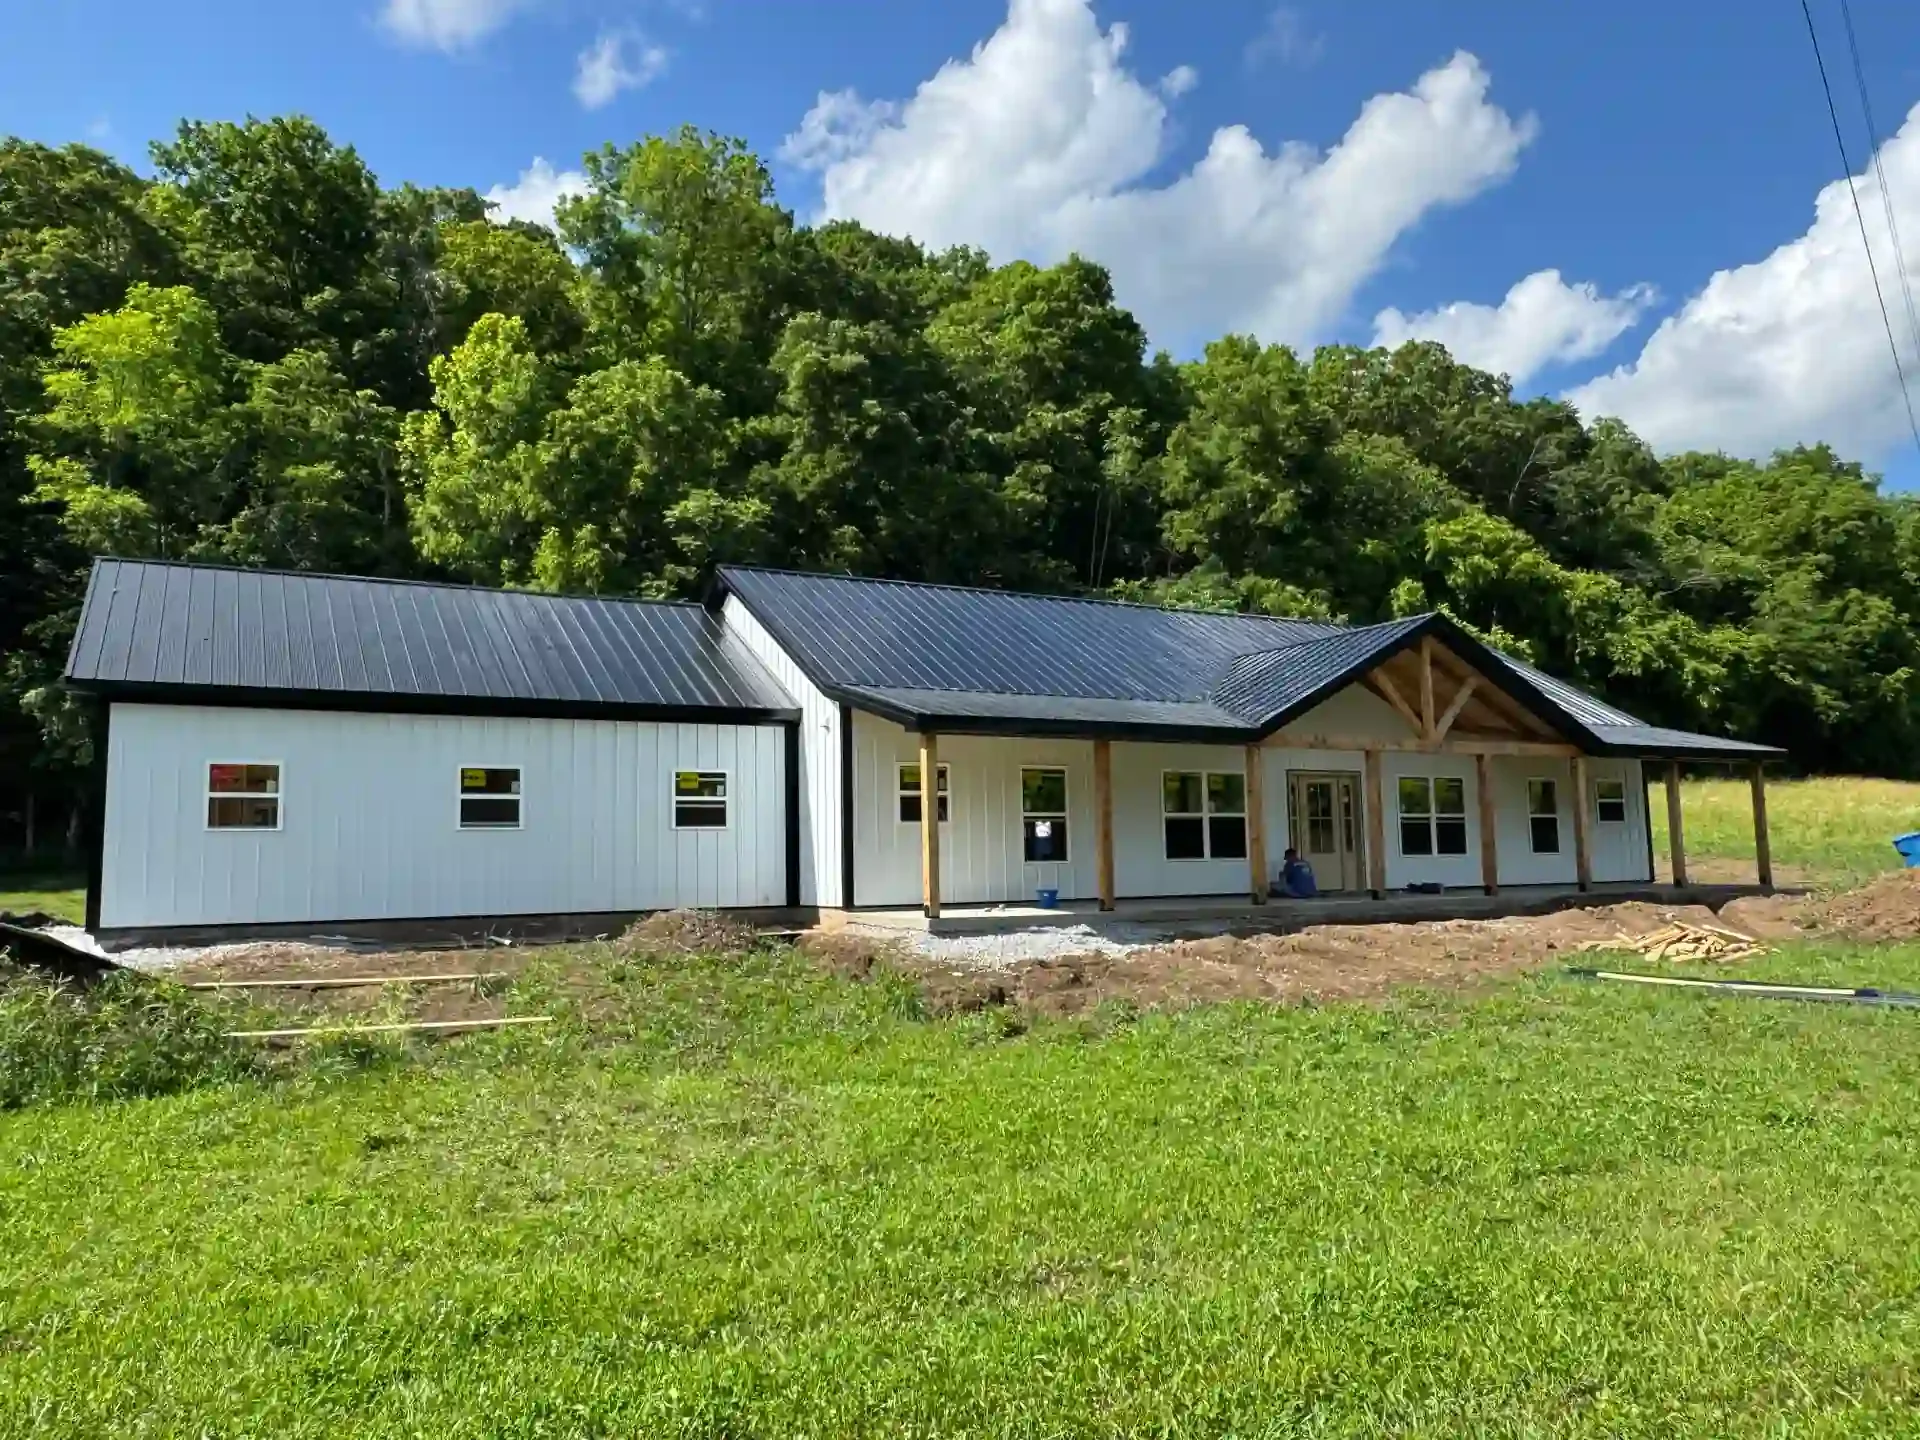

From One Family's Building Business To A Full Barndominium Company
Led by the Chavarria family, Barn House Co. now runs its own design and construction team. It builds across 24 Texas cities and has completed homes in 13 Kentucky communities, from Bowling Green to Louisville. New Kentucky projects are taken on case by case.
Its standard specifications include engineered trusses, spray foam insulation, metal roofing and siding, and 4-inch monolithic slabs. Barn House Co. states that it is a fully licensed and insured general contractor that builds to the lender's draw schedule.
Buyers can pick a stock plan, modify one, or start from a blank page with the in-house designer, and the team keeps clients updated from permitting through the final walkthrough.
Watch A Barn House Co. Home Come Together
A finished-home walkthrough from the Barn House Co. YouTube channel.
The Team Behind The Builds

Jonny Chavarria
CEO & FounderFounder with three decades in construction and more than twenty years as a business owner. He grew up in Costa Rica as a missionary kid and speaks Spanish fluently.

Jaseon Chavarria
COORuns operations and the build schedule. Two decades in construction, fifteen-plus years managing large projects in the U.S. and overseas, and fluent in Spanish.
Sherri Chavarria
AccountingHandles the company's books, with six-plus years in bookkeeping and accounting. Her family has worked in construction for three generations.

JP Pietras
Sales Manager & MarketingLeads sales and marketing. A U.S. Army combat veteran and former business owner, he also brings a background in government contracting.

Jarratt Walker
Sales RepA U.S. Navy veteran with thirty years in sales and two decades designing kitchens, who helps buyers choose and adjust a floor plan.

Brian F. Hendrickson
In-House DesignerDraws the homes in-house after more than fifty years in construction trades, from cabinetry to roofing. He studied engineering and holds two master's degrees.
Building A Barn House Co. Barndominium, With The Construction Loan Built In
Barn House Co. works in four stages: consultation, design, build, and move-in. Here is where each financing step lands.
- Financing
Set Your Budget With Joe Montgomery
Joe reviews your credit, income, and land, then matches you with the loan structure and program that fit, so you know your number before you pick a plan.
- Barn House Co. Consultation
Share Your Plans, Land, And Timeline
Barn House Co. learns how you live and what you want to spend. No land yet? They build in two gated acreage communities and can point you there.
- Design
Choose A Plan Or Draw A New One
Pick from four series or bring your own plan for the in-house designer to refine. The final plans, specs, and turnkey contract go to underwriting and the appraiser.
- Closing
Close Once On Land And Loan
A lot purchase can close with the construction loan, and land you already own counts toward the down payment.
- Build
Draws Tied To Finished Work
Before any draw is released, a third-party inspector confirms the stage is complete. Our bank pays each draw directly, in-house.
- Move In
Keys, Then Your Permanent Loan
After the walkthrough, a One-Time Close converts on its own. A Hybrid or Two-Time Close wraps up with the second closing.
Custom Barndominium Plans In Four Series
Barn House Co. groups its floor plans into four series, and each one points to a likely loan.
Streamlined Starter Homes
Five plans from about 1,024 to 1,680 square feet with stained concrete floors, granite counters, and cedar-finished porches.
How It Can Be FinancedConventional, FHA, or VA construction from a 640 scoreLarger Homes, Upgraded Finishes
Nine plans from about 1,742 to 2,625 square feet, many with large attached garages, plus LVP floors and tiled primary showers.
How It Can Be FinancedConventional, FHA, VA, or the Hybrid Construction LoanGuest Houses And In-Law Suites
Four smaller plans from 460 to 1,500 square feet, meant to sit beside a main house as an in-law suite, guest quarters, or a rental.
How It Can Be Financed2nd Mortgage Construction on a property you ownFully Custom Barndominiums
Open selections on everything, from hardwood and quartz to custom cabinetry, freestanding tubs, wraparound porches, and rooflines.
How It Can Be FinancedConventional, VA, or Jumbo construction up to $4.5MFinancing requires turnkey. Barn House Co. also sells shell builds, but our construction loans only cover homes built through to completion under the contract. The eligibility section below explains why.
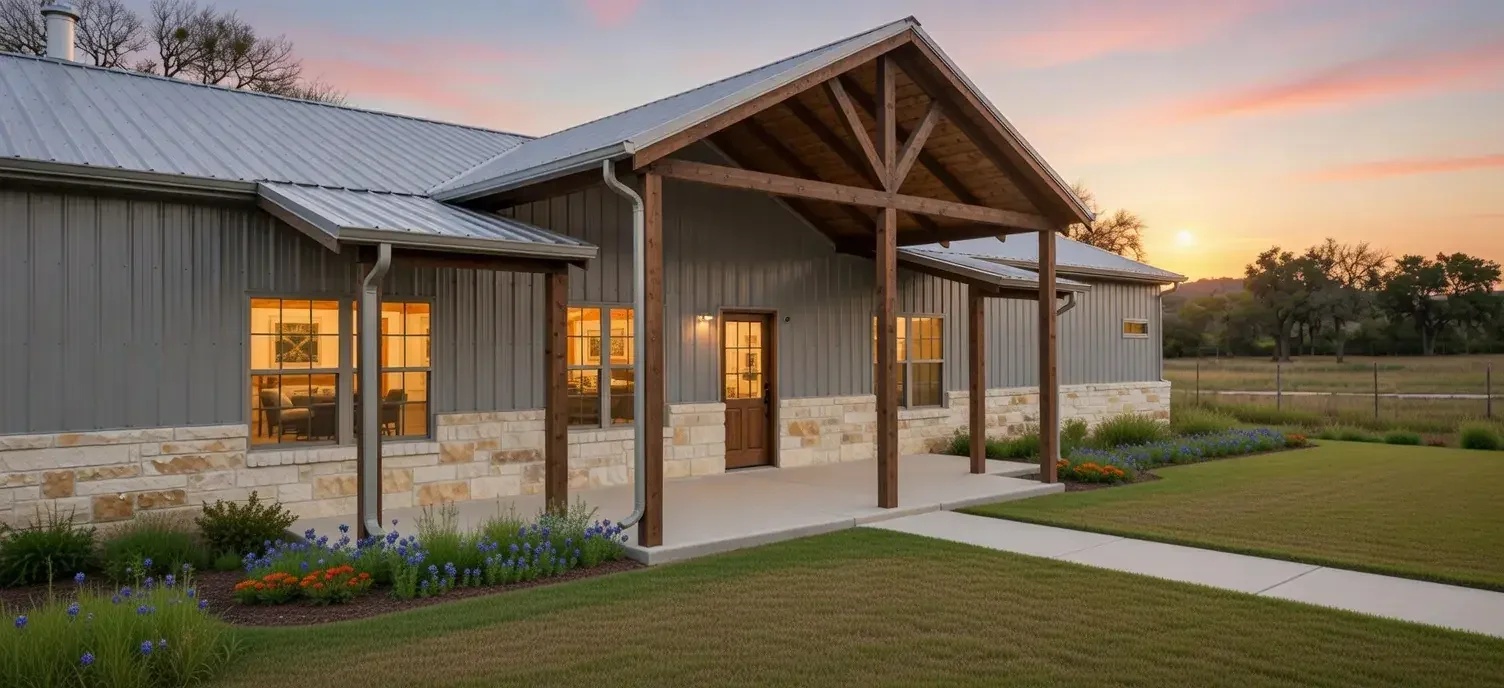
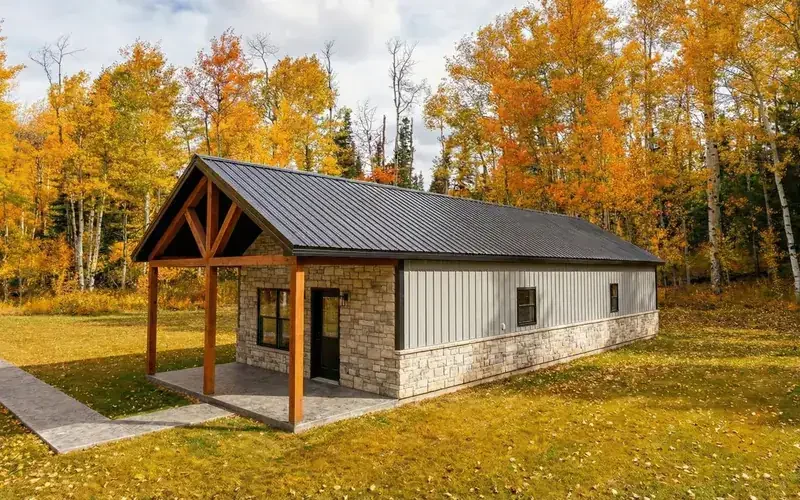
Signature, Elite, And Casita Designs From The Barn House Co. Plan Library
The gabled white Trenton with its stone base, the Columbia with a wraparound porch, the stone-front Brazos cottage, and a grey barndominium with a half stone front.
Any plan can be modified and any finish level upgraded.


Barndominium Construction Loans For Barn House Co. Homes
BuildBuyRefi.com is a division of The Federal Savings Bank (NMLS #411500), a veteran-owned, FDIC-insured direct lender licensed nationwide. Plenty of lenders still pass on barndominiums. We treat them as permanent residential construction when they sit on land you own or buy at closing, on a permanent foundation, with the right zoning and permits.
Three Ways To Structure The Loan
One Approval, One Closing
Qualify and close once. When the home is done, the loan becomes your permanent mortgage with no re-qualification and no second appraisal, on terms set at that first closing.
Set The Permanent Rate Later
Separate closings for construction and the permanent loan, so you choose the permanent rate at completion. FHA and VA permanent loans can be streamlined in qualifying scenarios.
Single-Close Feel, Rate Still Open
Our own design. Both loan packages are drawn up at the start, so it feels like a single closing with a single set of fees, yet you lock the permanent rate when the home is done. In qualifying scenarios the permanent loan can use an FHA or VA streamline. Only a direct lender can offer it.
Program Details At A Glance
- Minimum score, Conventional, FHA, VA
- 640
- VA financing, eligible veterans
- Up to 100%
- VA construction loan size
- $1.5M, up to $3M by exception
- Jumbo construction
- Up to $4.5M
- Minimum score, Jumbo
- 720
- Minimum score, ITIN
- 680
- Investment construction
- 1 to 4 units
- Minimum score, investment
- 680 to 700
- Administrative fees
- None
Jumbo amounts above $2.5M go to Credit Committee review. Credit, occupancy, and property type determine final eligibility.
Zero Down On Your Acreage
Veterans with full entitlement can borrow up to 100% on a VA Hybrid or Two-Time Close, with no mortgage insurance. For everyone else, land equity is the route to zero down: acreage you own or buy at closing counts toward the down payment and can cover all of it when the equity is there.
Comparables Drive The Appraisal
An independent appraiser values the home from the plans, the specs, and nearby comparable sales. Comparables matter most on barndominiums with oversized garages, so Joe checks the local market early. More in our barndominium construction loan guide.
No Fee Layers Hiding In The Loan
We charge no administrative fees on our construction programs. Broker and correspondent construction loans can stack $40,000 to $100,000 or more in added fees, enough to push the loan above what the finished home appraises for.
Every program is subject to credit qualification, property eligibility, reserves, and program guidelines. Rates, terms, and availability depend on the borrower, property, occupancy, and loan amount and are not guaranteed. Independent licensed appraisers complete appraisals, and third-party inspectors complete construction inspections. Ask your banker for current rates, terms, and conditions.
*$50,000
Extra Funds For The Parts Of Country Living A Build Contract Skips
Qualified borrowers can add up to $50,000 in separate, unsecured funds, available before, at, or after closing and underwritten by our team together with your home loan. It stays outside the construction loan and has no effect on your loan-to-value.
How Barn House Co. Clients Could Use It
A pole barn, carport, or storage building
For a structure that does not qualify for a mortgage after case-by-case review, paired with your primary BuildBuyRefi home loan.
Fencing, gates, and a driveway
Acreage needs perimeter fencing, an entry gate, and a road to the house, items that often sit outside the home contract.
Finish upgrades chosen late
Moving up to tile, better flooring, or premium cabinets after the build contract is already signed.
Furniture and appliances
An open barndominium layout means a big great room, a long porch, and new rooms to fill once you get the keys.
Moving and living costs
Rent, storage, and moving expenses while your home goes up on the land you just bought.
Clearing balances to qualify
Paying off credit card or auto balances can lower your debt-to-income ratio and, in some scenarios, make the loan size you need possible.
*Up to $50,000 is available to qualified borrowers and can be applied across our loan programs. This is a separate unsecured consumer loan underwritten in-house at the same time as the mortgage. Proceeds cannot be used for a down payment. Approval, amount, rates, and terms depend on credit qualification and are not guaranteed. Contact your banker for applicable rates, terms, and conditions.
Build On Your Own Land Or A Homesite In A Barn House Co. Community
Barn House Co. builds on land you already own and in two gated acreage communities in Central Texas. Either way, the land and the home can share one construction loan.
Highland Branch
Platinum Land's gated development offers estate lots with paved roads, utilities run to each homesite, and fast internet. Phase 2, The Estates, is listed as available, buyers pick their own builder, and there is no build deadline.
Iron Oak Reserve
National Land Partners developed this gated acreage community roughly 25 minutes outside College Station, with city water, electricity, fiber internet, and paved streets.
Build On Land You Own
Already own acreage in an area Barn House Co. serves? The equity in it can go toward the down payment on your new home.
How Land Works In Your Construction Loan
Lot And Loan In One Closing
Buy the lot in the same closing as the construction loan, with no separate land loan. If you owe on land you already own, that balance can be paid off at closing.
Title Must Be In Your Name
The land has to be titled to you, now or at closing. Family land needs a formal title transfer, and a survey to split it off where needed.
Room For Larger Tracts
VA construction is more flexible on large tracts than many programs, and Jumbo construction covers up to 30 acres, with exceptions reviewed by our construction leadership.
Community details, lot sizes, and amenities come from Barn House Co. and the developers and may change. Land eligibility depends on title, appraisal, zoning, access, and utilities. All financing is subject to credit qualification and program guidelines.
Elite Series Floor Plans, From The Cheyenne To The Austin Loft
Six Elite Series layouts: the Cheyenne at about 2,400 square feet with a 30x40 garage, the lofted two-story Austin, the four-bedroom Topeka, the Lincoln, the Lansing, and the five-bedroom Frankfort.
Every plan is shown uncropped. Select one to read the details.

The Cheyenne · Exterior And Floor Plan
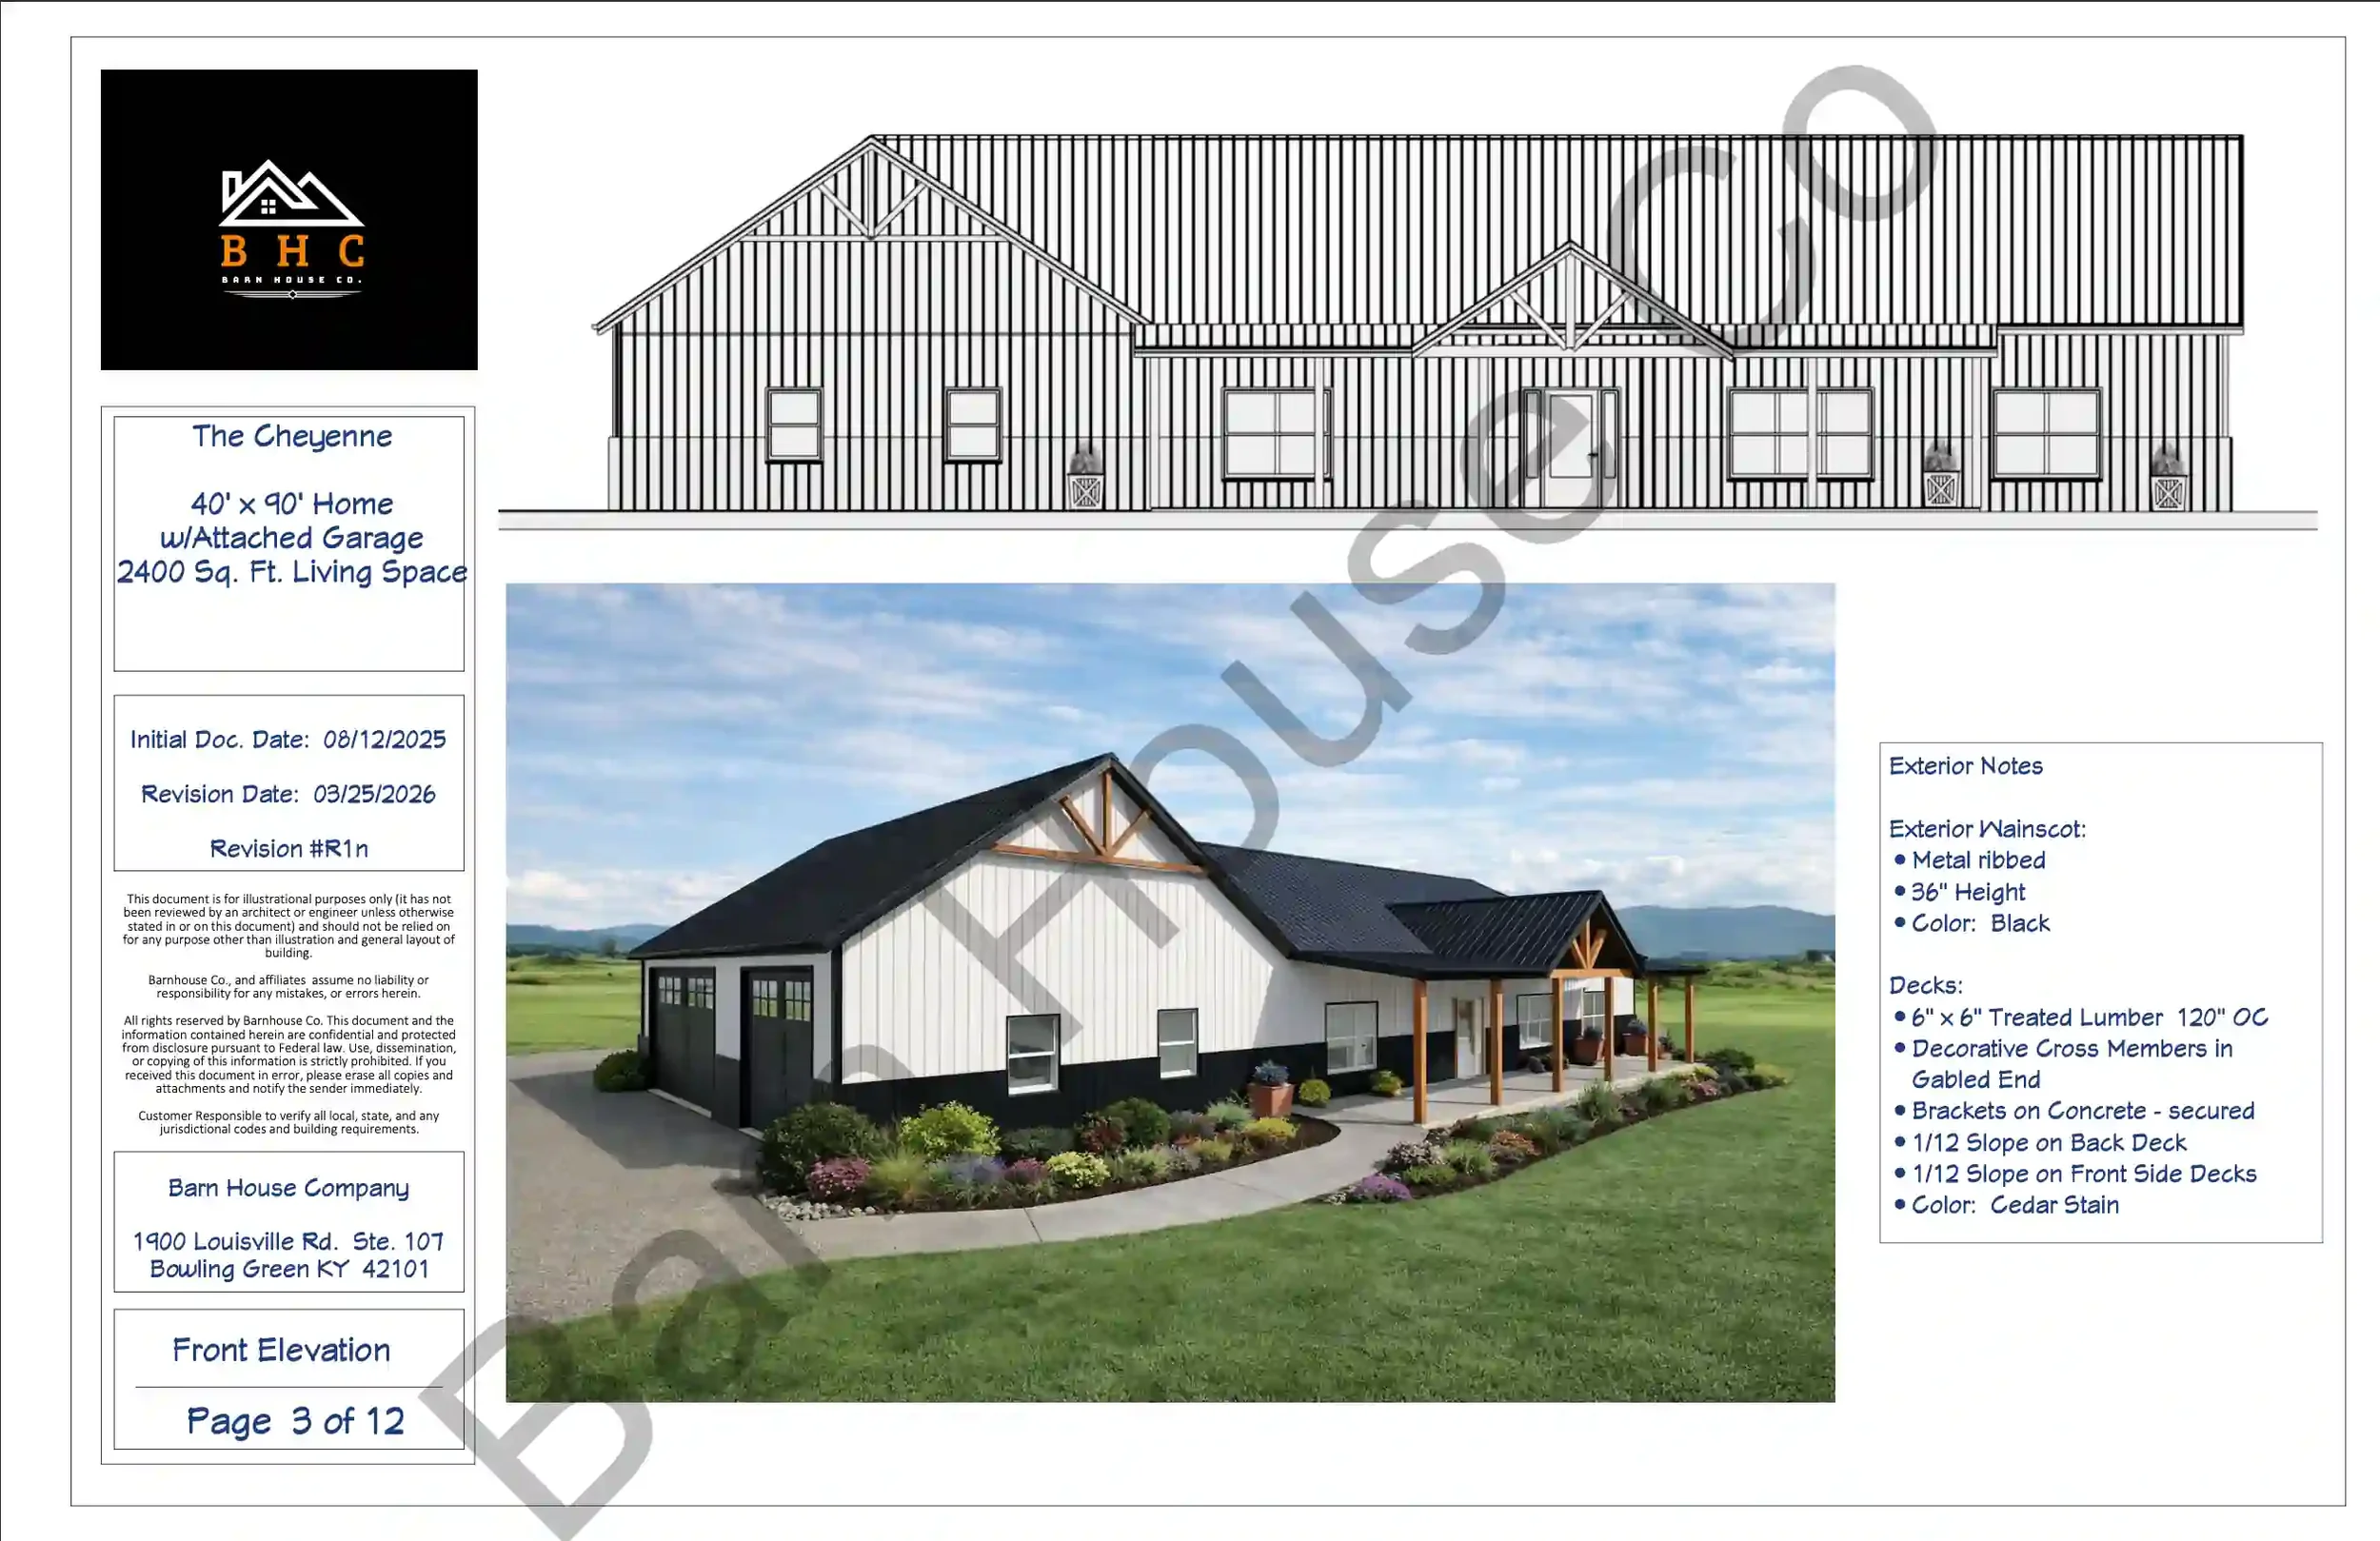
The Cheyenne · Exterior Elevation

The Cheyenne · Interior
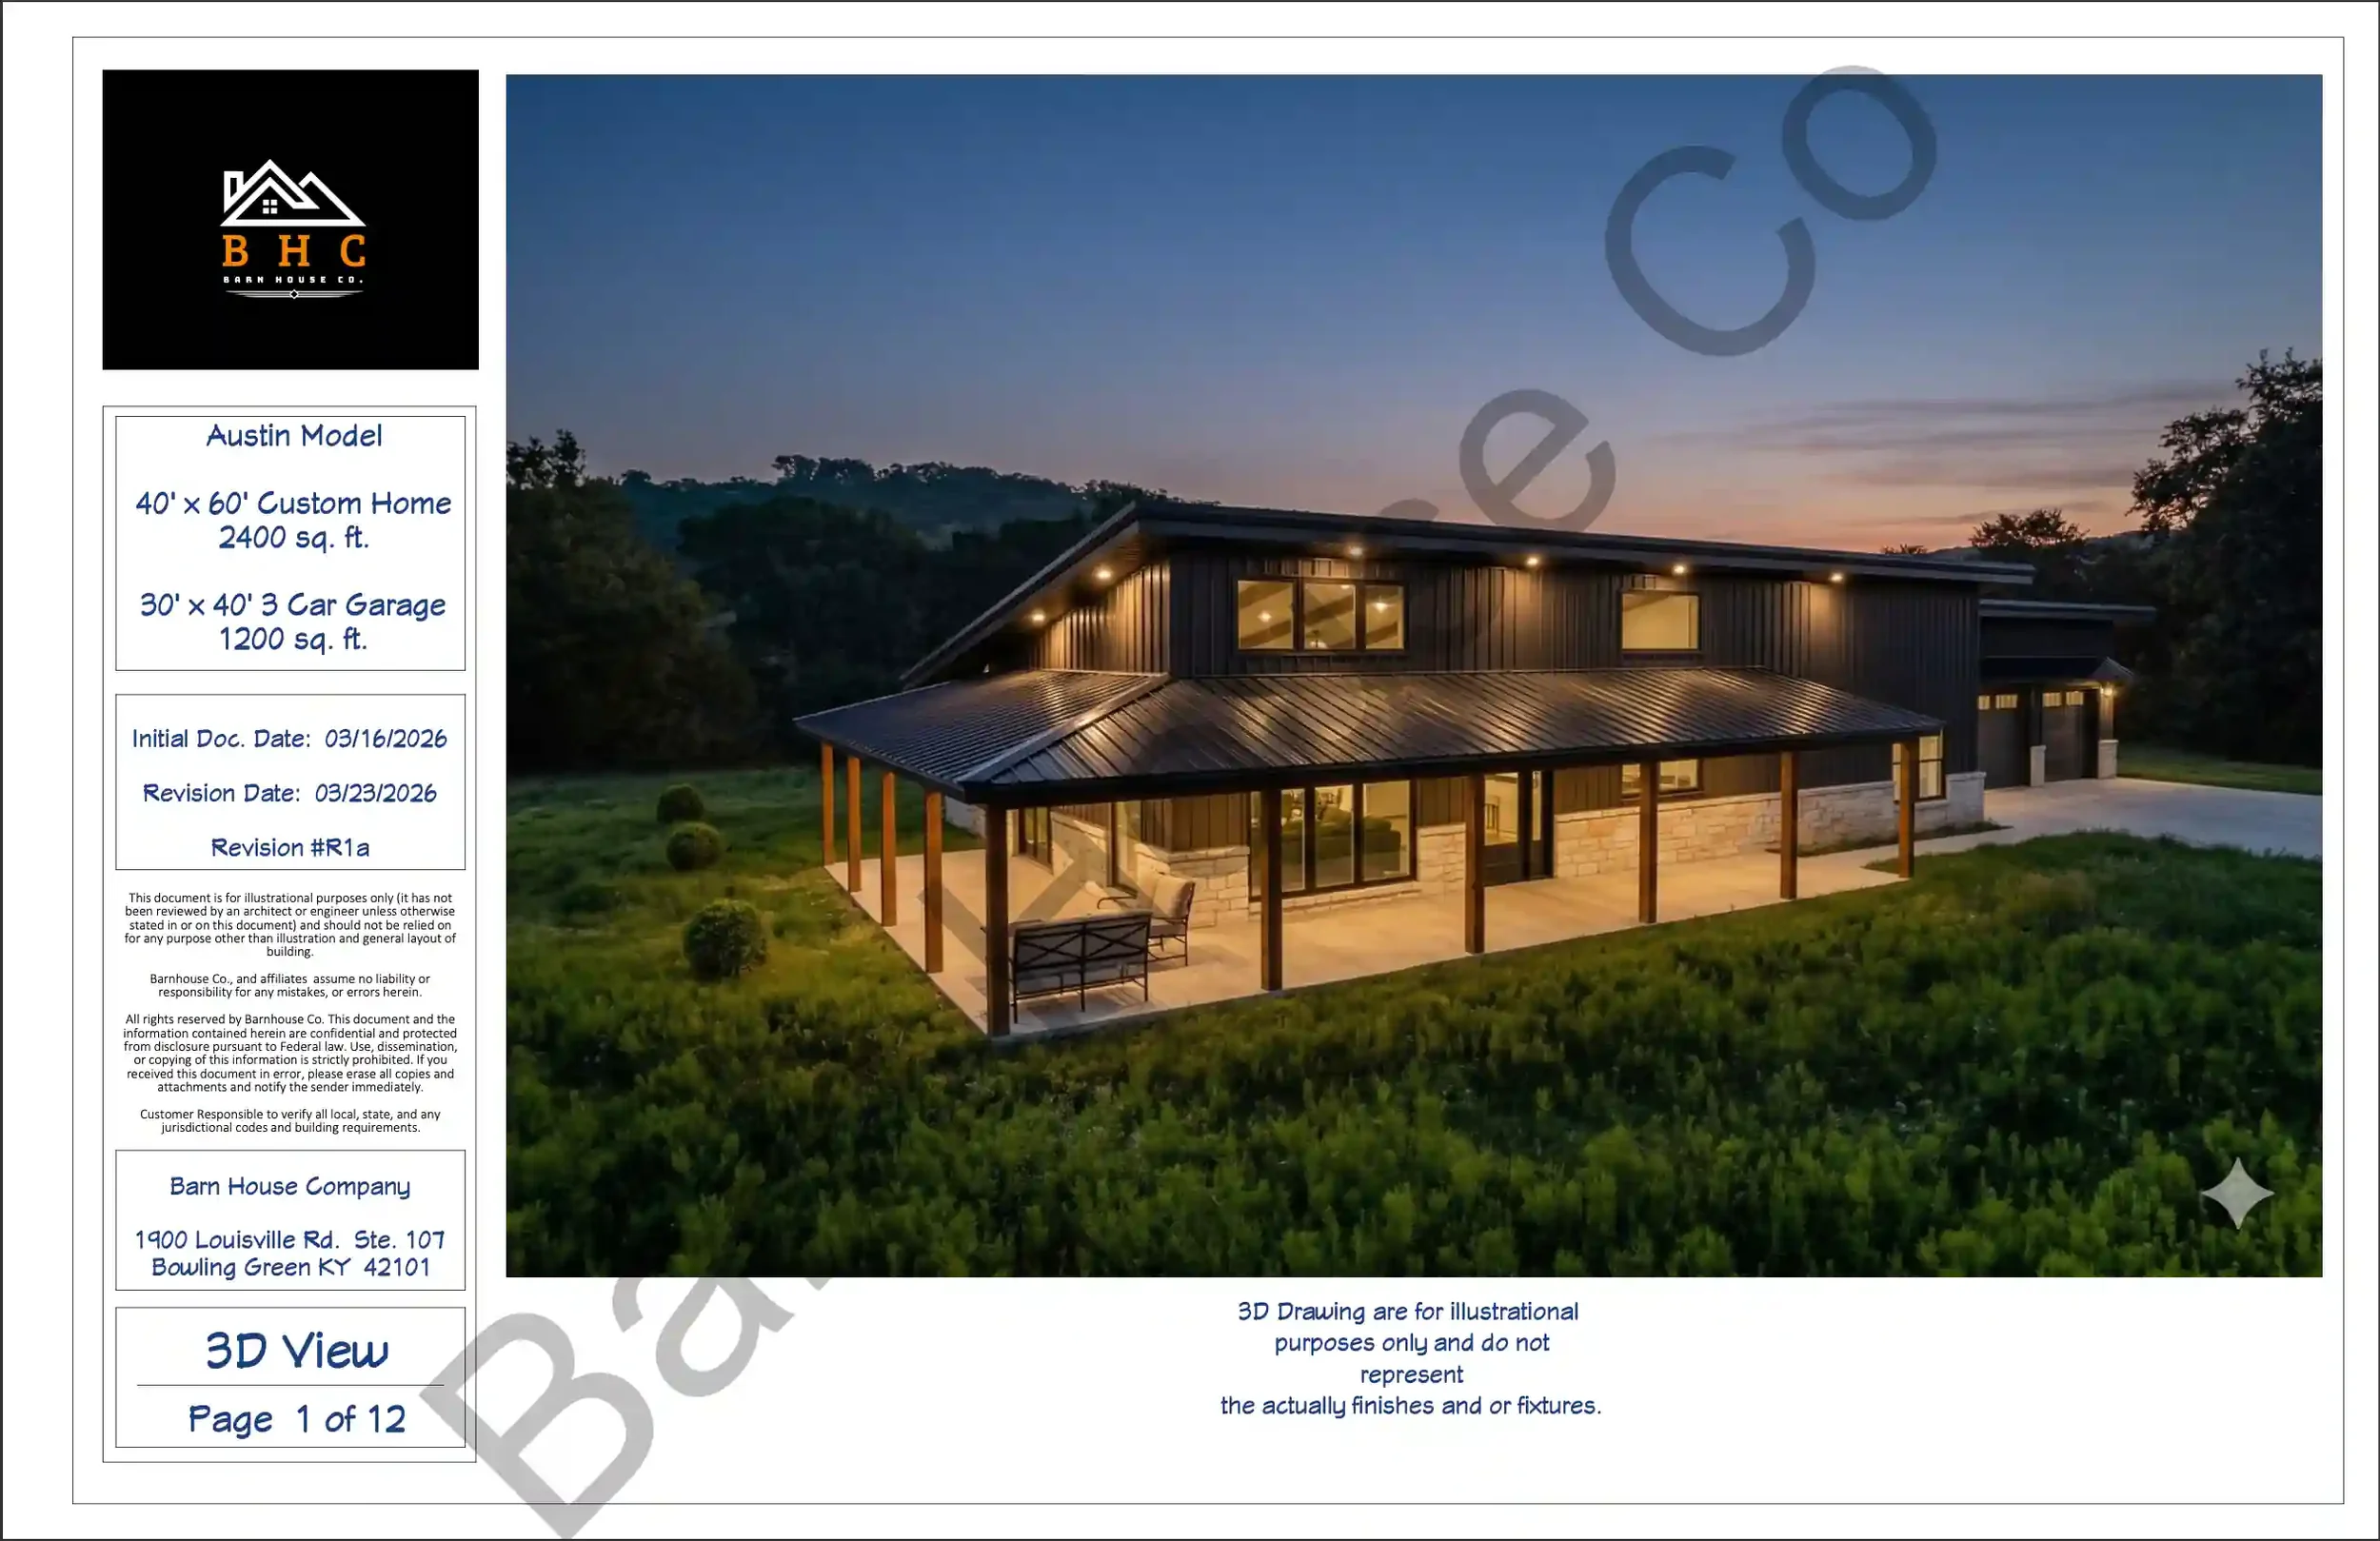
The Austin · Lofted Two-Story Exterior

The Austin · Lofted Interior

The Topeka · Exterior And Floor Plan

The Lincoln · Exterior And Floor Plan
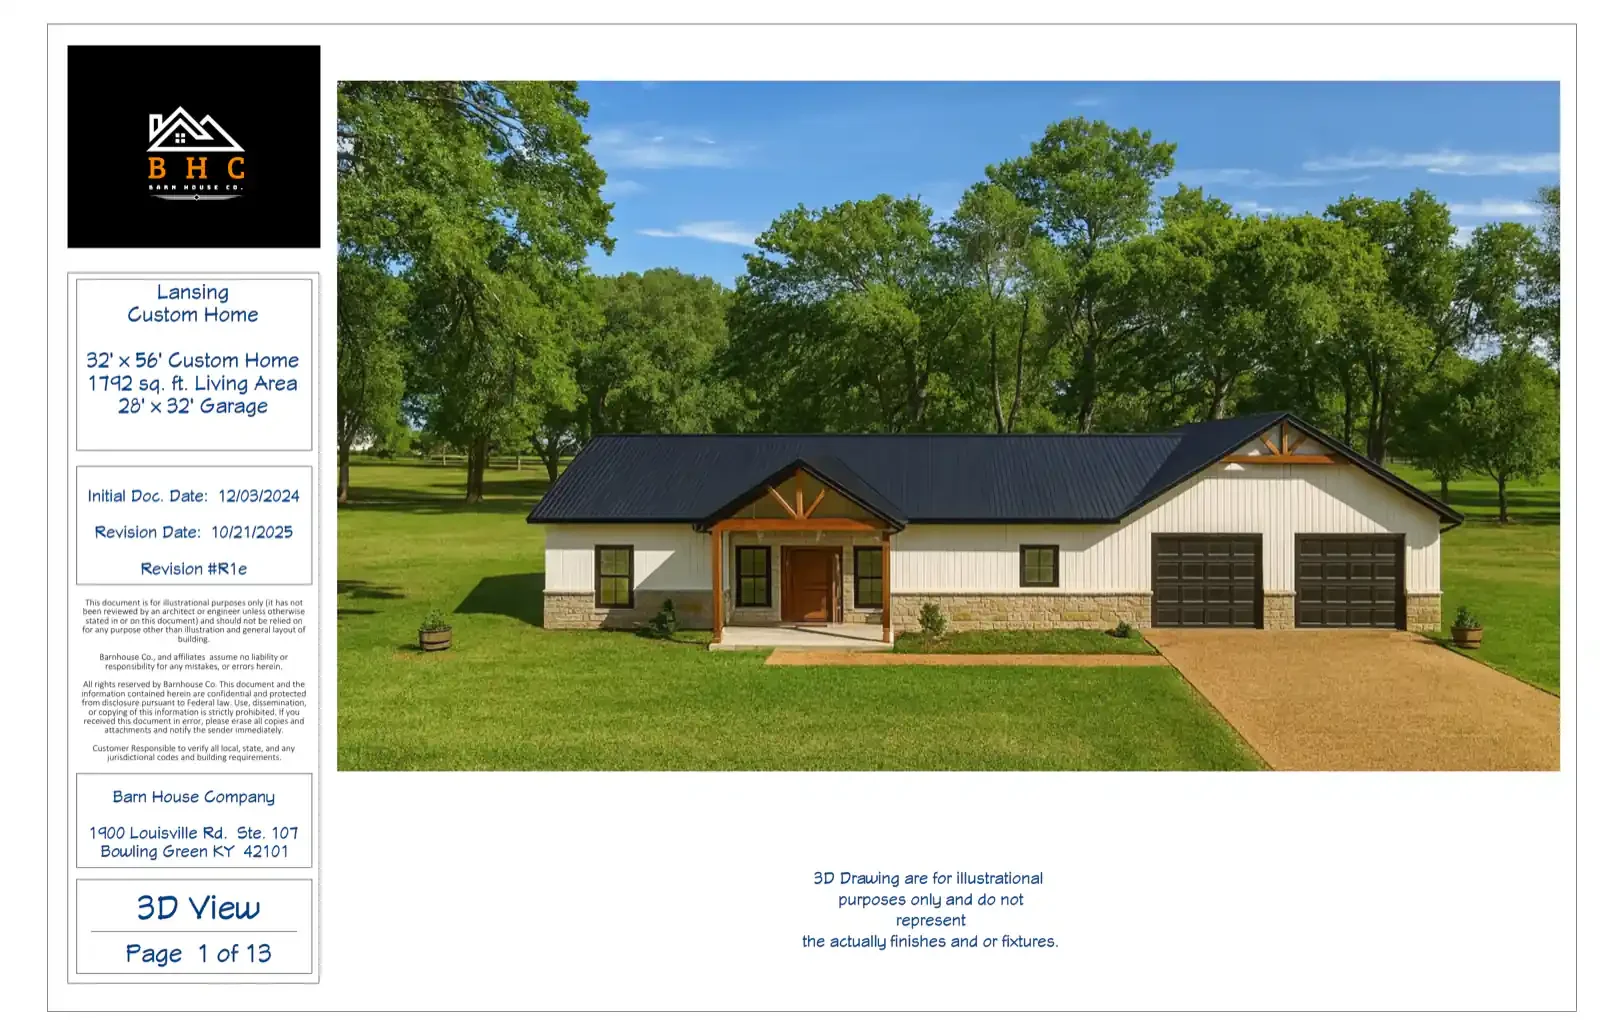
The Lansing · Exterior And Floor Plan

The Frankfort · Exterior And Floor Plan
What We Can And Cannot Finance With Barn House Co.
Barn House Co. builds homes, casitas, garages, workshops, and event spaces. We finance the homes and the residential structures that go with them.
What We Can Finance
- Turnkey barndominiums from any series to live in, use as a second home, or rent out, on land you own or buy at closing
- Barndominiums with oversized attached garages, when local comparable sales support the value and no full-time business operates from the space
- Custom builds up to $4.5 million in Jumbo construction, case by case
- Owner-occupied duplexes and 1 to 4 unit investment construction
- Casitas of 400 square feet or more, as a primary home or on a 2nd lien next to your current home
- Pools written into the build contract when the appraisal supports them
What We Cannot Finance
- Shell-only contracts finished by you or by trades you hire, which counts as owner-building
- Working shop homes built to run a full-time business out of the building
- Event venues, wedding barns, and other commercial projects
- Structures under 400 square feet, such as she sheds, unless approved case by case
- Land titled to someone else that is not transferring to you
- Work left out of the build contract, which cannot be added after closing
Reviewed case by case. Separate garages, combo workshops, barns, and other out-of-the-ordinary structures on the land are not ruled out. Joe Montgomery and our Loan Committee review each one on its plans and comparable sales. If a structure does not qualify, the *$50,000 Consumer Loan can cover it when paired with your primary loan.
Why only turnkey. A construction loan is underwritten on the finished home and paid out as an approved builder completes each stage. If the owner takes over after the shell, no approved builder is left to finish the house the loan is based on.
Appraisals come from independent appraisers, and we cannot influence the value. Put everything you want financed, from porches to garages, in the contract before closing.
Add A Casita, Workshop, Or Garage Without Refinancing Your First Mortgage
The Casita Series is built for land that already has a house on it. Many owners locked a first mortgage rate between 2.5 and 4.0 percent in 2020 and 2021, and a cash-out refinance to pay for a new structure would give up that rate on the whole balance, often costing more over time than the project.
2nd Mortgage Construction-To-Permanent
The project is paid out in inspected draws, then becomes a fixed-rate, closed-end second lien once it is finished. Your first mortgage, its balance, and its rate stay exactly where they are.
No set maximum applies. Joe reviews each project individually against the plans, your equity, and your credit, large ones included.
Built For Owners Keeping Their Rate
A HELOC often caps out early and floats. A cash-out refinance resets the entire mortgage. This loan covers only the new structure, at a fixed rate, with the same in-house draw management as a ground-up build.
The 640 minimum score still applies, and so does the builder rule: Barn House Co. builds it, not the homeowner.
Barn House Co. Projects This Loan Fits
In-Law Casita
A Guadalupe or Bosque plan beside the main house, so parents live close with their own front door.
Guest Quarters
A Brazos or Pecos casita for visiting family, ranch hands, or a quiet retreat on the back acres.
Detached Garage
A separate garage for trucks, trailers, and equipment, finished to match the house and reviewed case by case.
Combo Workshop
A garage and hobby shop under one roof for personal use, reviewed case by case by Joe and Loan Committee.
Long-Term Rental Casita
A compact unit that adds rental income to land you already own and live on.
A Second Home On Your Acreage
A full second barndominium for family on land you own, without touching the first home's mortgage.
For backyard units, see our ADU financing guide.
Subject to credit qualification, available equity, lien position, appraisal, property eligibility, and program guidelines. Rates and terms depend on the borrower and property and are not guaranteed. Local zoning and permits control what can be built. Contact Joe for current rates, terms, and conditions.
Selling A Home Or Buying Land First? Save Up To 30% On Commissions
A move to acreage often starts with selling your current house, and sometimes with buying land through an agent. Qualified borrowers can save up to 30% on real estate commissions on those deals through our participating agent network, as a closing cost credit or a rate buy-down. See how commission savings work.
Selling Your Current Home
Trading a house in town for land in the country? The savings apply to selling the home you own now.
Buying Agent-Listed Acreage
If the land you want is listed with an agent, the network can represent your purchase and the savings apply.
Credit Or Lower Rate
Use the savings for closing costs or a rate buy-down. Joe can price both and show which saves more.
Where it applies and where it does not. Only agent-represented deals qualify: the sale of a home you own, the purchase of an existing listed home, or land bought through a listing agent. It does not apply to a home built by Barn House Co., since you sign that contract directly with the builder and no agent is paid. A community lot bought straight from a developer with no agent involved does not qualify either.
We do not pay the agents and they do not pay us. Nobody earns a referral fee when you use the network, because paying or accepting fees for referring federally related mortgage loans is against the law.
Commission savings are offered to qualified borrowers through a participating agent network, subject to agent availability, program terms, and state law. Savings come from the fee earned by the participating brokerage representing the borrower and are applied to closing costs or a rate buy-down. Results vary by property, price, and agreement. The benefit does not apply to buying or building a new home directly from a builder. BuildBuyRefi.com and The Federal Savings Bank pay and receive no referral, affiliate, or other fee for this benefit.
Barn House Co. Reviews From Facebook And Google
Paraphrased from public reviews. The same themes repeat: crews that show up on time, quick answers, and quality that holds up.
A homeowner says the team stayed with them from start to finish, answered the phone every time, and stayed patient even when the same question came up twice. They report no missed appointments, no delays, and finished work they rate as top quality.
Christopher F. · Home Build · FacebookAfter Barn House Co. completed the shell and framing of her home, this client said the crew arrived every time they promised. She found Jonny and Jaseon easy to talk to and quick to respond, and recommends them highly.
Alicia T. K. · Shell And Framing · FacebookAfter collecting quotes from several local companies, this customer chose Barn House Co. for a garage and pole barn. He says he got exactly what he asked for at a fair price, and that the quality, communication, and value beat his expectations.
Shane J. · Garage And Pole Barn · FacebookA couple who had a home shell built describes the framing crew as professional and polite, and says they were kept up to date at every step of the process. They recommend the builders without hesitation.
Ida C. · Home Shell · GoogleA recent homeowner calls the experience excellent and the finished home beautiful. Questions and problems were handled quickly, the crew paid close attention to what the family wanted, and even his detail-focused wife was happy with the result.
Donald L. · New Home · GoogleMeet Joe Montgomery, The Banker Assigned To Barn House Co. Clients
Joe Montgomery
Top Rated® Nationwide Mortgage Banker
BuildBuyRefi.com, powered by The Federal Savings Bank | NMLS ID# 406818
Joe has spent more than two decades in mortgage lending, much of it working side by side with builders. He handles construction, renovation, factory-built, and barndominium financing for clients nationwide, along with standard purchase loans.
Barndominium loans hinge on details like the framing method, the finish level, and the comparable sales an appraiser can use, and Joe works those out with clients before they sign a contract. VA lending is a personal priority for him, and he also works across FHA, Jumbo, and Conventional programs.
For a Barn House Co. build, Joe can set a budget ceiling before you choose a plan, match One-Time Close, Hybrid, or Two-Time Close to your timeline, apply your land equity, time a lot purchase in Highland Branch or Iron Oak Reserve, and set up a Casita or garage on a 2nd lien. Read Joe's full bio.
 Texas · Custom Barndominium
Check Your Eligibility To Build With Barn House Co.
Answer a handful of questions to see which programs match your land, plan, and budget. There is no credit pull, no Social Security number, and no commitment. Joe Montgomery and Barn House Co. both receive your answers.


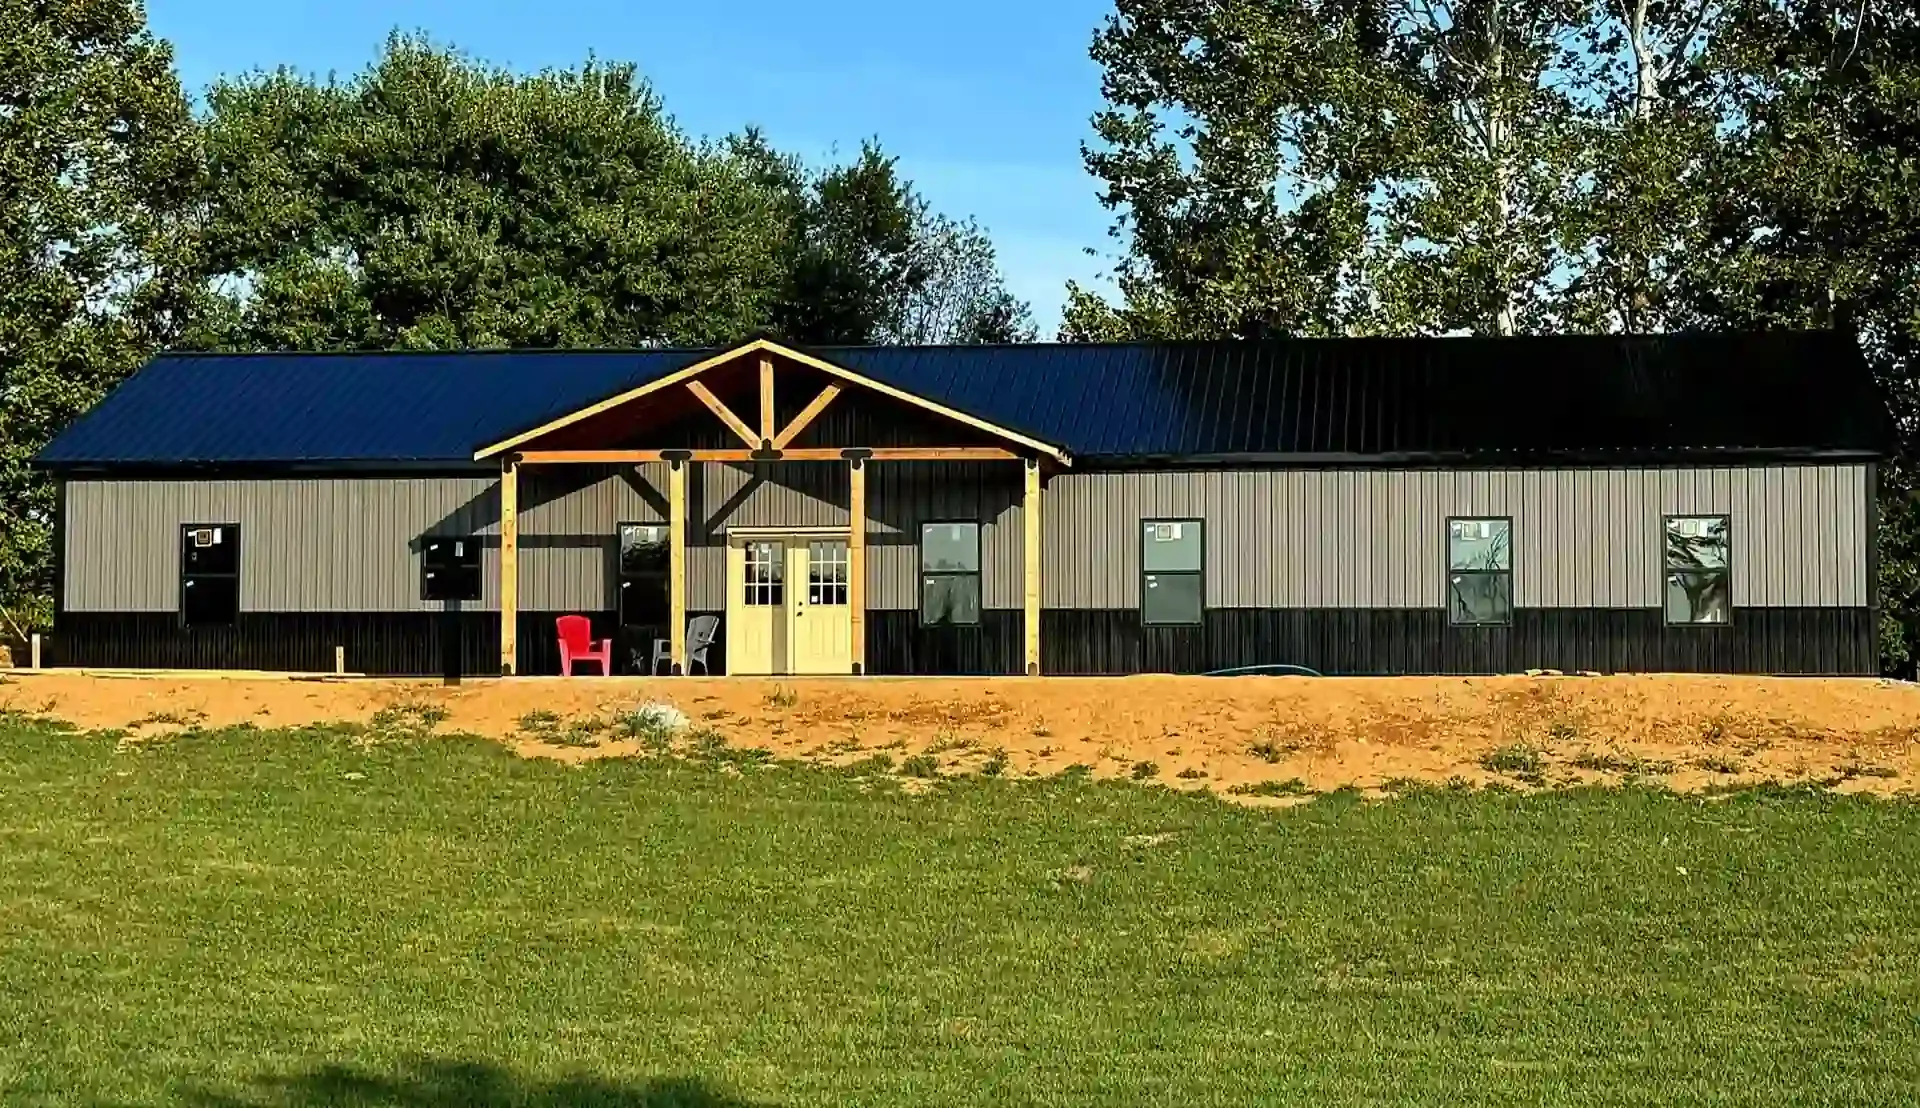 Auburn, Kentucky · Snowden Estate
Schedule A Call With Joe Montgomery
Choose a time below. Have your land or lot details, a rough budget, and the Barn House Co. plan you are leaning toward, and Joe will map out the programs that fit.
Frequently Asked Questions About Barn House Co. And Barndominium Financing
The questions buyers ask most before building a barndominium with Barn House Co., answered plainly.
Where does Barn House Co. build?
Barn House Co. builds from its Temple office across 24 Texas cities, including Austin, Belton, Bryan, College Station, Dallas, Killeen, San Antonio, Seguin, Tyler, and Waco. It has also completed homes in Kentucky, from Bowling Green and Louisville to Owensboro, and takes on new Kentucky projects case by case. Our financing covers all 50 states.
Can I get a construction loan for a barndominium built by Barn House Co.?
Yes. As long as the home sits on a permanent foundation, on land titled to you by closing, with proper zoning and permits, it is financed as permanent residential construction. One-Time Close, the Hybrid Construction Loan, and Two-Time Close are available across Conventional, FHA, VA, Jumbo, and ITIN programs, subject to credit qualification.
Can I finance a shell-only barndominium build?
No. We only finance turnkey builds, meaning homes completed under the contract by an approved builder. Finishing a shell yourself, or hiring your own trades to finish it, counts as owner-building, and none of our programs allow it.
Can I finance a barndominium with an oversized garage or a workshop?
Often, yes. Barndominiums with large attached garages qualify when there are enough comparable sales nearby to support the value and the space is not used to run a full-time business. Working shop homes built around a business are not eligible. A separate garage, a combo workshop, or another unusual structure on the land is reviewed case by case by Joe Montgomery and our Loan Committee.
Can I use land I own, or a lot in Highland Branch or Iron Oak Reserve, toward my down payment?
Yes, in qualifying scenarios. The value of land you own, or buy in the same closing, is credited toward your down payment, and enough equity can cover it completely. A remaining land loan can be paid off at closing, and the deed must be in your name by then.
Can veterans build a barndominium with no money down?
Yes. Eligible veterans with full entitlement can finance up to 100% through our VA Hybrid and Two-Time Close construction loans, with no mortgage insurance and a 640 minimum credit score. VA construction loans run up to $1.5 million, and up to $3 million by exception.
Can I add a Casita without refinancing my first mortgage?
Yes. Our 2nd Mortgage Construction-to-Permanent loan pays for the Casita in draws while it is built, then becomes a fixed-rate, closed-end second lien. Your first mortgage keeps its rate and balance. There is no set maximum, and each project is reviewed on its plans, your equity, and your credit.
What credit score do I need for a barndominium construction loan?
Conventional, FHA, and VA construction start at 640. ITIN construction needs 680, investment construction needs 680 to 700 depending on loan-to-value, and Jumbo construction needs 720. Joe Montgomery can look at your credit before you apply.
Can I build a barndominium as a rental or a second home?
Yes. Our Two-Time Close investment construction program covers 1 to 4 unit site-built properties, and second home construction is available through Conventional and Jumbo programs. FHA and VA do not extend to second homes or investment properties.
Why does it matter that Barn House Co. is already a registered builder?
Approving a builder takes real work. A lender that has never worked with a builder must gather the company's financials, vet it, and get it set up on draws first, and a lot of builders would rather not go through that again.
Barn House Co. is already registered with our bank, so that step is behind you. Your approval is the only one left, which improves and speeds up the closing process.
Contact Barn House Co. In Temple, Texas
Book a consultation with Barn House Co., or talk to Joe first and find out what your budget supports.
The BuilderBarn House Co.
CEO & Founder: Jonny Chavarria
Sales Manager & Marketing: JP Pietras
3211 E Adams Ave
Temple, TX 76501
Phone: (254) 541-7769
Website: barnhouseco.net
Hours: Monday to Friday, 8:00am to 5:00pm. Saturday by appointment. Closed Sunday.
Joe Montgomery
Top Rated® Nationwide Mortgage Banker
BuildBuyRefi.com, powered by The Federal Savings Bank
NMLS ID# 406818
The Federal Savings Bank: federally chartered, FDIC insured, veteran owned, and licensed nationwide. NMLS #411500.
One Builder From Plan To Keys
Barn House Co. handles design, construction, and finishes under one turnkey contract, from an office in Temple, with a leadership team that works in English or Spanish.
Talk through the design with Barn House Co. and the loan with Joe Montgomery at the same time, before anything is signed.
Where Barn House Co. Builds Custom Barndominiums
Working out of Temple, Barn House Co. covers 24 Texas cities, from the Hill Country and the Austin to San Antonio corridor to Waco, Bryan, Dallas, and East Texas. It has also completed homes in 13 Kentucky communities, and new Kentucky projects are considered case by case.
Texas
Kentucky
For buyers searching for a barndominium builder in Temple or Belton, custom barndominium builders near Austin or San Antonio, barndo builders in Waco and College Station, or barndominium construction loans in Texas, this is the area Barn House Co. covers.
Our lending reaches every state. BuildBuyRefi.com is licensed in all 50, so Texas and Kentucky builds are both covered, as are buyers moving in from elsewhere.
More Registered Builders Serving Texas Buyers
Our bank has nearly 2,000 registered builders and dealers. Tell Joe Montgomery about your land and plans, and he can suggest others that fit.
Financing Resources
As Seen In