Get Up To 100% Financing & *$50K ExtraWhen You Build With Sposen Signature Homes
Lot and home packages, pool homes, multigenerational plans, and duplexes across Southwest Florida, financed through FHA, VA, Conventional, Jumbo, ITIN, and second home construction programs. One direct lender underwrites, funds, and manages every draw in-house.
Meet The Registered Home Builder
How Do You Finance A New Home With Sposen Signature Homes?
Sposen Signature Homes is a registered builder with our bank, so buyers can finance both the lot and the build through BuildBuyRefi.com, with up to 100% financing available on eligible programs.
The builder review is already done, which means the only approval left is yours. Builders often slow down when a buyer brings in a lender they have never worked with, because it means new paperwork, new calls, and a new draw process. Choosing a lender that has already approved the builder removes that step and helps the closing move faster.
Sposen Signature Homes builds custom site-built homes across Lee, Charlotte, Collier, and Hendry counties in Southwest Florida. Every floor plan is built on the buyer's own lot, whether that lot is already owned or still being purchased.
That makes the loan structure matter. The land, the construction, and the permanent mortgage all need to line up. We handle all three in-house, from underwriting through every draw payment to the builder.
Many Sposen buyers live far from Cape Coral. The builder's own customer reviews describe homeowners following their builds from New Jersey and from Israel through an online construction portal. We lend in all 50 states, so a buyer's home state does not limit the loan.
Sposen Signature Homes buyers work directly with Mark Rempel, Top Rated® Nationwide Mortgage Banker, NMLS ID# 2844127, BuildBuyRefi.com, powered by The Federal Savings Bank, for guidance on eligibility, loan structure, and closing. New Construction Loan Specialist
Who Builds Sposen Signature Homes
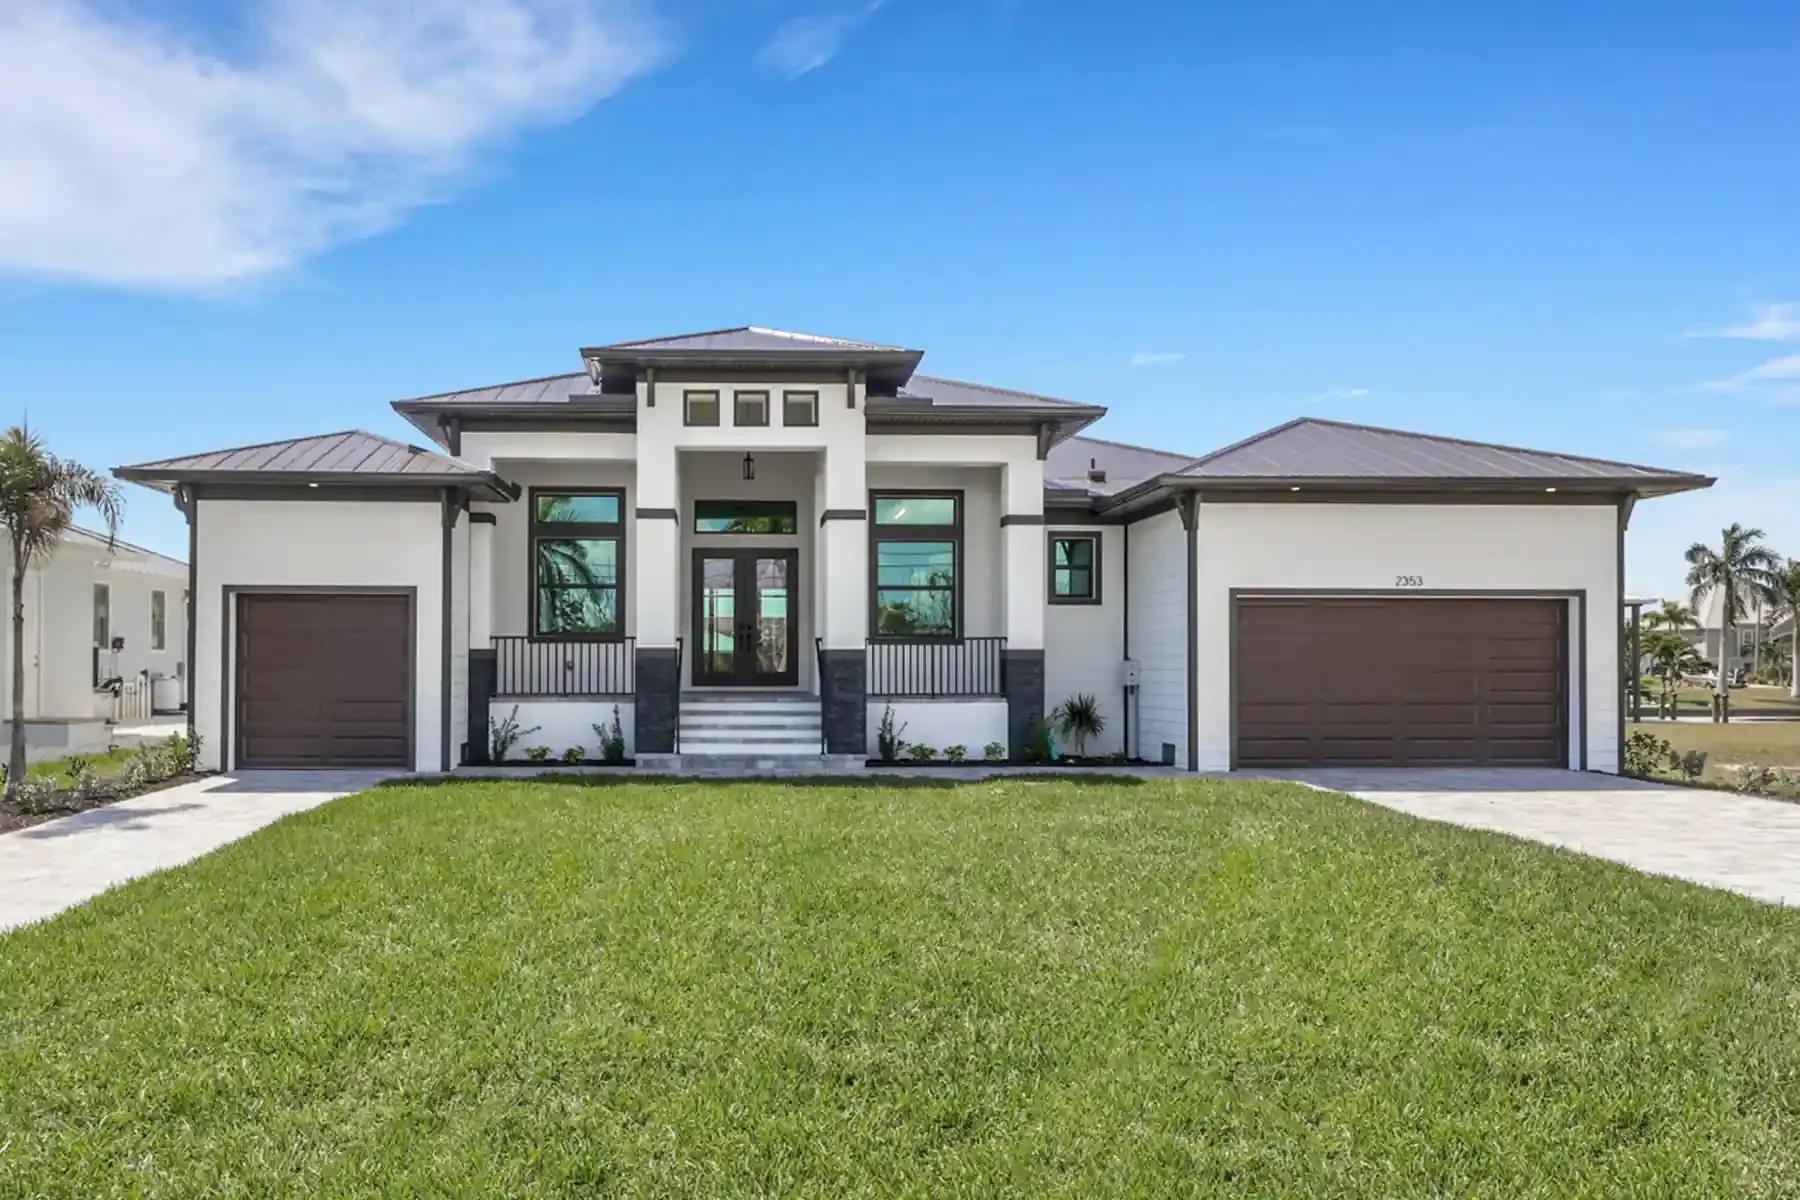
Sposen Signature Homes is a Cape Coral home builder and a Castle Real Estate company, holding Florida license #CBC008854. The company reports 12 years in business, more than 740 homes built, and 24 design awards, including Showcase of Homes recognition.
The company names integrity, quality, and value as the core of how it operates. Its team brings more than 65 years of combined construction experience, and its plans focus on connecting the interior of the home to the outdoor living areas, with most floor plans offered in three exterior elevations.
The Leadership Team
Neil Eisner
Partner and Managing MemberMore than 25 years in homebuilding, from land acquisition and sales to construction operations. Before co-founding Sposen, he served as Chief Operating Officer and President of Transeastern Homes. He is a two-term past president of Florida's Gold Coast Builders Association, which named him its builder of the year, and an active NAHB member.
Albo Antenucci Jr.
Partner and Managing MemberMore than 40 years in commercial, residential, and mixed-use real estate development. He has been a principal of Castle Real Estate Group since 2010 and earlier served as CEO and President of American Real Estate Partners, the public company now known as Icahn Enterprises.
Jeremy Sposato
Managing MemberA Fort Myers resident since 1986 and a licensed real estate professional since 2003, with involvement in more than 3,500 transactions and over 15 years focused on new construction. He also owns Sposen Realty & Development and founded Houses to Homes, a charity that funds local help for single parents.
Sposen buyers track their schedule and construction progress through an online portal. The builder's reviews describe a team that includes construction managers, a design concierge for selections, and a warranty manager. For a financed build, a clear schedule helps everyone see where the project stands each time a draw is requested.
Four Home Series, Built On Your Lot
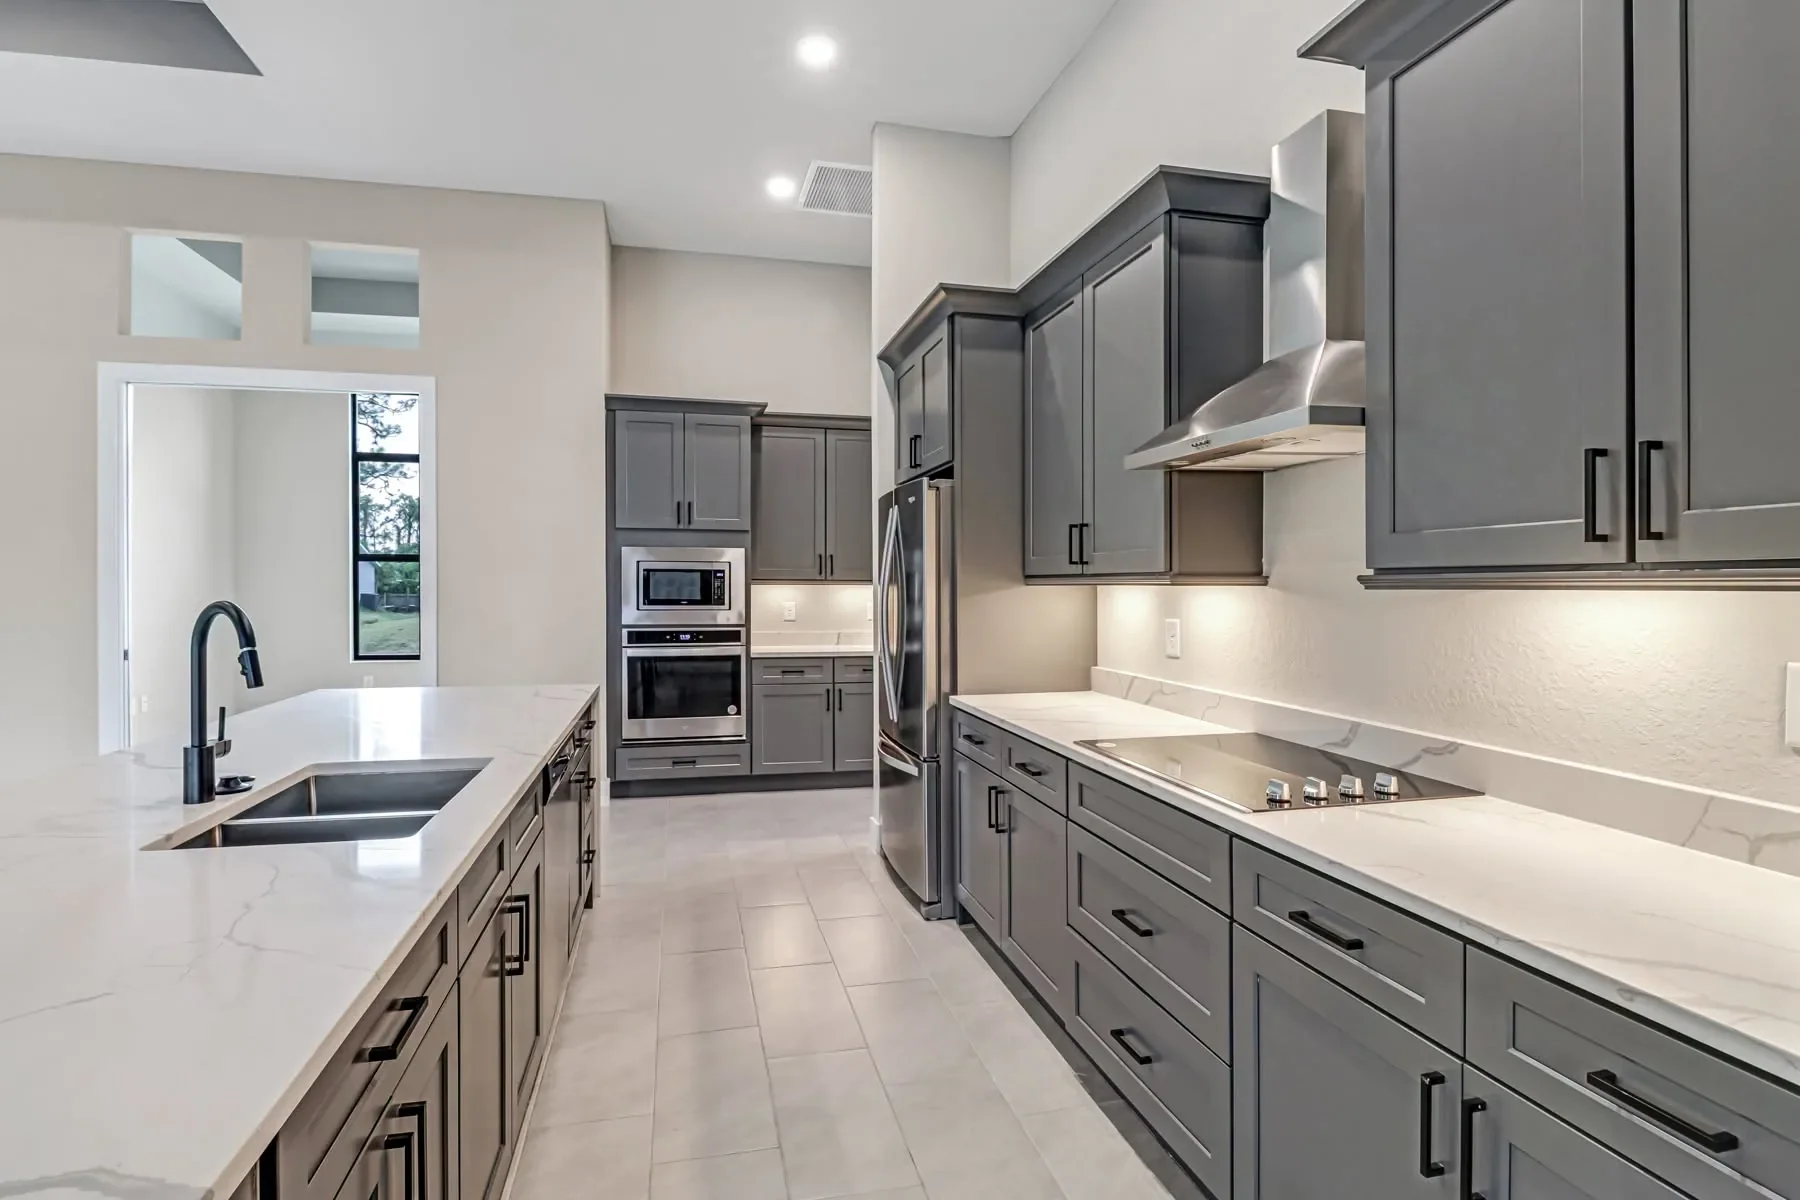
Sposen groups its floor plans into four series, from efficient three-bedroom homes to multigenerational plans and duplexes. Buyers can build a published plan on their lot, request a custom design, or ask about move-in ready homes. Every series fits the same financing approach: the land, the build, and the permanent mortgage handled by one lender.
Express Series
Three plans from about 1,400 to 1,700 square feet, with three or four bedrooms and two baths. Sposen designs these around an open great room tied to the kitchen and dining area, with a lower-maintenance footprint. A practical fit for first-time buyers, downsizers, and second homes.
Signature Series
Five plans from about 1,850 to 2,250 square feet, with three to five bedrooms and up to three and a half baths. Most are offered in a choice of exterior styles, including Modern and Transitional, so the same layout can look very different from the street.
Sterling Series
Sposen's largest standard plans, about 2,400 to 2,600 square feet, with three or four bedrooms and three baths. The Mira Vista is offered in Transitional, Coastal, or Modern exteriors.
Specialty Plans
Plans built for specific needs: the Harmony and Melody for multigenerational living, the Rue and Primrose duplexes with two separate three-bedroom units, and the Ventura with an oversized garage running the full length of the house. Sizes run from about 1,900 to just over 3,000 square feet.
Duplexes and multigenerational plans open financing options many buyers do not expect. A duplex can be financed as a primary residence when the buyer lives in one unit, or as an investment property, in qualifying scenarios. Land the buyer already owns can also count toward what a qualified borrower brings to closing.
Pool Homes, Designed Into The Build
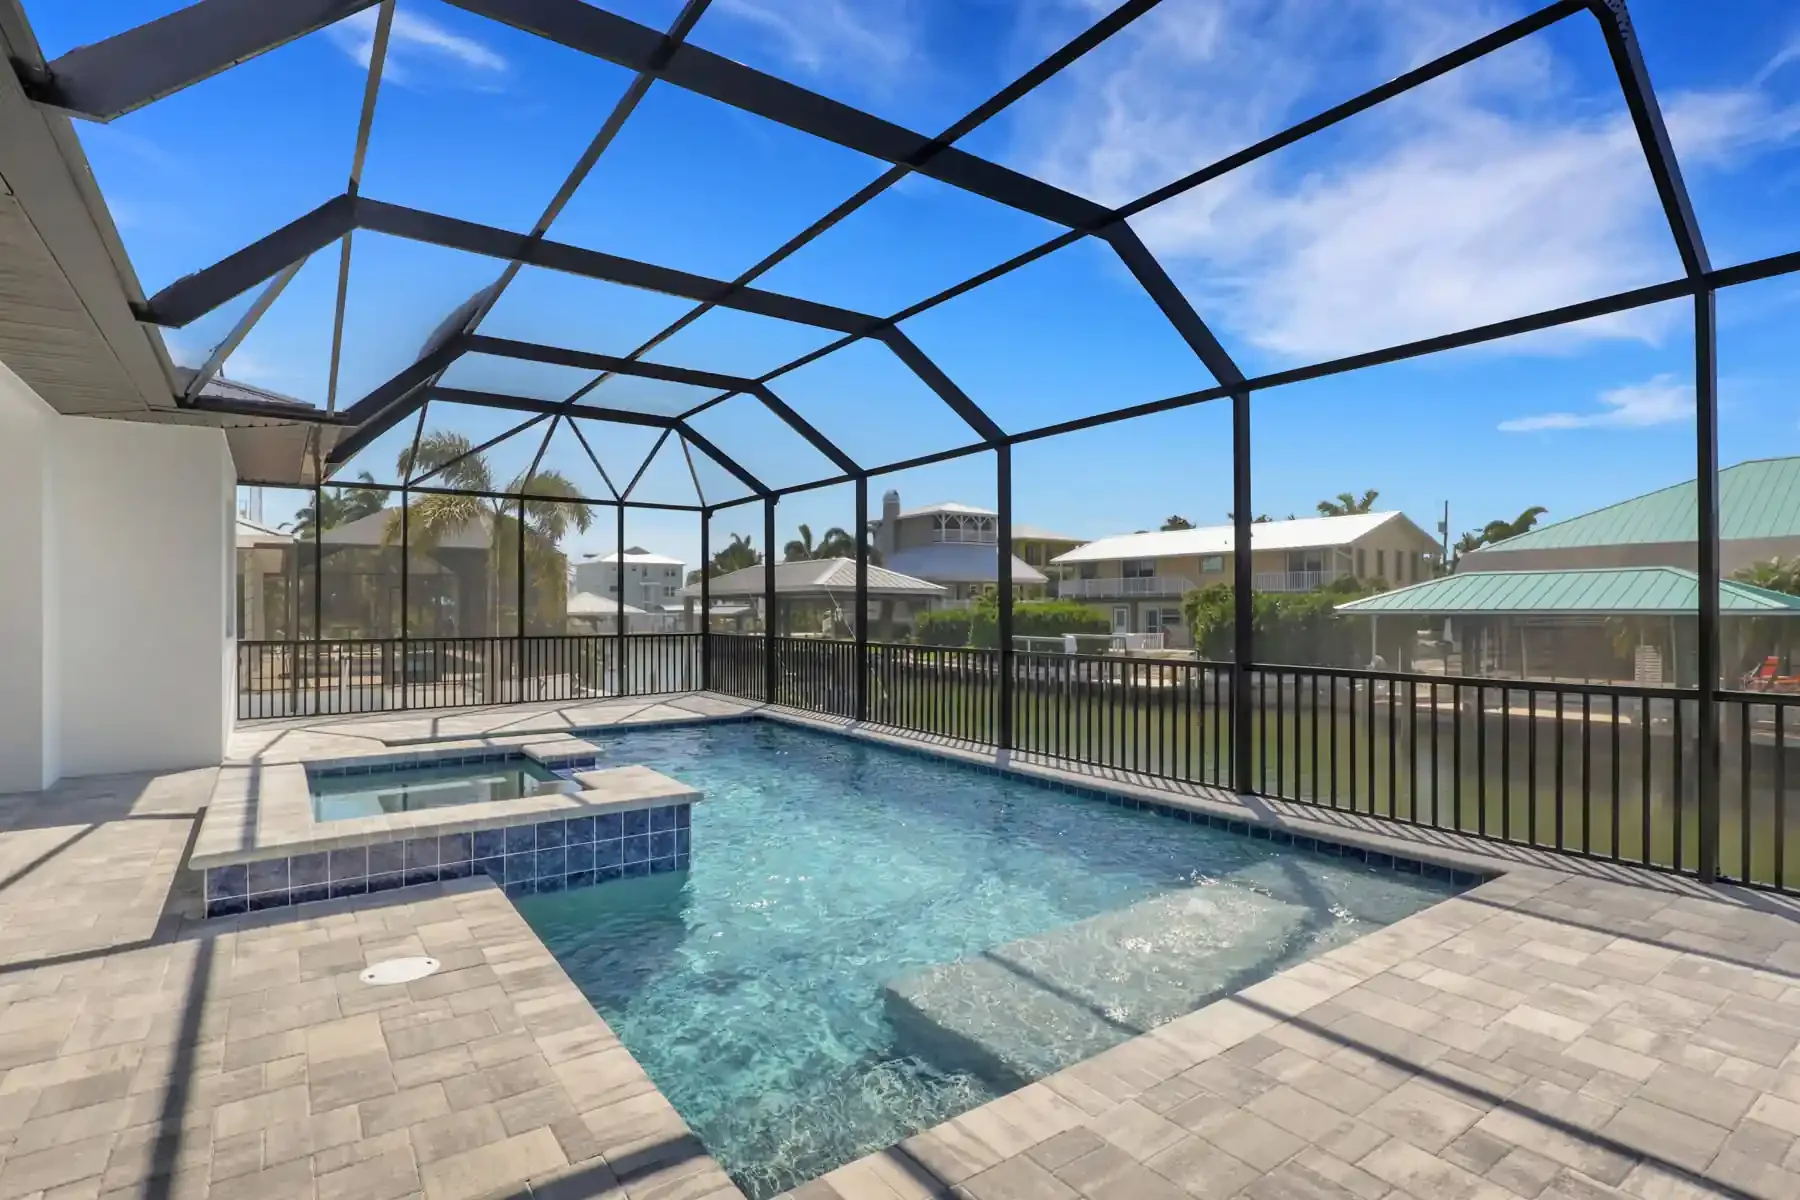
Sposen offers three pool packages matched to its home series. The Express package starts with a 12 by 25 foot pool, the Signature package a 14 by 28 foot pool, and the Sterling package a 16 by 32 foot pool. Each includes a paver deck, a swim-up bench, a three to five foot depth, and LED lighting.
Pool Upgrades Available Through Sposen
Sposen also includes a $35,000 builder allowance with its homes toward permit and impact fees, site preparation, private inspections, builder's risk insurance, and surveys and utilities. On the financing side, a pool that is part of the build contract can be financed inside the construction loan when the appraisal supports it.
Building In Southwest Florida From Another State Or Country
Many of Sposen's customer reviews come from buyers who were not local when they built. Homeowners in New Jersey describe managing their build from home, and investors in Israel describe choosing plans, finishes, and colors through video calls with Sposen's design team.
Sposen supports that with an online portal where buyers see construction photos, the schedule, and upcoming milestones. Reviewers also describe help finding and negotiating a lot, and guidance on which upgrades fit a home they plan to live in, rent long term, or rent seasonally.
The financing has to work from a distance too. We lend in all 50 states, and second home and investment property construction are both available in qualifying scenarios. Each draw is released after an independent third-party inspection confirms the work on site, so a buyer who lives elsewhere is not relying on photos alone to know the build is moving.
Buyers living outside the United States should talk with Mark Rempel early. Program options depend on residency and documentation, and ITIN construction financing is available for qualified borrowers.
What We Can And Cannot Finance
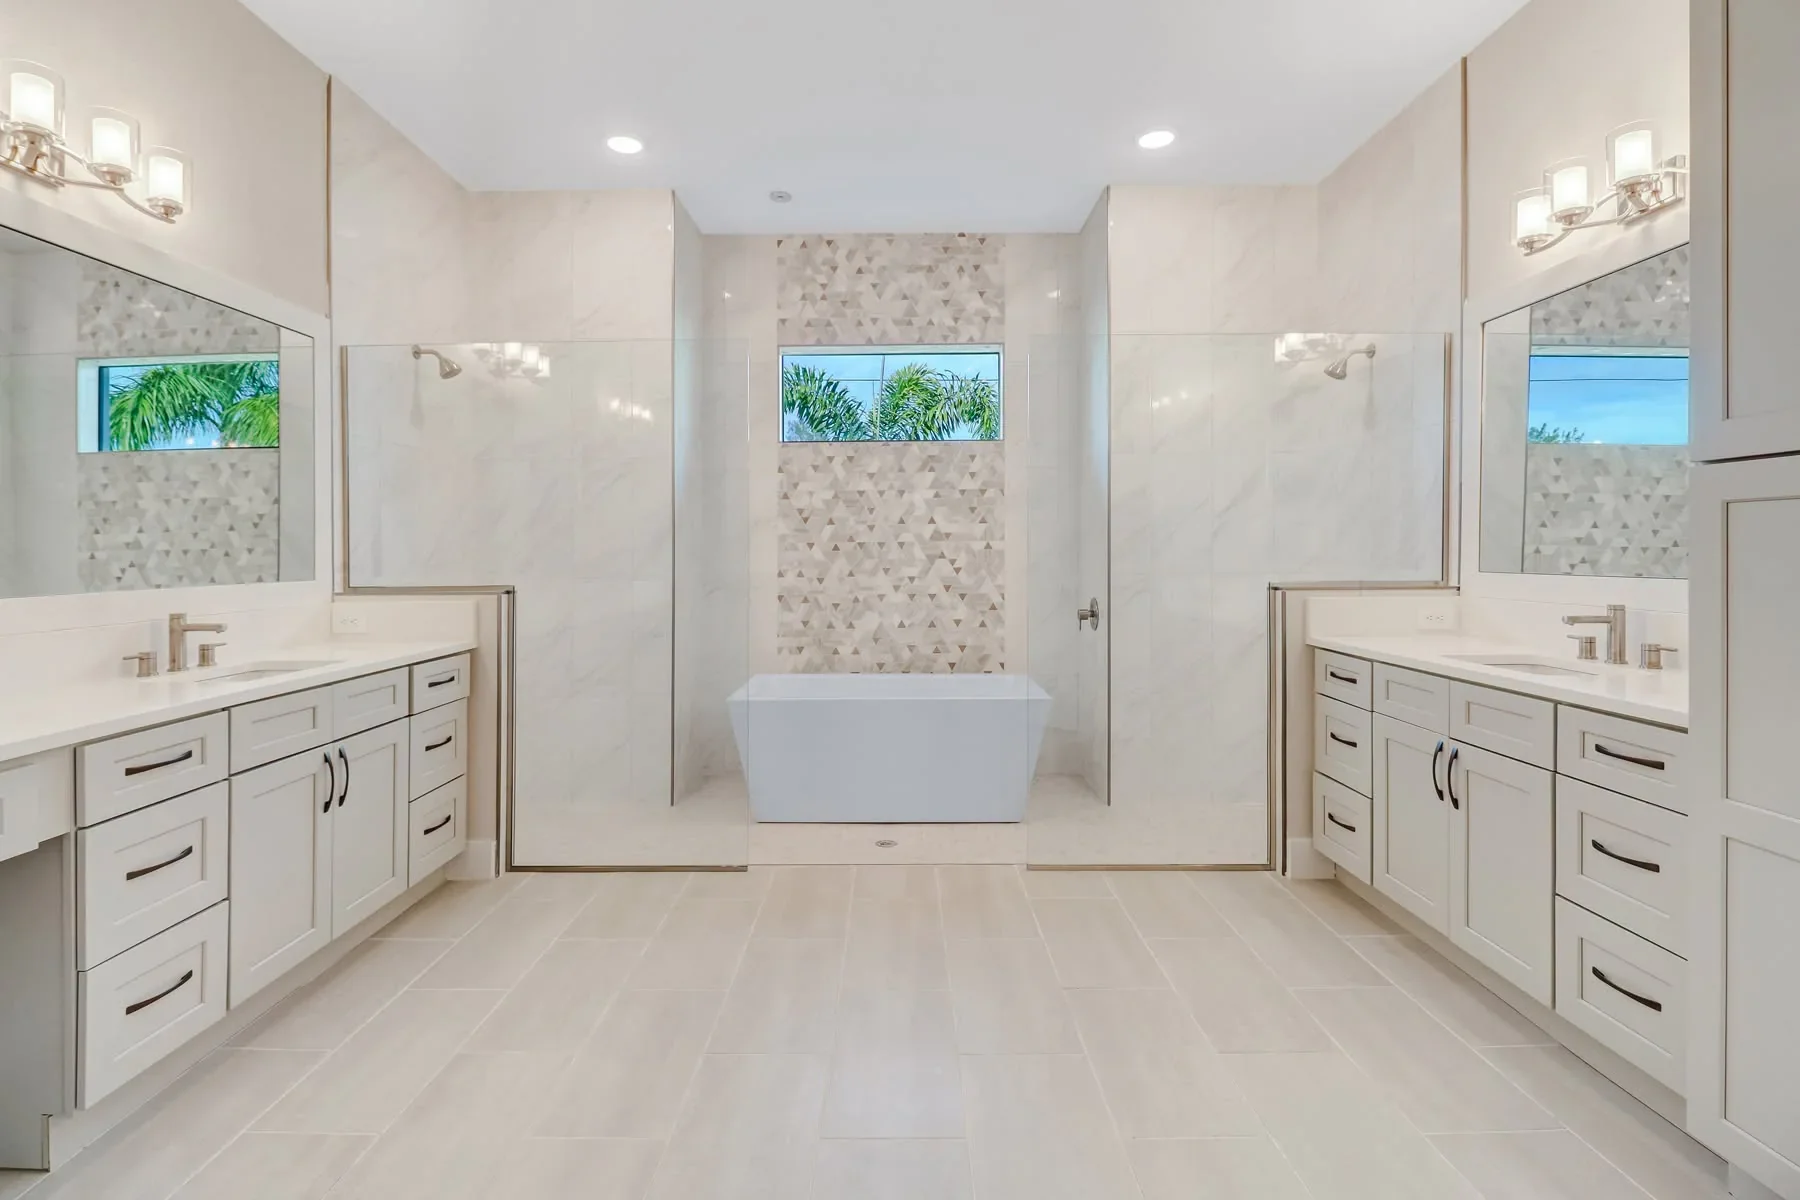
Site-built lending has fewer restrictions than manufactured or modular, but the lines are still firm, and finding out late can cost a buyer months. The short version: a licensed registered builder, a lot the borrower owns at closing, and a build contract the appraisal supports.
What We Can Finance
Mortgage Eligible
- New Sposen homes built on a lot the borrower owns or purchases as part of the loan
- Lot purchase and construction combined in one financing plan
- Lots already owned, with existing lot equity applied toward the project
- Pools, screen enclosures, and paver decks included in the build contract when the appraisal supports them
- Primary residences, second homes, and investment properties
- Owner-occupied duplexes and multigenerational floor plans
- Larger builds through Jumbo construction up to $4.5 million, case by case
What We Cannot Finance
Not Mortgage Eligible
- Self-build or owner-as-contractor projects. A licensed registered builder has to be on the file
- Lots the borrower leases or will not own at closing
- Homes under 400 square feet
- Detached structures that are not permanently affixed, such as sheds or tiny homes, as part of the mortgage
- Upgrades left out of the build contract cannot be added to this construction loan after closing. Later projects can be financed separately through our renovation and 2nd mortgage options
Why The Contract And Appraisal Set The Budget
The construction loan is based on the lot, the build contract, and the home's appraised value once complete. The appraisal is done by an independent appraiser, and we have no influence over the value it comes back at. That is why every item a buyer wants financed, including a pool, an upgraded finish package, or an extended screen enclosure, needs to be written into the contract before closing.
Run a specific plan past Mark Rempel before signing a build contract. Getting the lot, contract, and loan structure lined up first is what keeps a file from stalling later.
How A Sposen Build Comes Together
Seven stages, in the order they happen. Decisions made early set the budget everything else has to fit inside, so the order matters as much as the steps.
-
Set The Budget With Mark Rempel
Knowing the budget before choosing a lot or floor plan means every decision gets made against the full project cost. Mark reviews which structure fits the lot, the home, and how the buyer plans to use it, whether that is One-Time Close, Two-Time Close, or our Hybrid Construction Loan, across FHA, VA, Conventional, Jumbo, ITIN, second home, and investment programs.
-
Secure The Lot
Buyers who already own a lot move straight to step 3. For everyone else, Sposen's reviewers describe the team helping them find and negotiate a lot across its Southwest Florida build areas. The lot purchase can be financed together with the construction.
-
Choose A Plan, Elevation, And Pool Package
Buyers pick from the four home series or request a custom design, choose an exterior style, and decide on a pool package and upgrades. Anything the buyer wants financed should be settled here, because it needs to be in the build contract.
-
Sign The Contract And Close The Loan
With the plan and lot set, the build contract is signed and the loan closes. Equity in a lot the buyer already owns counts toward the project, which can reduce or eliminate what a qualified borrower brings to closing.
-
Selections And Pre-Start Orientation
Sposen's design concierge walks buyers through colors and finishes, in person or by video call. Reviewers describe a pre-start meeting with their construction manager before work begins, and permits are finalized during this stage.
-
Construction, Portal Updates, And Draws
As the home goes up, buyers follow photos and the schedule through Sposen's online portal. Draws release as stages are completed and verified by an independent third-party inspector, and we fund every draw in-house.
-
Final Walk-Through And Move-In
Reviewers describe a final walk-through with the construction team and a warranty manager for questions after move-in. At completion the loan moves into its permanent phase, either automatically or through a second closing, depending on the structure chosen in step 1.
One builder running the project and one lender funding it, from the first budget conversation through the final walk-through. That is what keeps the build schedule and the draw schedule moving together.
How We Finance A Sposen Build, From Lot To Permanent Loan
A Sposen home starts with a lot and ends with a finished house, sometimes with a pool out back, and the loan has to cover everything in between. BuildBuyRefi.com is powered by The Federal Savings Bank, an FDIC-insured, veteran-owned direct lender licensed in all 50 states, NMLS #411500. We underwrite the lot, the build contract, and the permanent mortgage as one plan.
Three Ways To Structure The Loan
Hybrid Construction Loan
Our in-house structure. Both sets of loan documents are prepared at the start, so it closes like a single loan with one set of fees, while the permanent rate stays open until the home is finished. FHA and VA streamline eligible in qualifying scenarios, and a broker or correspondent lender cannot offer it.
One-Time Close
One application, one closing. The permanent rate is locked at the start, and the loan converts on its own at completion with no second qualification and no second appraisal. A good fit for buyers who want the payment settled before the first draw.
Two-Time Close
The construction loan and the permanent mortgage close separately, so the permanent rate is set at completion based on the market then. We cover the origination fee on the second closing, and FHA and VA borrowers can streamline the permanent loan in qualifying scenarios.
The Program Details Sposen Buyers Ask About
- Up to 100% financing for qualified borrowers on eligible programs, including VA construction with no monthly mortgage insurance for eligible veterans.
- 640 minimum credit score on Conventional and FHA construction.
- Jumbo construction up to $4.5 million, reviewed case by case, for larger Sterling, Specialty, or custom builds.
- Owner-occupied duplexes, second homes, and investment properties, not only primary residences.
- ITIN construction financing for qualified borrowers.
- Lot equity counts. A lot the buyer already owns can be applied toward the project, which often reduces what a qualified borrower brings to closing.
- Pools and upgrades written into the build contract can be included when the appraisal supports them.
- No administrative fees on our construction programs. Ask for every fee line by line on any construction quote you compare.
Why a direct lender matters on a build. A broker hands the file to another company and waits for an answer. A correspondent lender funds the loan and then sells it, so an outside investor's rules decide what happens. We originate, underwrite, fund, and manage draws ourselves, with no wholesale division and no brokered submissions. If a question comes up halfway through the build, the people answering it work here.
Sposen Signature Homes is already a registered builder with our bank, so builder approval is done before a buyer ever applies. From the first conversation, the work stays focused on the borrower and the lot, which improves and speeds up the closing process.
All programs are subject to credit qualification, property eligibility, and applicable program guidelines. Rates, terms, and availability vary by borrower, property, occupancy, and program, and are not guaranteed. Appraisals are performed by independent licensed appraisers and construction inspections are performed by third-party inspectors. Contact your banker for applicable rates, terms, and conditions.
You Do Not Need A Lot Or A Floor Plan Yet.Start With What The Budget Can Support.
A few questions show which programs fit the lot, the home, and the build. No cost, no obligation, and no credit impact to have the conversation.
*$50,000
Additional Funds For Everything The Build Contract Leaves Out
The construction loan covers the lot, the home, and what is written into the contract. Qualified borrowers can also access up to $50,000 in separate, unsecured funds before, at, or after closing, underwritten in-house alongside the mortgage. It does not rely on equity and it does not affect loan-to-value. We are not aware of another lender in this space offering it.
How Sposen Buyers Could Put It To Work
Furnishing a second home or rental
A seasonal rental or a winter home needs to be fully furnished before the first guest or the first season. That means beds, linens, kitchenware, patio furniture, and everything else, all at once.
Pool upgrades added later
The spa, the heater, the salt system, or the outdoor shower that did not make it into the build contract. Adding them after move-in no longer means waiting years or paying cash.
Moving to Florida
Relocating from another state adds up fast: movers, vehicle transport, travel back and forth during the build, and the overlap of carrying two homes for a few months.
Landscaping and outdoor living
Upgraded landscaping, fencing, an outdoor kitchen, or extra paver space. The outdoor projects that make a Southwest Florida home feel finished, and the first items cut from most budgets.
Consolidating debt to qualify
Paying down qualifying revolving balances can improve the debt-to-income ratio, which in some scenarios helps a borrower qualify for the plan or series they actually want.
A cushion during the build
Plans change once construction starts. Having separate funds already approved means a late decision or an unexpected cost does not have to stall the project.
*Up to $50,000 is available to qualified borrowers and can be applied across our loan programs. This is a separate unsecured consumer loan underwritten in-house at the same time as the mortgage. Proceeds cannot be used for a down payment. Approval, amount, rates, and terms depend on credit qualification and are not guaranteed. Contact your banker for applicable rates, terms, and conditions.
Up To 30%
Real Estate Commission SavingsOn The Home You Sell Or The Lot You Buy
A Sposen build often comes with another transaction attached: a current home that needs to sell, or a lot that needs to be purchased first. Qualified borrowers can save up to 30% on listing-side real estate commissions on those transactions through our participating agent network, taken as a closing cost credit or applied toward a rate buy-down.
Selling A Home In Another State
Many Sposen buyers are moving to Southwest Florida from somewhere else. The network covers all 50 states, so the savings follow the home being sold, wherever it is.
Buying An Agent-Listed Lot
When the lot for the build is listed with a real estate agent, the network can represent that side of the purchase and the savings apply there as well.
Credit Or Rate Buy-Down
The savings can come back as a credit toward closing costs or go toward a lower rate. Mark Rempel can run the numbers both ways to see which helps the file more.
What This Covers, And What It Does Not
This benefit applies only to real estate transactions represented by an agent: selling an existing home, buying an existing listed home, or buying land listed with an agent.
It does not reduce the cost of a new home built by Sposen Signature Homes. A build contract is a direct agreement with the builder, with no listing agent and no commission involved.
It is also separate from Sposen's own brokerage, Sposen Realty & Development. The savings come only through our participating agent network, and buyers are free to choose who represents them on any purchase or sale.
No money changes hands between us and the agents in either direction. We do not pay them, they do not pay us, and we earn nothing when a borrower uses one. Paying or receiving fees for referrals of federally related mortgage loans is prohibited by law, and we do not do it.
Commission savings are available to qualified borrowers through a participating real estate agent network, subject to agent availability, program terms, and applicable state law. Savings apply to the listing side of an agent-represented transaction. Actual savings vary by property, sale price, and the agreement reached with the participating agent. This benefit does not apply to the direct purchase or construction of a new home from a builder or dealer. No referral, affiliate, or other fee is paid or received by BuildBuyRefi.com or The Federal Savings Bank in connection with this benefit. Contact your banker for details.
Already Own A Home? Build Onto It With A 2nd Mortgage Construction Loan
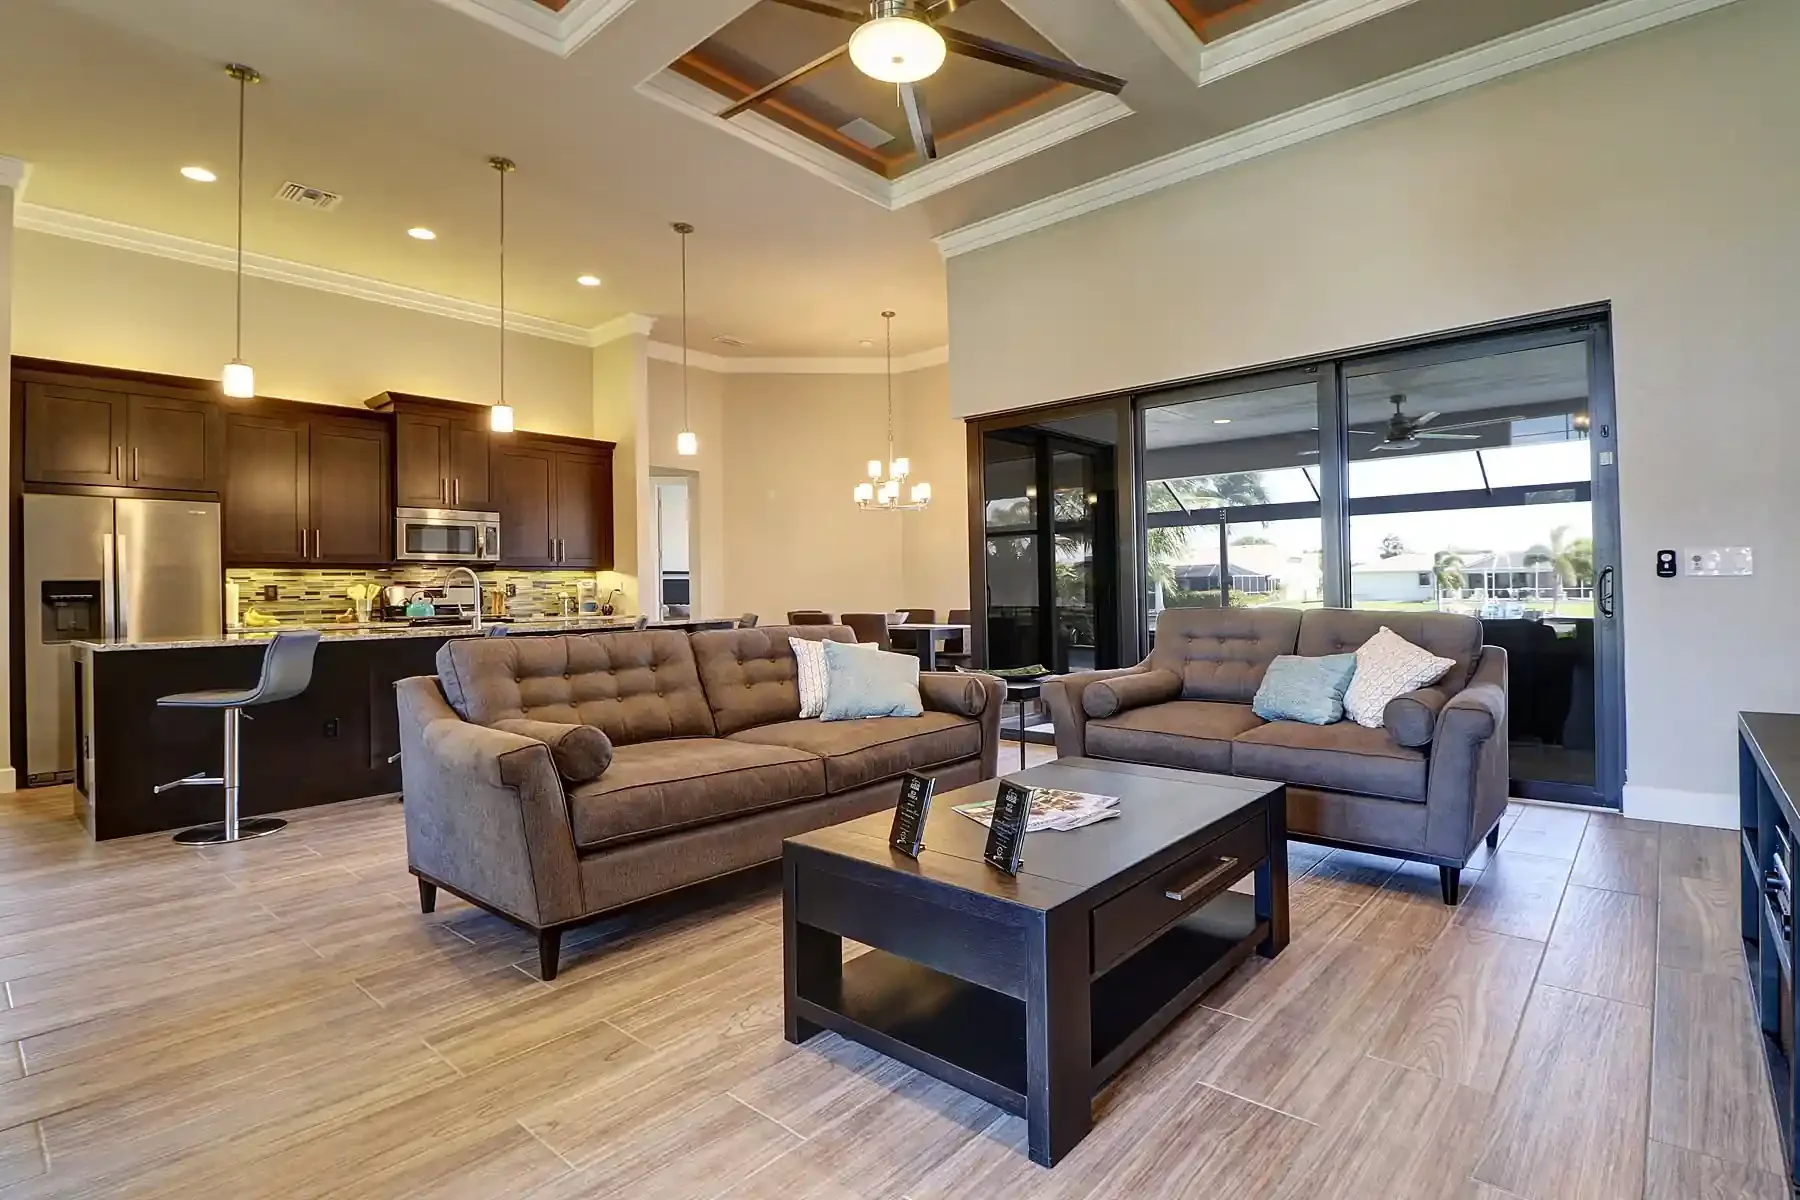
Some homeowners do not need a new house. They need more space, a pool, or a finished project on the home they already have. The hard part is paying for it without losing a low first mortgage rate, and that is exactly what this loan solves.
A large share of homeowners locked in first mortgage rates between 2.5 and 4.0 percent in 2020 and 2021. A cash-out refinance would trade that rate for today's rate on the whole balance, and over the life of the loan that can cost more than the project itself.
Our 2nd Mortgage Construction-to-Permanent loan funds the project while it is being built, then converts to a fixed-rate, closed-end second lien once it is complete. The first mortgage stays in place at its original rate. Only the new money carries a new rate.
Funds are released in draws as each stage of work is completed and inspected, the same way our first-lien construction loans work.
What Homeowners Build With It
Adding A Pool And Screen Enclosure
For owners who skipped the pool at build time, or bought a home without one. The pool, deck, and enclosure get financed as a real construction project.
Primary Suite Or In-Law Suite
A larger primary suite, or a separate suite with its own entry for a parent or adult child who is moving in.
A Second-Story Addition
On a lot with no room to build out, building up adds bedrooms and living space without giving up the yard.
Kitchen And Bath Renovation
A full kitchen or bathroom remodel with real construction scope, funded through draws instead of savings or credit cards.
A Detached Garage Or Workshop
More room for vehicles, tools, storage, or a hobby space, built as its own structure on the property.
A Guest House Or ADU
A separate small dwelling for visiting family or long-term rental use, where local zoning allows it.
We are not aware of another lender offering this structure. Most home equity products hand over a lump sum or a credit line and leave the construction risk with the homeowner. This is a true construction-to-permanent loan in second position, underwritten, funded, and draw-managed in-house, with a licensed builder on the project.
For a Sposen homeowner, it often matters a few years after move-in. The family grows, a parent moves closer, or the pool that was cut from the original budget finally makes sense. That becomes a phone call, not a refinance.
Subject to credit qualification, property eligibility, lien position, available equity, and applicable program guidelines. Rates and terms vary by borrower and property and are not guaranteed. Local zoning and permitting govern what may be built on any given property. Contact your banker for applicable rates, terms, and conditions.
Meet The Banker Assigned To Sposen Signature Homes Buyers
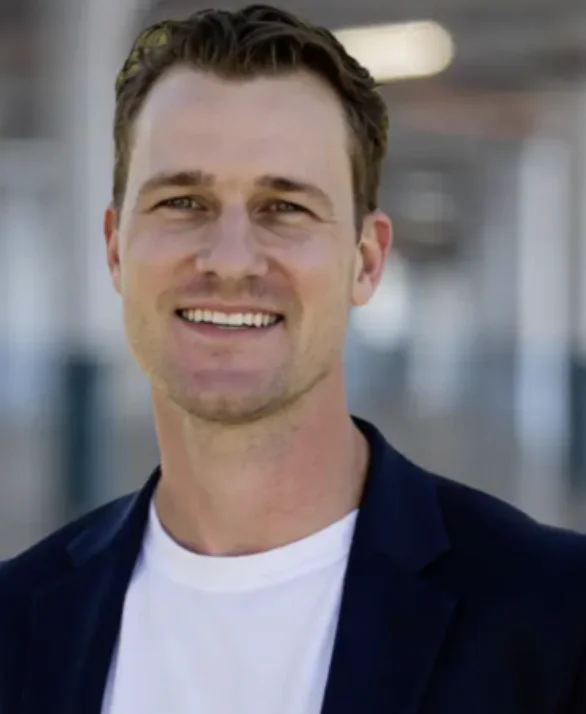
Mark Rempel
Top Rated® Nationwide Mortgage Banker
BuildBuyRefi.com, powered by The Federal Savings Bank
Sposen Signature Homes buyers work directly with Mark Rempel, a member of our New Construction Team, from the first question through the final draw. One banker who knows the file, rather than a new voice every time someone calls.
Mark is originally from Chandler, Arizona, and earned a degree in Strategic Communications from Northern Arizona University. Before mortgage banking, he spent several years in insurance and retirement planning, helping clients understand complex financial products. That background shapes how he structures a loan today: around the buyer's long-term finances, not just the closing date. He recently moved his own family to the Raleigh, North Carolina area, so he understands what a long-distance move involves for buyers relocating to Southwest Florida.
A Sposen build has more moving parts than a standard purchase: a lot that may still need to be bought, a build contract that has to include every item being financed, a draw schedule tied to inspections, and a permanent loan at the end. Lining those up correctly before the contract is signed is what keeps a file from stalling later.
What Mark handles for a Sposen buyer: reviewing eligibility before a lot or plan is chosen, comparing the Hybrid, One-Time Close, and Two-Time Close structures against the specific build, checking whether FHA, VA, Conventional, Jumbo, or ITIN fits best, applying lot equity where the buyer already owns the land, and keeping the draw schedule in step with Sposen's construction team.
He also covers the questions that come up most with Sposen buyers. Whether a duplex can be financed as a primary residence. Whether a second home or rental qualifies. How the process works for someone living in another state or another country. Those conversations cost nothing and happen before anyone signs a contract.
One Lot. One Builder. More Possible Than Most Buyers Expect.
Most people start with a simple question. Can we afford to build a new home in Southwest Florida?
The answer often turns into something bigger than the question.
A Signature plan on a lot they already own, with the pool built in from day one. A multigenerational home with its own suite for a parent. A duplex with a second unit for family or tenants. A winter home finished and furnished before the first season, built while the owners watched every stage from a thousand miles away. All of it financed as one plan instead of pieced together over the next several years.
There is no single right Sposen home. There is the one that fits how a particular family lives, on a specific lot, at a payment they can carry comfortably.
Sposen Signature Homes brings the floor plans and the building experience. BuildBuyRefi.com brings financing built around the whole plan, with Mark Rempel available to show how the programs fit a real lot and a real budget.
The conversation costs nothing, and it is far easier to have before a contract is signed than after.
Ready to Get started With Sposen Signature Homes? Check Your Eligibility Today And Access Up To An Extra *$50,000 Before Or At Close!


Schedule A Free Strategy Call With Mark Rempel
What Homeowners Say About Building With Sposen
Sposen's customer reviews keep returning to the same themes: communication, build quality, and a team that stays reachable from the first meeting to the final walk-through. Below is a summary of what buyers describe, in our words rather than theirs.
Building From Far Away
Owners in New Jersey and Israel describe following their builds through the online portal and making selections by video call, with the team answering questions throughout.
Solid, Quiet Construction
Homeowners describe homes that feel solid and quiet inside, and point to the hurricane-rated windows and doors in their homes.
Coming Through Storms
Two families describe their Sposen homes coming through Hurricane Irma and a later storm with little or no damage while homes nearby were hit hard.
Knowledgeable Construction Managers
Reviewers single out their construction managers by name, from the pre-start orientation through the final walk-through, for clear answers and practical advice.
Help Finding A Lot
Several buyers describe the team helping them locate a lot and negotiate the purchase, including buyers who were not in Florida at the time.
Upgrades Without Pressure
Investors describe being guided toward the upgrades that fit their plans, whether living in the home or renting it, rather than being pushed to add everything.
Sposen also publishes reviews from its subcontractors, which is rare for a builder. Drywall, stucco, and HVAC trades describe organized scheduling, clear communication from the office and the field, and reliable, prompt payment.
That matters to a financed build more than most buyers realize. Trades that are scheduled well and paid on time keep showing up, which keeps each stage moving toward its inspection and its draw. One homeowner noted that permitting took time at the start, and that the build moved quickly once it cleared.
Reviews reflect individual experiences and are summarized from Sposen's published testimonials.
Frequently Asked Questions About Sposen Signature Homes And Construction Financing
The questions buyers ask most often before building with Sposen, answered plainly.
Where does Sposen Signature Homes build?
Sposen builds in Southwest Florida, from Port Charlotte south to North Naples, across Lee, Charlotte, Collier, and Hendry counties. Its build areas include Cape Coral, Fort Myers, Bonita Springs, Estero, Punta Gorda, and Port Charlotte. Our financing is available in all 50 states, so the buyer does not need to live in Florida to qualify.
Can I finance the lot and the construction together?
Yes, in qualifying scenarios. A buyer who still needs a lot can finance the lot purchase and the build as one plan. A buyer who already owns a lot can often apply that lot equity toward the project, which can reduce or eliminate what a qualified borrower brings to closing.
Can I get 100% financing to build a Sposen home?
Qualified borrowers may be eligible for up to 100% financing on certain construction programs, including VA construction with no monthly mortgage insurance for eligible veterans. Eligibility depends on the borrower, the lot, occupancy, and program guidelines.
Can a pool be included in my construction loan?
Yes, when the pool is written into the build contract and the appraisal supports it. The same applies to screen enclosures, paver decks, and other upgrades. Anything left out of the contract cannot be added to the construction loan after closing, so it should be decided before the contract is signed.
Can I build with Sposen if I live in another state or country?
Yes. Many of Sposen's reviews come from buyers who built from out of state or overseas, following progress through Sposen's online portal. We lend in all 50 states, and second home and investment property construction are both available in qualifying scenarios. Buyers living outside the United States should speak with Mark Rempel early, since program options depend on residency and documentation. ITIN construction financing is available for qualified borrowers.
Can I finance a Sposen duplex or investment property?
Yes, in qualifying scenarios. Sposen's Rue and Primrose duplexes can be financed as an owner-occupied two-unit home when the buyer lives in one unit, or as an investment property. Second home construction is also available.
What credit score do I need?
The minimum is 640 on our Conventional and FHA construction programs. Credit score is one factor among several, and Mark Rempel can review where a buyer stands before an application is submitted.
What is the difference between One-Time Close, Two-Time Close, and a Hybrid Construction Loan?
A One-Time Close uses one closing, locks the permanent rate at the start, and converts automatically at completion. A Two-Time Close uses separate closings, so the permanent rate is set when the home is finished. Our Hybrid Construction Loan prepares both sets of documents upfront so it runs like a single close with one set of fees, while the permanent rate stays flexible through completion. All are subject to credit qualification and program guidelines.
Why does it matter that Sposen is already a registered builder?
Builder approval is a real step. A lender with no existing relationship has to collect the builder's financials, run its own review, and onboard the builder before the buyer's file can move, and builders are often slow to repeat that process with a new lender.
Sposen Signature Homes is already registered with our bank, so that work is done. The only approval left is the buyer's, which improves and speeds up the closing process.
Can I add a pool, addition, or renovation to a home I already own without refinancing?
Yes. Our 2nd Mortgage Construction-to-Permanent loan funds the project during construction and converts to a fixed-rate, closed-end second lien at completion. The existing first mortgage stays in place at its original rate. It works for pools, suite additions, second-story additions, major renovations, and detached garages, subject to credit qualification, available equity, and local zoning.
Why Buyers Choose Sposen Signature Homes
Sposen combines a leadership team with decades of homebuilding and development experience and a build process designed so buyers can follow every stage, even from far away.
Buyers get access to four home series, multigenerational and duplex plans, custom design, three pool packages, a $35,000 builder allowance, help finding a lot, and an online portal for schedules and progress photos. One builder, one team, and one project schedule from contract to walk-through.
Just as important, Sposen works with buyers who are starting from very different places.
You may already own a lot in Cape Coral and want to know what it will take to build on it. You may still be searching for one. You may be planning a winter home from another state, a duplex as an investment, or a smaller home to downsize into.
Each of those leads to a different plan and a different loan, and the time to sort that out is before a contract is signed.
The financing follows the same idea. The right structure depends on what is already settled: whether the lot is owned, whether the buyer is a veteran, whether the home will be a primary residence, second home, or rental, whether a pool is part of the plan, and whether the rate should be locked now or left open until completion.
Sposen Signature Homes answers the building questions. Mark Rempel answers the financing questions, and both conversations can happen before a single dollar is committed.
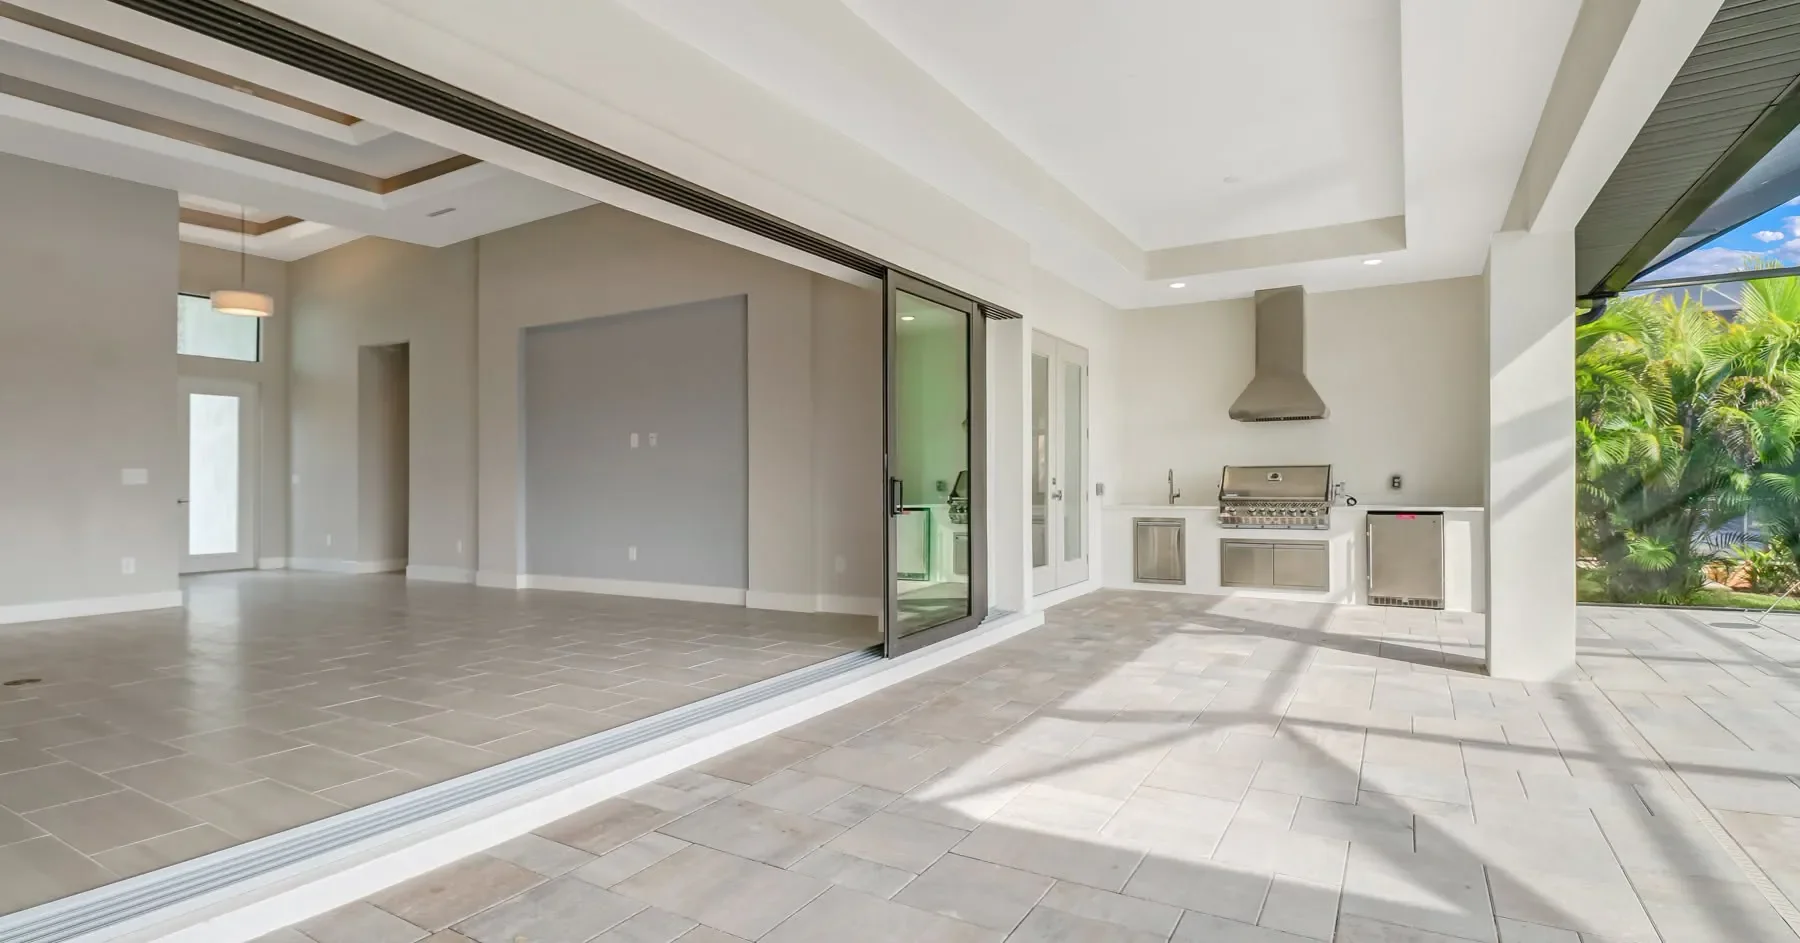
Contact Sposen Signature Homes
Visit Sposen's Cape Coral office to review floor plans, selections, and available lots. Or start with the financing and find out what the build can support first.
The Builder
Sposen Signature Homes
2311 Santa Barbara Blvd, Suite 112
Cape Coral, FL 33991
Phone: (239) 244-8886
Email: hello@sposenhomes.com
Website: sposenhomes.com
Florida License #CBC008854
Hours
Monday through Friday: 9:00 AM to 5:00 PM
Saturday: 10:00 AM to 3:00 PM
Sunday: By appointment
Financing Contact
Mark Rempel
Top Rated® Nationwide Mortgage Banker
BuildBuyRefi.com, powered by The Federal Savings Bank
NMLS ID# 2844127
New Construction Loan Specialist and VA Construction Loan Specialist. Mark reviews eligibility, compares loan structures against the specific build, and stays on the file through the final draw.
The Federal Savings Bank, NMLS #411500. FDIC insured, veteran owned, federally chartered, and licensed in all 50 states.
Ready to see what a Sposen build could look like on your lot? Check your eligibility or schedule a time to talk it through.
Where Sposen Signature Homes Builds
Sposen is based in Cape Coral and focuses its building in Southwest Florida, from Port Charlotte south to North Naples. That covers Lee, Charlotte, Collier, and Hendry counties, with six primary build areas.
Sposen's Build Areas
Cape Coral
Sposen's home base. The city is best known for waterfront living, with roughly 400 miles of canals running through it.
Fort Myers
Warm weather all year, nearby beaches, and steady growth in new shopping and services.
Bonita Springs
Just north of Naples, known for its stretch of Gulf beachfront and clear coastal water.
Estero
Between Fort Myers and Naples along the Gulf. The name comes from the Spanish word for estuary, which describes the area well.
Punta Gorda
A community with a strong local culture, set along the water of Charlotte Harbor.
Port Charlotte
The northern end of Sposen's build area, on Charlotte Harbor and a frequent pick for retirees relocating to Florida.
Counties Served
For buyers searching Cape Coral home builders, new construction in Fort Myers, or building a home on your own lot in Southwest Florida, Sposen covers the area from Charlotte Harbor to North Naples. Lot conditions, permitting, and fill requirements vary from one area to the next, which is why the lot and the plan should be reviewed together before a contract is signed.
On the lending side, there is no geographic limit. BuildBuyRefi.com is powered by The Federal Savings Bank, licensed in all 50 states, so the financing works anywhere in Sposen's build area and for buyers living anywhere in the country.
More Resources For Building With Sposen
Program details and related pages for buyers planning a new build in Southwest Florida. Mark Rempel can narrow the options quickly once he knows the lot, the plan, and how the home will be used.
Construction Loan Programs
One-Time Close, Two-Time Close, and the Hybrid Construction Loan, with FHA, VA, and Conventional construction options explained side by side.
ADU Financing
For homeowners adding a guest house or second dwelling, including how financing works while keeping an existing first mortgage in place.
Registered Home Builders Directory
Browse more than 1,800 builders and dealers already registered with our bank, searchable by location and home type.
BuildBuyRefi.com
Construction, purchase, and refinance programs from a direct lender licensed in all 50 states, powered by The Federal Savings Bank.
Sposen Signature Homes is one of more than 1,800 builders and dealers registered with our bank. Other registered Florida custom home builders include Glades & Bay Construction, Coastal Classic Homes, and Brije Homes.
Or browse the full Registered Home Builders directory.