Featured Registered Builder · Hampton Roads, Virginia
Build, Remodel, Or Add On With Almond Exteriors.Up To 100% Financing & *$50K Extra.
Construction, remodel, and home addition loans in Hampton, Newport News, Poquoson, and York County, including jumbo, second home, investment, and multi-family construction, from a direct lender already approved with Almond Exteriors.
How Do You Finance A Custom Home With Almond Exteriors In Hampton Roads?
Almond Exteriors is already registered with our bank, so homeowners in Hampton, Newport News, Poquoson, and York County can finance a custom or waterfront home with Almond Exteriors through BuildBuyRefi.com. That covers One-Time Close, Two-Time Close, and our Hybrid Construction Loan across Conventional, FHA, VA, and jumbo construction up to $4.5 million, for primary residences, second homes, and investment properties, with up to 100% financing for eligible veterans or for borrowers whose land equity covers the down payment.
Builders often push back on a new lender because it means sending company financials, sitting through approval calls, and learning a draw process they have never used. Almond Exteriors has already been through that with us, so the only approval left is yours, which improves and speeds up the closing process.
Founded in 2000, Almond Exteriors designs and builds site-built custom homes across Coastal Virginia. The company is known above all for raised coastal and waterfront homes, often three levels with large garages and storage underneath, built to meet elevation and flood-zone requirements. It also builds off the water, in established developments, and on lots clients already own, and it takes on remodels and home additions for homeowners who want to stay put.
We finance every one of those paths in-house. Site work, foundations, and elevation requirements written into the Almond Exteriors build contract can be part of the construction budget, and a remodel or addition can be financed without touching your current first mortgage.
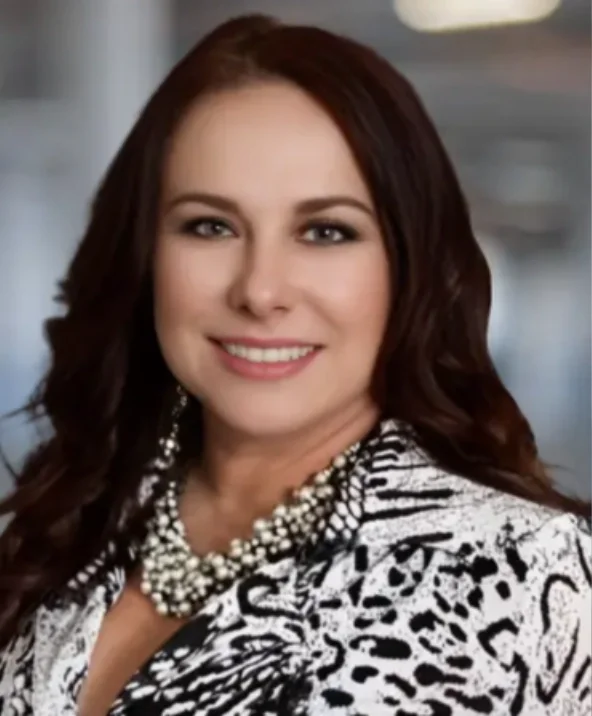
Almond Exteriors clients work directly with Ilonka Avila, Top Rated® National Vice President, NMLS ID# 47252, BuildBuyRefi.com, powered by The Federal Savings Bank, from the first eligibility question through the final draw.U.S. Air Force Veteran | 35+ Years In Mortgage Lending | Construction And Renovation
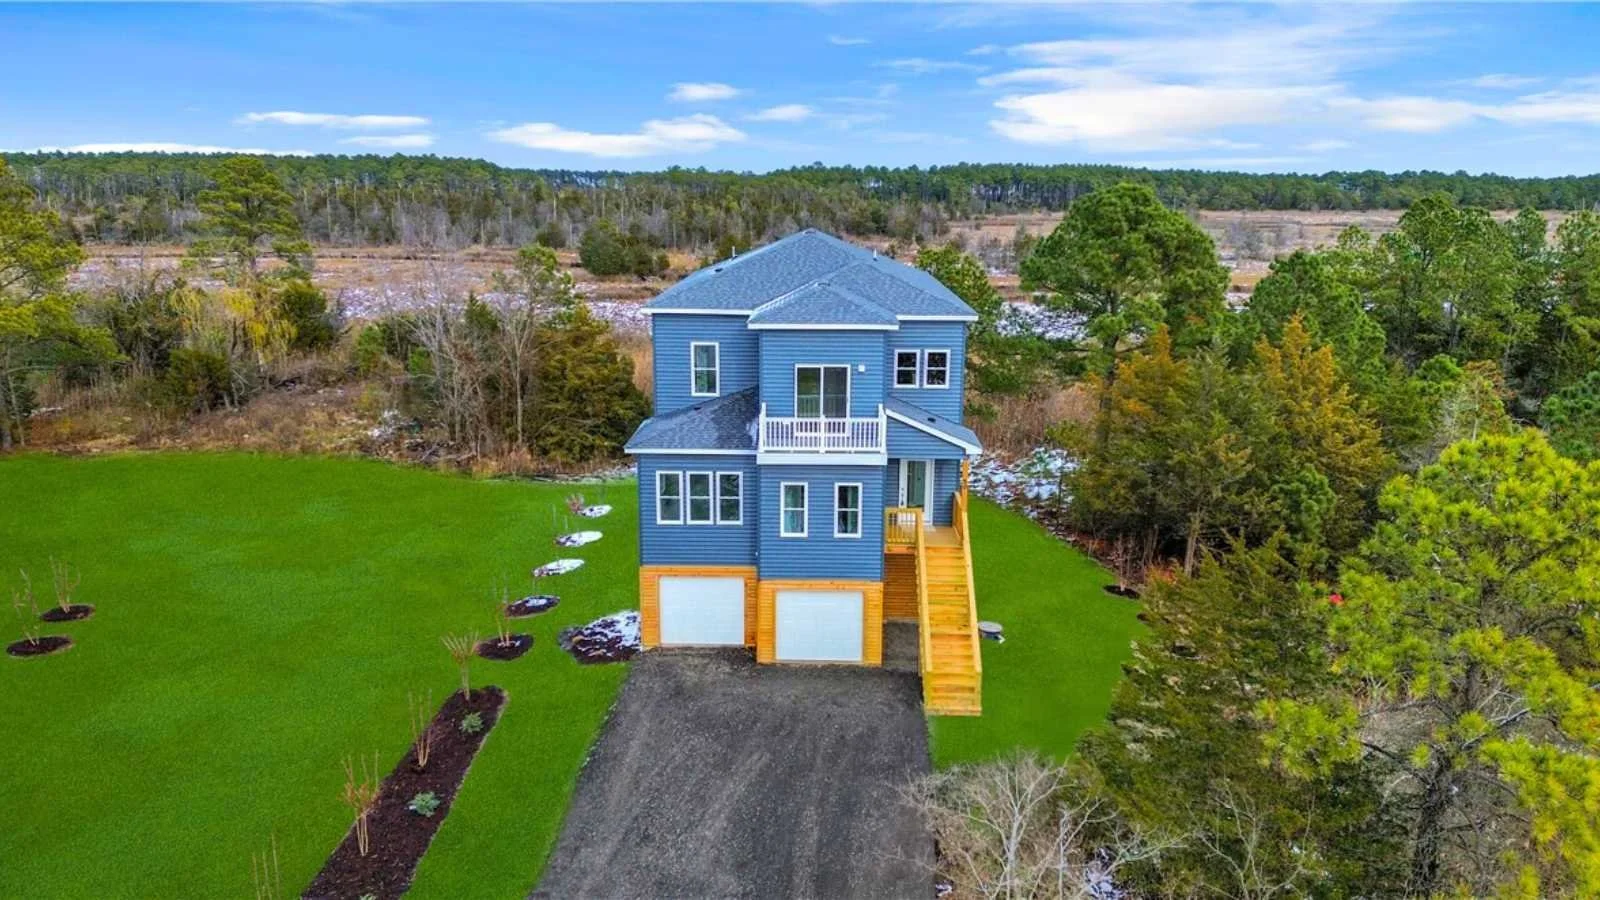
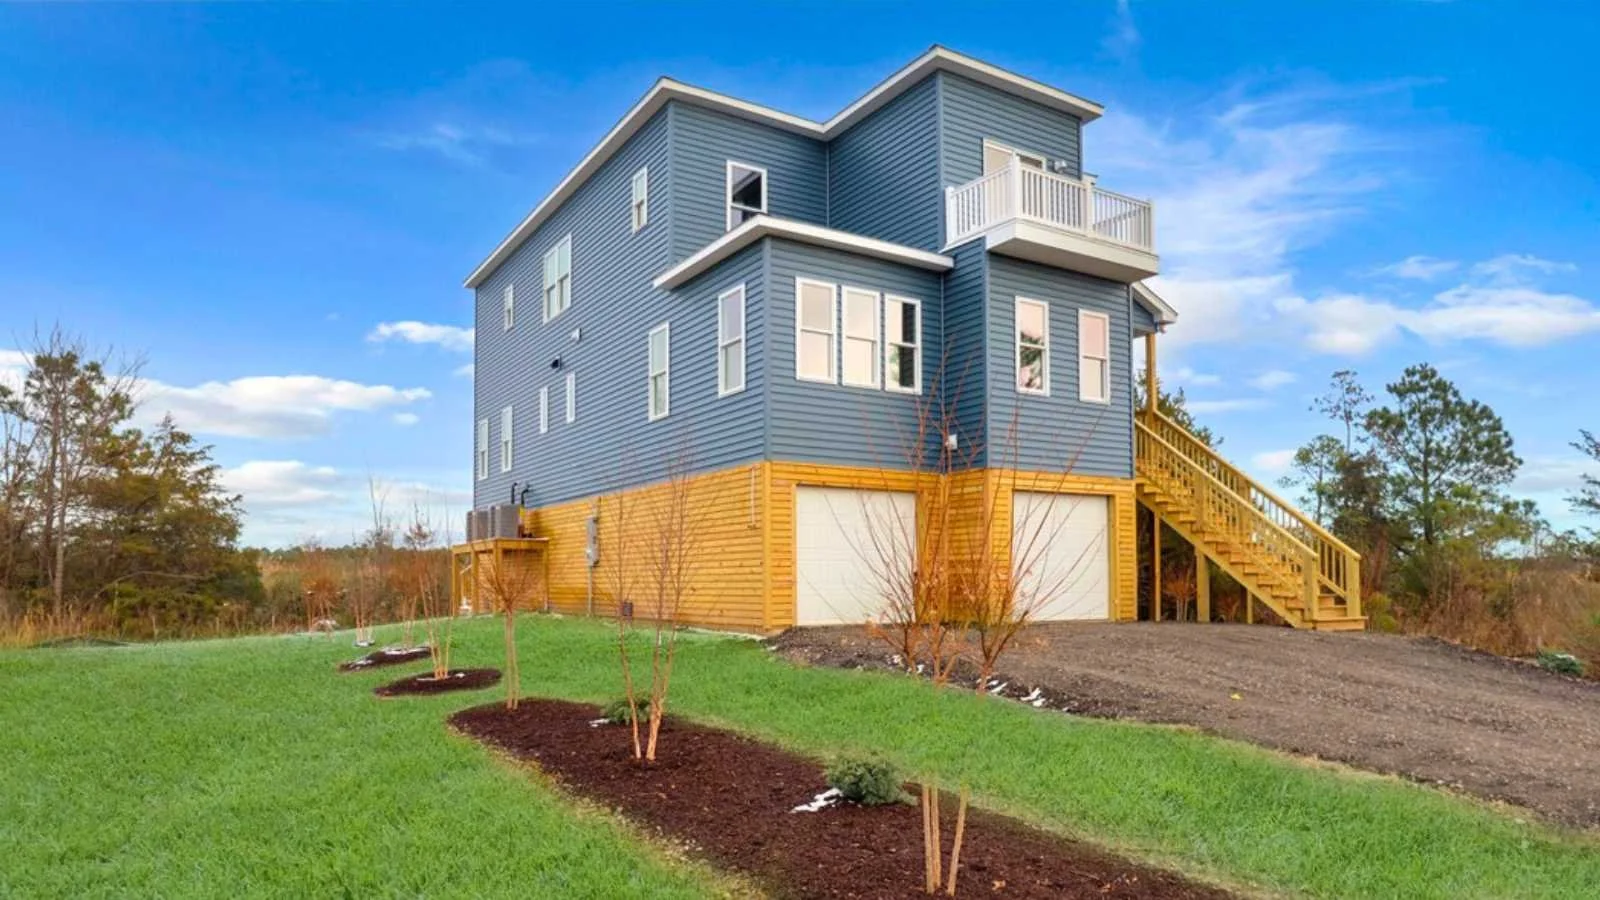
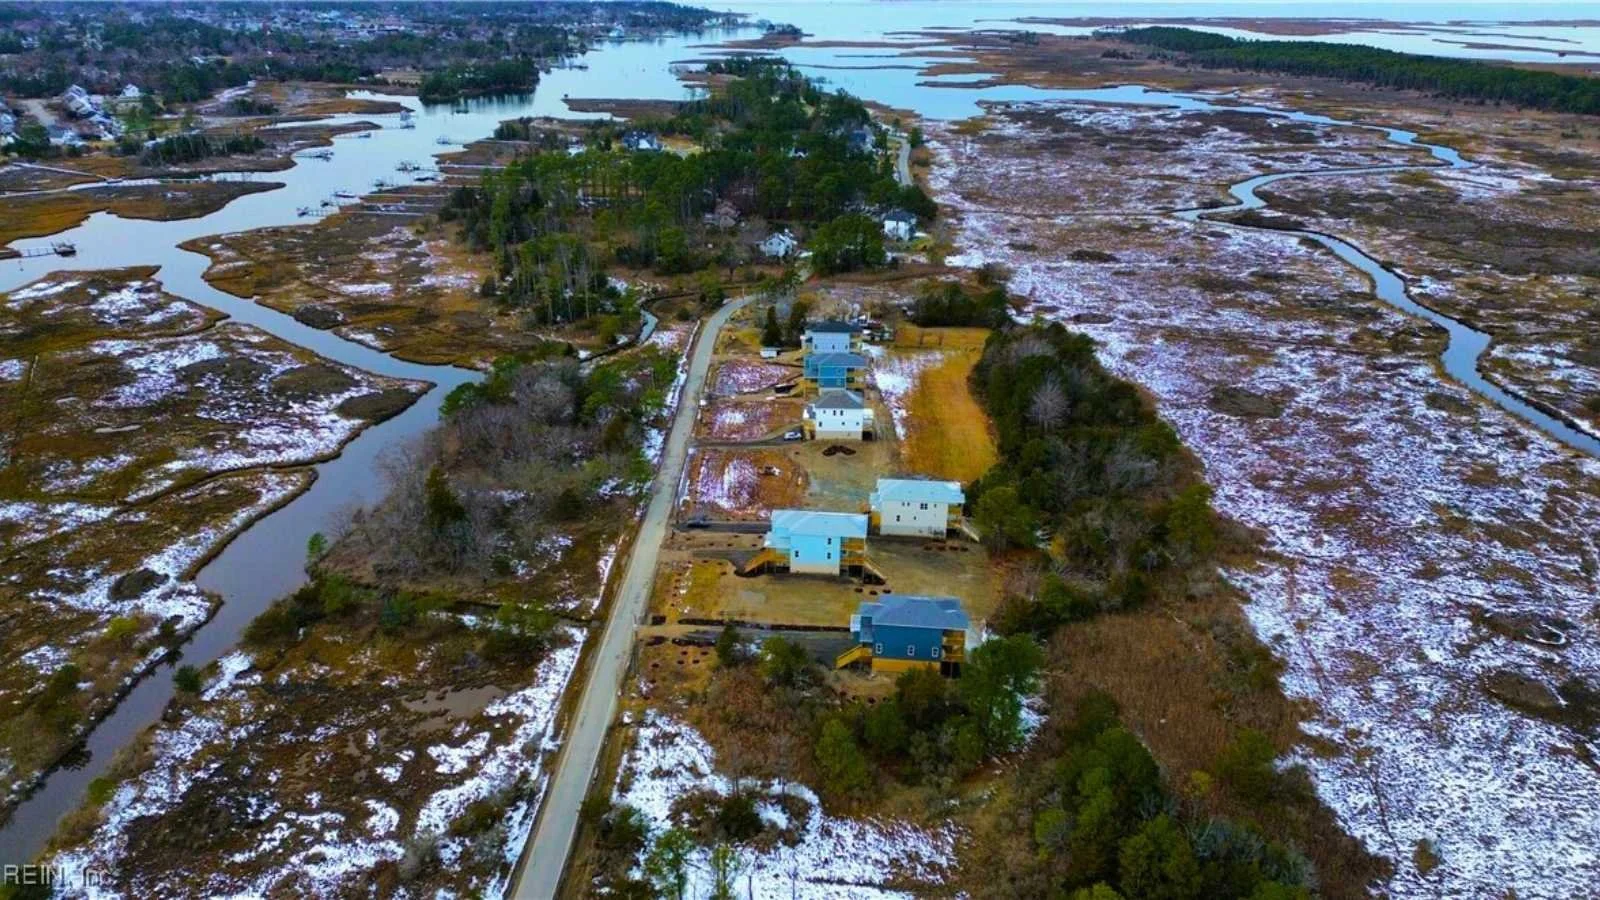
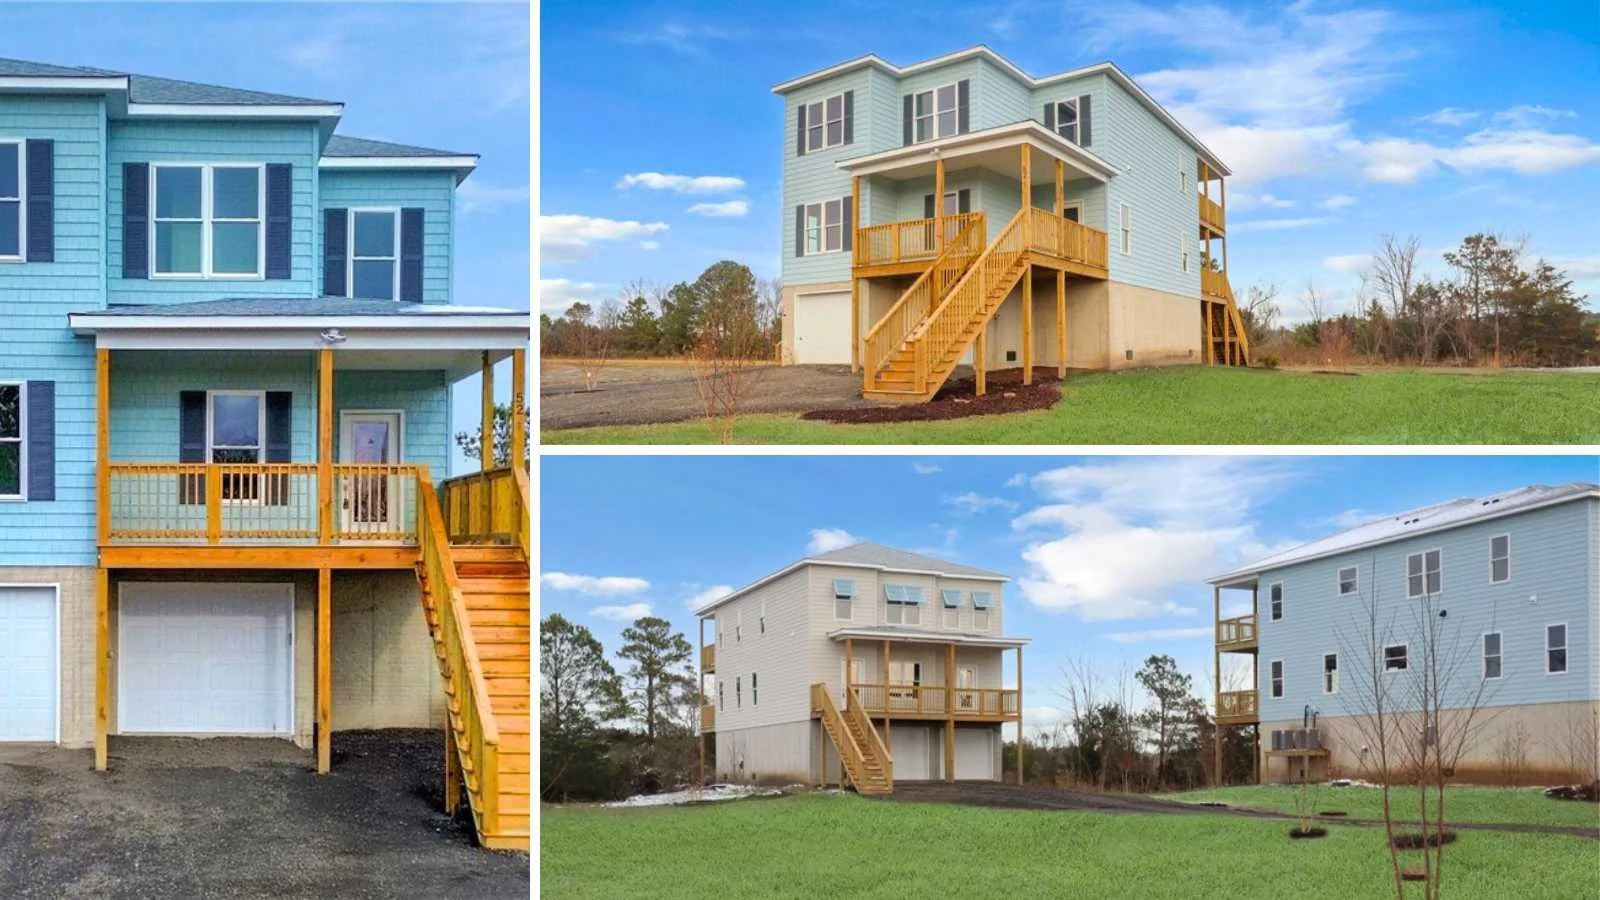
Raised Coastal And Waterfront Homes Built By Almond Exteriors
Three-level homes with living space set well above grade, oversized garages and storage on the ground level, and decks built for the view. This is the style Almond Exteriors is known for along the water on the Virginia Peninsula.
Tap any photo to view it larger.
A Coastal Virginia Custom Home Builder Since 2000
Almond Exteriors started in 2000 with a straightforward standard: build homes the right way and keep the relationship strong after the keys change hands. More than two decades later, the company has built coastal, traditional, contemporary, and luxury waterfront homes across the Peninsula.
No two homes come from a production plan. Clients can start from an existing floor plan and customize it, or work with an architect on a fully custom design. Either way, the design is adapted to the specific lot, including waterfront, raised, and flood-zone requirements.
Almond Exteriors also develops land and builds on pre-developed sites, so clients can come in with a lot, without one, or with a site that still needs work.
Not every client needs a new house. Almond Exteriors also remodels existing homes and builds home additions for homeowners who want more from the house they already own.
What Almond Exteriors Clients Mention Most
- Clear, steady communication from the first meeting through move-in
- A team that answers questions quickly and knows the work
- Close attention to detail on exteriors, outdoor spaces, and full builds
- Design preferences and material choices respected without pushback
- Crews that protect the property and clean up after themselves
- Work finished on schedule
The Almond Exteriors Build Process, With Your Construction Loan Built In
Almond Exteriors runs five stages from first meeting to move-in. The financing steps fit inside them, so the plans, the budget, and the loan all describe the same home.
- Financing
Check Eligibility With Ilonka Avila
Before the design is final, Ilonka reviews which structure fits: One-Time Close, Two-Time Close, or our Hybrid Construction Loan, and how much land equity counts toward the down payment.
- Almond Exteriors
Initial Consultation
Project goals, land details, budget range, and timeline are reviewed up front, so expectations are set early and communication starts clear.
- Almond Exteriors
Design And Planning
Choose or customize a floor plan, settle architectural details, and address site conditions, elevation needs, and local requirements. The finished plans, specs, and build contract go to underwriting and to an independent appraiser.
- Close And Build
Site Work And Construction
The loan closes, then land development, foundation, framing, and structural work begin. Each draw is released after a third-party inspection confirms the work, and our bank funds every draw in-house.
- Almond Exteriors
Interior And Exterior Finishes
Finishes, materials, and exterior details are completed to match the approved design, with durability on the coast in mind.
- Completion
Final Walkthrough And Permanent Loan
Almond Exteriors walks the home with you and closes out final items. The loan then moves to its permanent phase: automatically on a One-Time Close, or with the permanent rate set at completion on a Two-Time Close or Hybrid.
Custom Home Builder In Hampton, Newport News, Poquoson, And York County
Almond Exteriors takes on eight kinds of residential projects, from new waterfront homes to remodels and additions. Naming yours points to the right loan quickly.
Raised Waterfront Homes
Multi-level homes set above flood elevation, with decks and living areas oriented to the water.
How It Can Be FinancedOne-Time Close, Hybrid, or Two-Time Close construction, including jumbo up to $4.5MHomes On Your Own Lot
Custom homes built on land the client already owns, on the water or off it.
How It Can Be FinancedConstruction loan with land equity applied toward the down paymentHomes In Developments
Custom builds inside approved subdivisions and established neighborhoods.
How It Can Be FinancedConventional, FHA, VA, ITIN, or jumbo constructionLand Development And Prepared Sites
Almond Exteriors develops land and builds on pre-developed sites for clients who need the site ready first.
How It Can Be FinancedSite work written into the build contract can be part of the loanMulti-Level Homes With Large Garages
Luxury residences with oversized garages and storage on the ground level.
How It Can Be FinancedPrimary residence, second home, or investment constructionExisting Plan Or Architect-Led Design
Start from an existing floor plan and customize it, or design from scratch with an architect.
How It Can Be FinancedThe final plans and specs set the loan amount and the appraisalRemodels
Remodeling work on existing homes for owners who want to update the house they already have.
How It Can Be FinancedJumbo Renovation, FHA 203K, FNMA HomeStyle, VA Renovation, or a 2nd lienHome Additions
Added living space on an existing home, planned and built by the same team that builds new homes.
How It Can Be Financed2nd Mortgage Construction-to-Permanent that keeps your first mortgage rateBuilding in a flood zone? When a lot sits in a FEMA special flood hazard area, flood insurance is required on the loan. Raised construction is how coastal builders like Almond Exteriors work with those requirements, so bring the lot address to your first call with Ilonka and both sides can plan for it from the start.
New Beachfront Home For Sale On The Chesapeake Bay In Seaford, Virginia
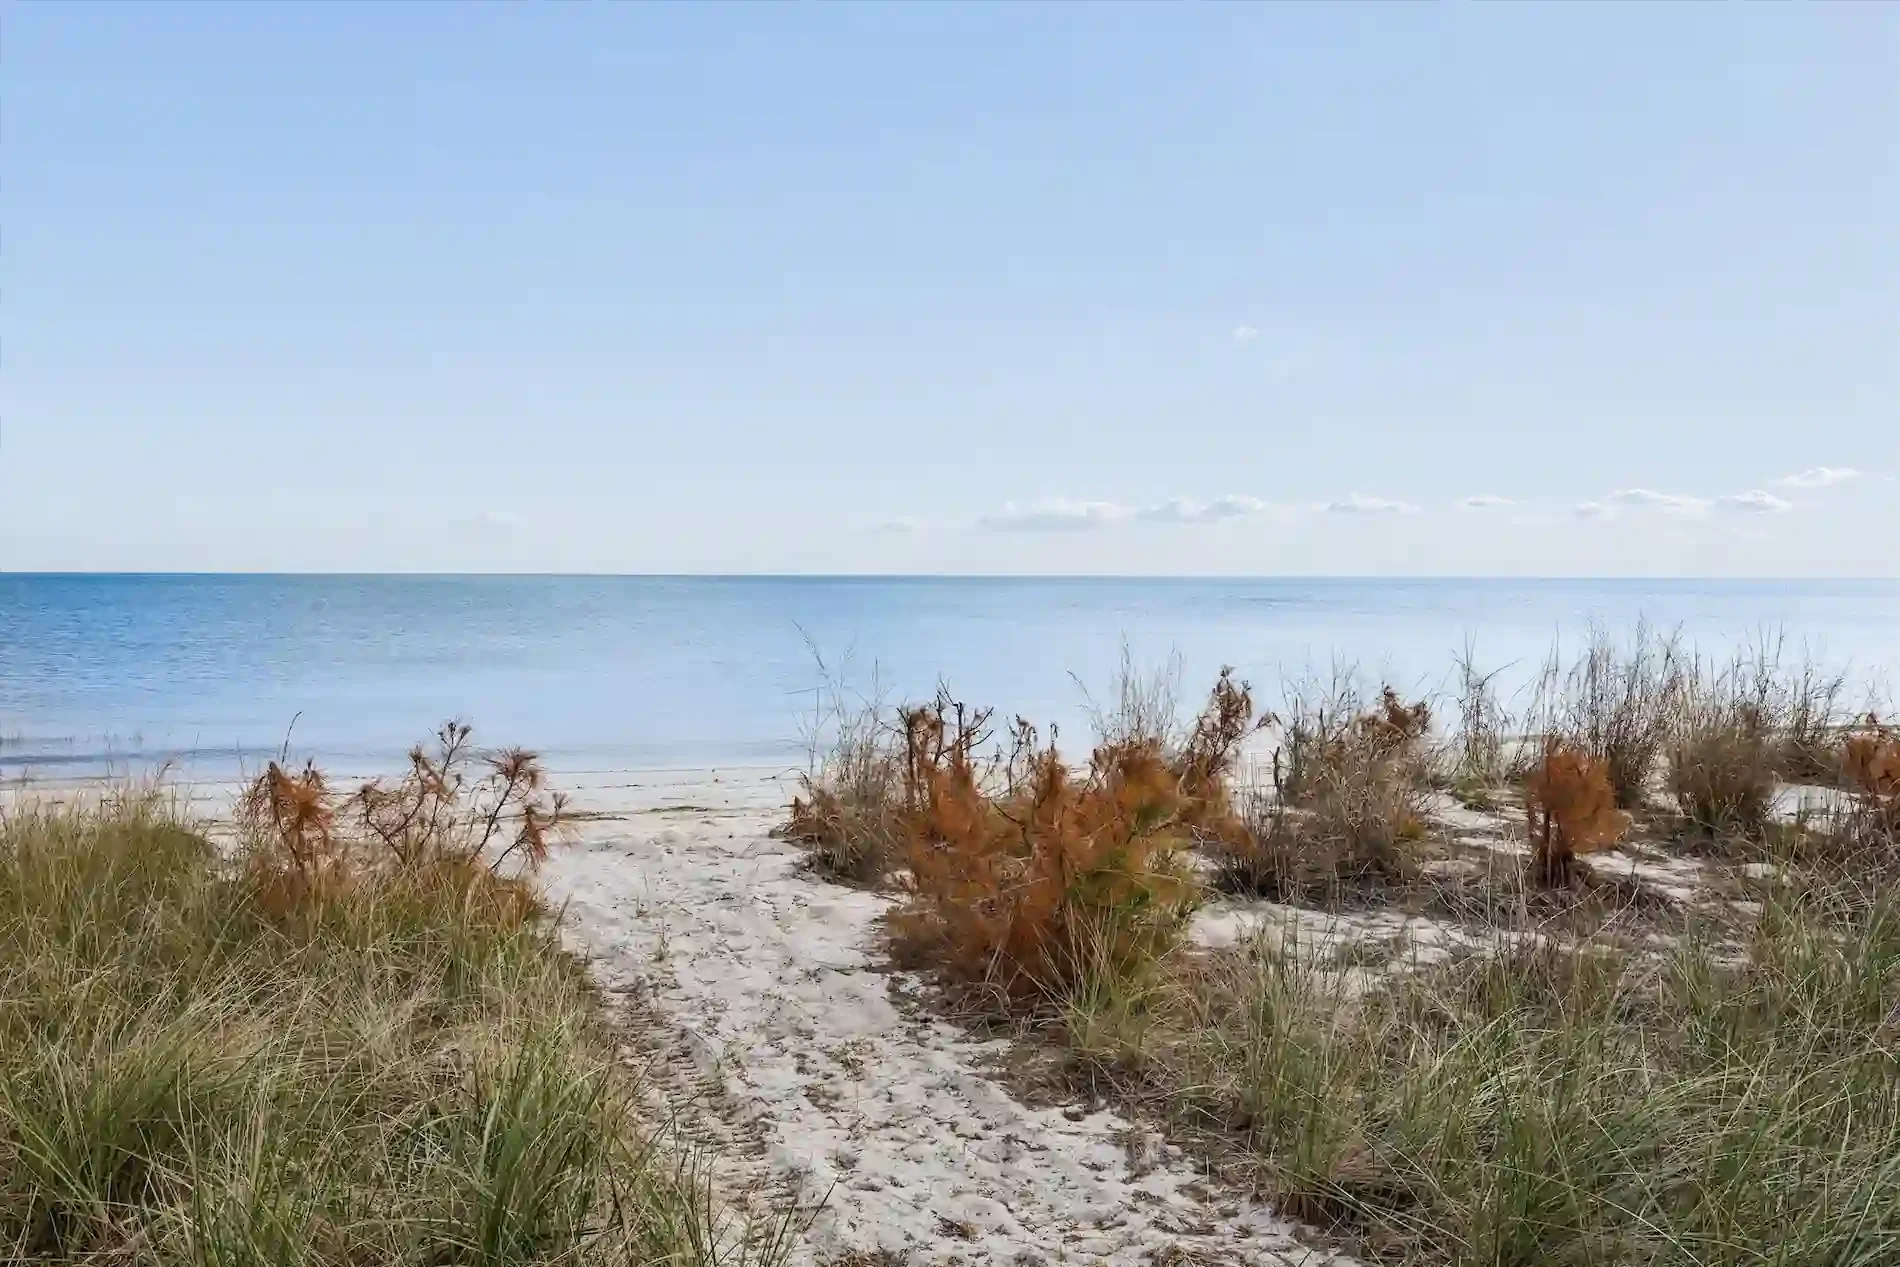
Almond Exteriors has finished a brand-new beachfront home at 1015 Bay Tree Beach Rd. in Seaford, in York County. It sits on 1 acre directly on the Chesapeake Bay, with a private sandy path from the backyard to the beach and sunrise views over the water.
The builder describes the setting as resort living every day: dolphins along the shoreline, sailboats passing, and a backyard designed for entertaining from morning coffee to evenings by the pool.

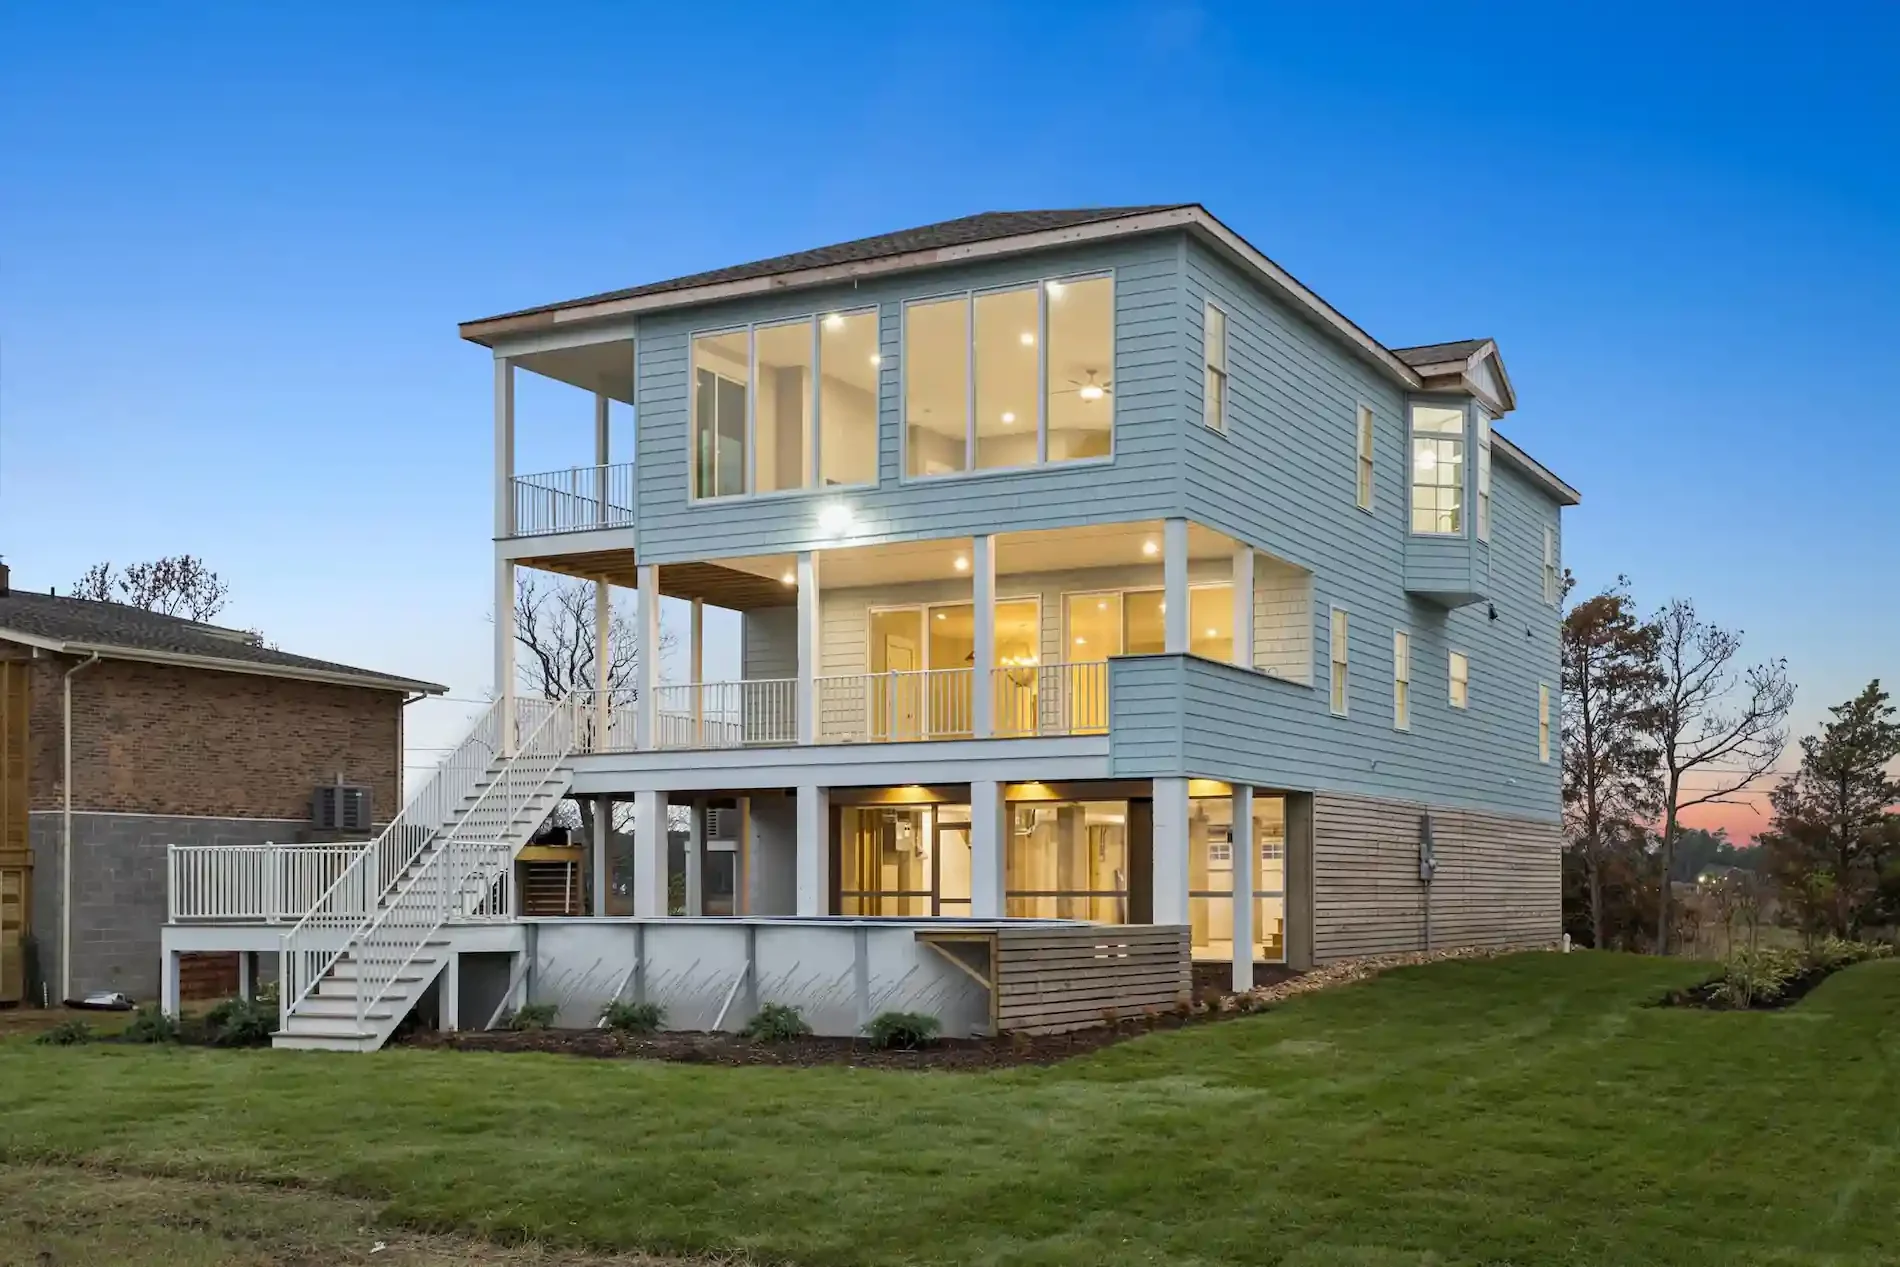

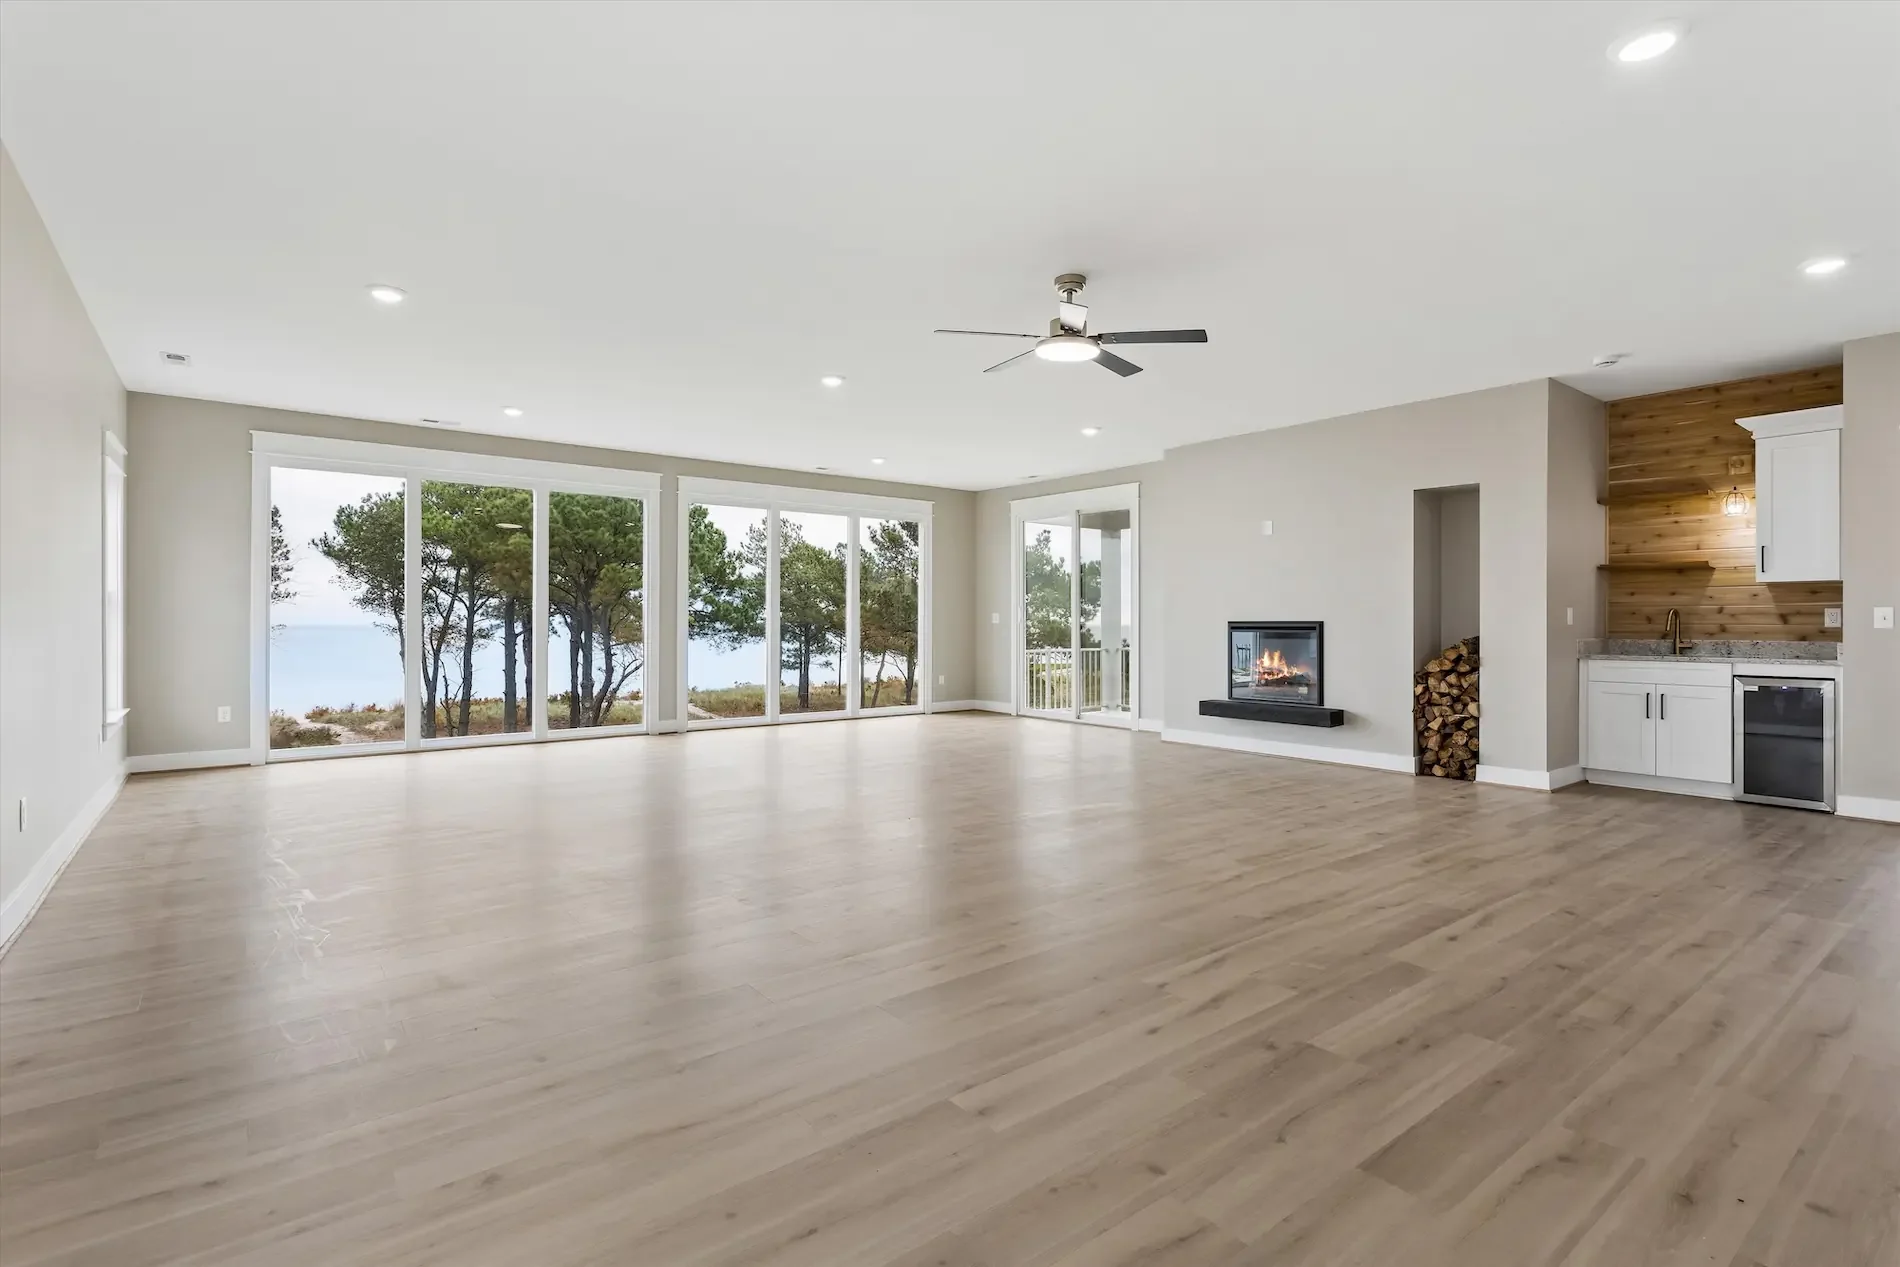

Home Highlights
- Direct beach access on the Chesapeake Bay, with sunrise views
- Resort-style pool with a swim-up bar
- Outdoor kitchen for poolside entertaining
- Private elevator and a whole-home generator
- Butler's pantry and a dedicated coffee bar
- Hidden rooms and upgrades throughout, per the builder
How You Can Finance This Home
This home is finished, so it is bought with a purchase loan, not a construction loan. Depending on the loan amount and how you will use the home, that can be Conventional, FHA, VA, or jumbo purchase financing up to $10 million, in qualifying scenarios.
Eligible veterans with full entitlement may qualify for up to 100% financing on a primary residence, and up to *$50,000 extra is available to qualified buyers.
Commission savings note: buying this home from Almond Exteriors is a new-home purchase from a registered builder, so the up to 30% commission savings does not apply to it. It can apply to selling the home you live in now.
Property details are provided by Almond Exteriors and are subject to change, errors, and prior sale. Financing is subject to credit qualification, appraisal, property eligibility, occupancy, and program guidelines. Rates and terms vary and are not guaranteed. Equal Housing Lender.
Virginia Construction Loans From A Direct Lender, Built For Custom Homes
BuildBuyRefi.com is powered by The Federal Savings Bank, an FDIC-insured, veteran-owned direct lender licensed in all 50 states, NMLS #411500. Every construction loan for an Almond Exteriors home is originated, underwritten, funded, and drawn in-house, from the first conversation to the final inspection.
Three Ways To Structure The Loan
One Closing, Terms Set Early
Qualify and close once. The permanent terms are set at that closing, and the loan converts when the home is finished with no second appraisal and no re-qualification.
Rate Set When The Home Is Done
A construction loan first, then a separate permanent loan at completion, so your permanent rate is chosen when the build is finished. FHA and VA permanent loans can be streamlined in qualifying scenarios.
Single-Close Feel, Rate Stays Open
Built in-house. Both document sets are prepared upfront, so it runs like one closing with one set of fees while the permanent rate stays flexible until completion. FHA and VA streamline eligible in qualifying scenarios. Brokers and correspondents cannot offer it.
Program Details At A Glance
- Conventional, FHA, and VA minimum score
- 640
- VA construction, eligible veterans
- Up to 100%
- VA loan size
- $1.5M, up to $3M by exception
- Jumbo construction loan amount
- Up to $4.5M
- Jumbo minimum score
- 720
- ITIN construction minimum score
- 680
- Investment construction, 1 to 4 units
- 680 to 700
- Second home construction
- Available
- Administrative fees
- None
Jumbo amounts above $2.5M go to Credit Committee review. Investment score minimums depend on loan-to-value. Credit, occupancy, and property type determine final eligibility.
Zero Down When You Own The Land
For borrowers who are not using VA, land equity is the path to zero down. A lot you own, or buy at closing, can be applied toward the down payment, and in qualifying scenarios it can cover the down payment entirely.
VA Construction For Hampton Roads Veterans
Hampton Roads is home to one of the largest military communities in the country. Eligible veterans with full entitlement can build with Almond Exteriors with up to 100% financing and no monthly mortgage insurance, through our Hybrid or Two-Time Close structures.
A Direct Lender, Not A Broker
A broker hands your file to someone else. A correspondent closes the loan and sells it. We keep it. There are no administrative fees on our construction programs, while fee layers of $40,000 to $100,000 or more show up on many broker and correspondent construction loans. Ask for every fee line by line on any quote you compare.
All programs are subject to credit qualification, property eligibility, reserve requirements, and applicable program guidelines. Rates, terms, and availability vary by borrower, property, occupancy, and loan amount, and are not guaranteed. Appraisals are performed by independent licensed appraisers and construction inspections by third-party inspectors. Contact your banker for applicable rates, terms, and conditions.
Primary, Second Home, Investment, Multi-Family, And Jumbo Construction Loans
Most construction lenders stop at a primary residence within conforming limits. We finance an Almond Exteriors home however you plan to use it, and Ilonka matches each occupancy type to the One-Time Close, Hybrid, or Two-Time Close structure it qualifies for.
The Home You Live In
Conventional, FHA, and VA construction with a 640 minimum score. VA builds with up to 100% financing run through our Hybrid or Two-Time Close.
StructuresOne-Time Close, Hybrid, Two-Time CloseA Vacation Home On The Bay
Build a weekend or vacation home on the water through our Conventional and Jumbo programs. FHA and VA do not cover second homes, and higher credit minimums apply.
StructuresConventional, plus Jumbo Two-Time CloseA Rental Built From The Ground Up
New 1 to 4 unit site-built rentals. A 700 score allows up to 75% loan-to-value, or 680 up to 70%. Rental income from the home being built cannot be used to qualify.
StructureTwo-Time Close investment constructionDuplexes And 2 To 4 Units
An owner-occupied duplex, or a 2 to 4 unit building as an investment. Larger multi-unit residential buildings and subdivisions are reviewed case by case.
StructuresMatched to occupancy and unit countWaterfront Builds Up To $4.5 Million
A 720 minimum score. The Jumbo One-Time Close covers primary residences with up to 18 months interest-only. The Jumbo Two-Time Close covers primary and second homes, with a no-cost 6-month extension when requested in advance.
StructuresJumbo One-Time Close, Jumbo Two-Time CloseNo Social Security Number Needed
Ground-up primary residence construction for borrowers who file taxes with an ITIN, with a 680 minimum score and no private mortgage insurance.
StructureOne-Time CloseProgram availability depends on occupancy, property type, unit count, loan amount, and credit. Jumbo amounts above $2.5 million require Credit Committee review, and reserve requirements increase with loan size. Investment construction is limited to 1 to 4 unit site-built properties. All programs are subject to credit qualification and program guidelines, and rates and terms are not guaranteed.
*$50,000
Extra Funds For What A Coastal Build Contract Leaves Out
Qualified borrowers can access up to $50,000 in separate, unsecured funds before, at, or after closing, underwritten in-house at the same time as the mortgage. It does not draw on your equity and does not change your loan-to-value. We are not aware of another lender in this space offering it.
How Almond Exteriors Clients Could Use It
Furnishing three levels
A multi-level coastal home has more rooms, decks, and porches to furnish than most first budgets plan for.
Storm prep and window treatments
Shutters, blinds, and coverings that usually land after closing, when the construction budget is already spent.
Finish upgrades decided late
The tile, fixtures, or lighting you fall for after the contract is signed and the allowance is set.
Landscaping and outdoor living
Plantings, patio furniture, or an outdoor kitchen added after the first season near the water.
A cushion for change orders
Funds already approved keep a mid-build decision from stalling the schedule while it is priced.
Consolidating debt to qualify
Paying down revolving balances can lower your debt-to-income ratio, which in some scenarios helps you qualify for the loan size the home needs.
*Up to $50,000 is available to qualified borrowers and can be applied across our loan programs. This is a separate unsecured consumer loan underwritten in-house at the same time as the mortgage. Proceeds cannot be used for a down payment. Approval, amount, rates, and terms depend on credit qualification and are not guaranteed. Contact your banker for applicable rates, terms, and conditions.
Building On The Water In Hampton Roads: What Underwriting Looks At
A waterfront or raised home is financed the same way as any custom build. A few items simply deserve attention earlier, and knowing them up front keeps the plan, the budget, and the loan in line.
Flood Zone And Insurance
If the lot is in a FEMA special flood hazard area, flood insurance is required on the loan. An elevation certificate is often needed to price it.
Foundation And Elevation Costs
Raised foundations cost more than a standard slab. Written into the build contract, that cost belongs in the construction loan.
An Independent Appraisal
An independent appraiser values the home from the land, plans, and specs, using comparable sales. We have no influence over the value.
Waterfront Lot Equity
A waterfront lot you already own can carry real equity, which can be applied toward the down payment in qualifying scenarios.
Flood insurance requirements depend on the property's FEMA flood zone designation and lender guidelines. Appraised value is determined by an independent licensed appraiser. Financing is subject to credit qualification and program guidelines.
What We Can And Cannot Finance With Almond Exteriors
Almond Exteriors builds custom homes, which sits squarely inside what our bank finances. The limits below are general program rules that apply to every builder in our network.
What We Can Finance
- Custom site-built homes as a primary residence, second home, or investment property (1 to 4 units)
- Raised and waterfront homes, including foundation and elevation work written into the build contract
- Homes on land you own or buy at closing, with land equity applied
- Builds in developments and on developed or pre-developed sites
- Jumbo construction up to $4.5 million, case by case
- Owner-occupied duplex construction, and 2 to 4 unit investment construction
- Remodels and home additions, through first lien renovation loans or a 2nd lien that keeps your first mortgage
- Tearing down an existing home and rebuilding on the same lot
- Pools written into the build contract when the appraisal supports them
What We Cannot Finance
- Self-build or owner-as-contractor projects of any kind
- Work left out of the build contract, which cannot be added to the construction loan after closing
- Homes under 400 square feet, unless approved case by case
- Stand-alone barns, and retail, office, or other commercial buildings
- Land titled to someone else that is not being transferred to the borrower
Underwriting looks at the full cost to build, including hard costs, soft costs, land, and closing costs. When Almond Exteriors writes site work, elevation, and finishes into one contract, underwriting has one complete budget to review.
The appraisal is completed by an independent appraiser from the land, plans, and specifications, and we have no influence over the value. Anything you want financed belongs in the contract before closing.
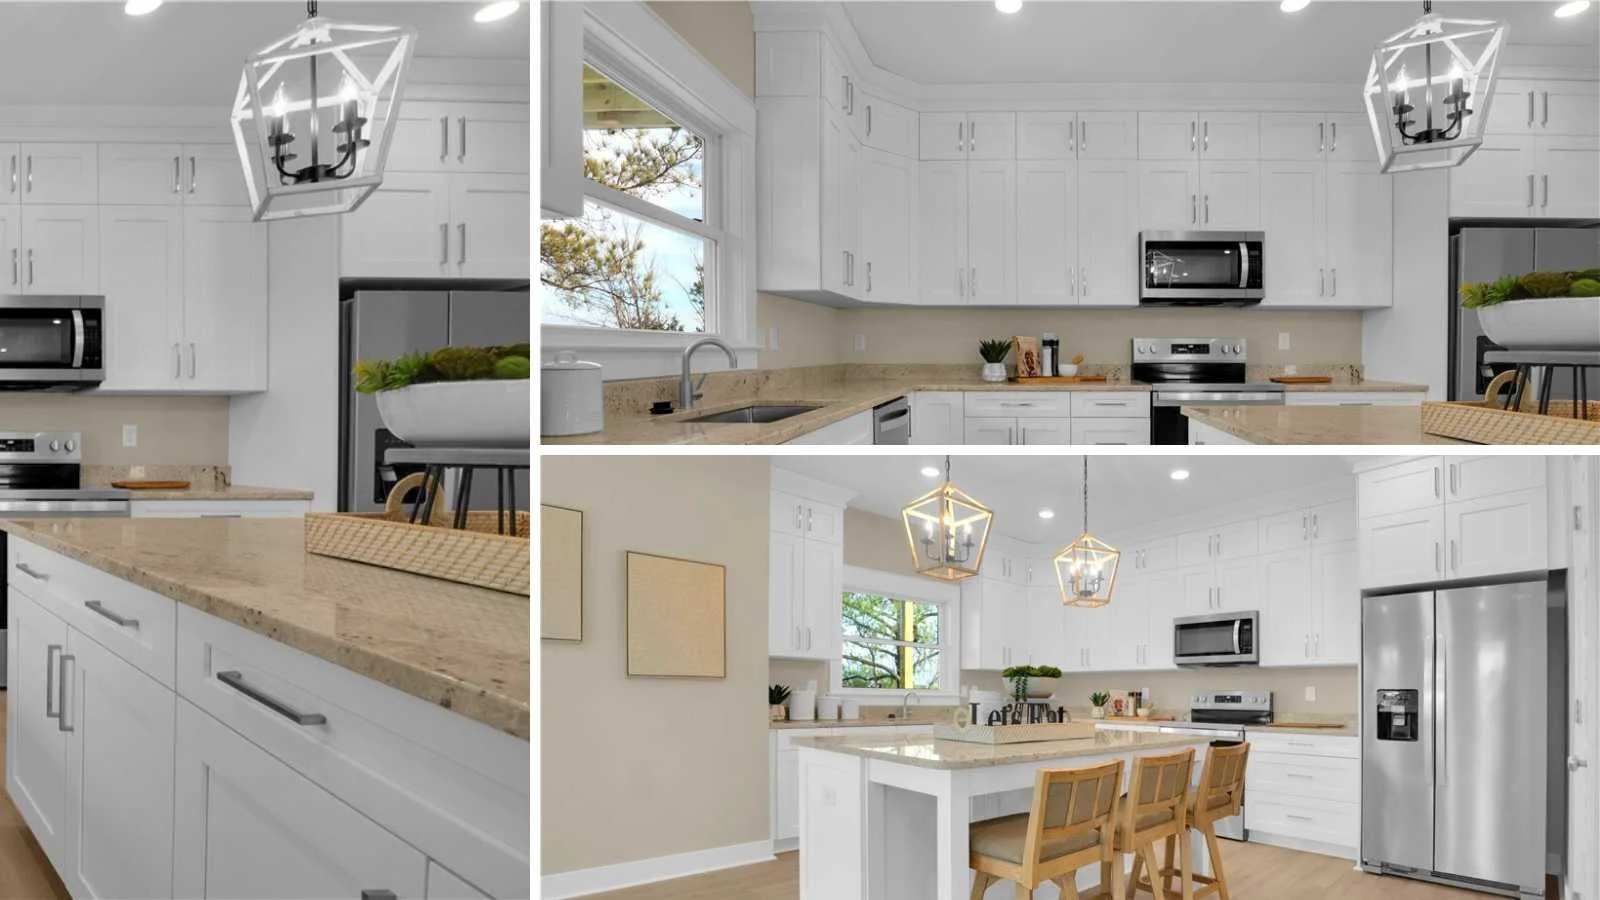
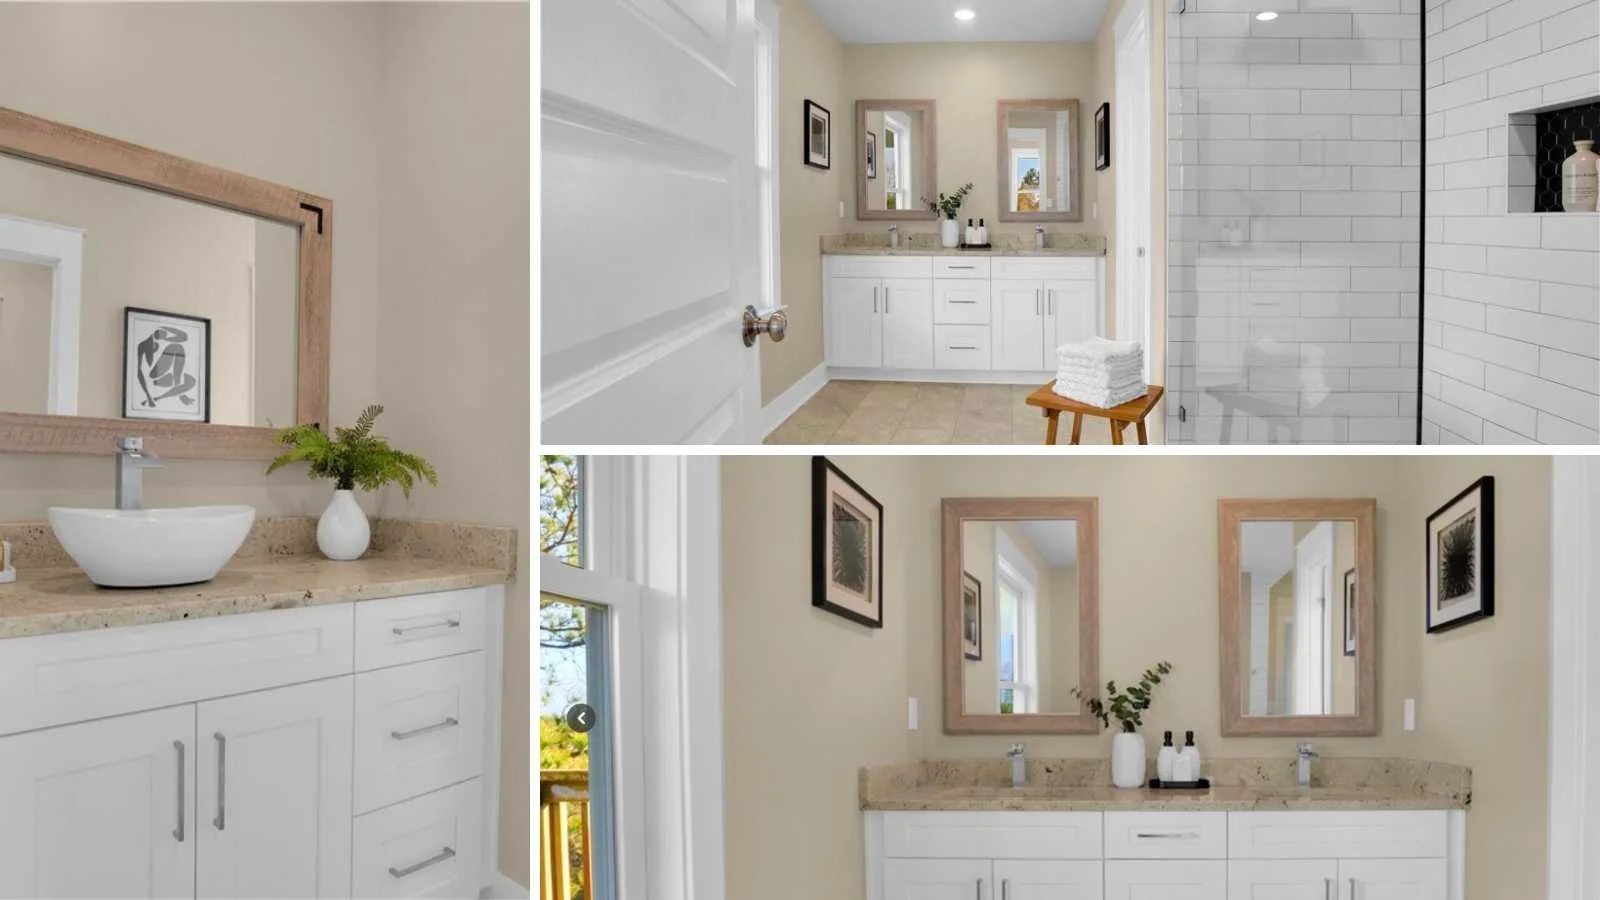
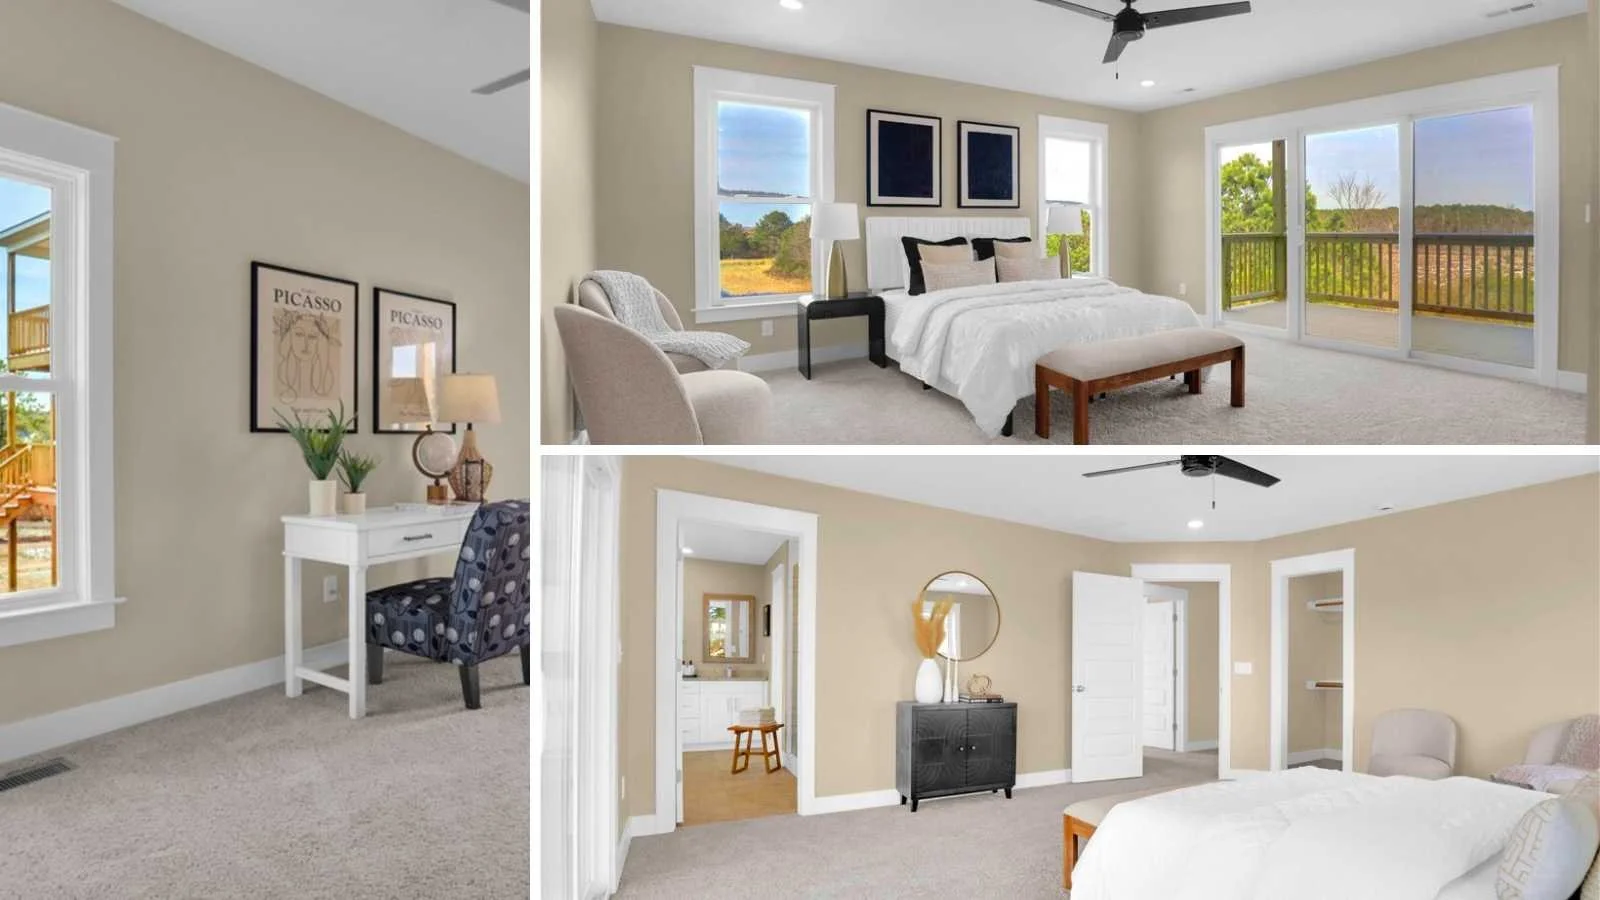
Kitchens, Baths, And Bedrooms Finished By Almond Exteriors
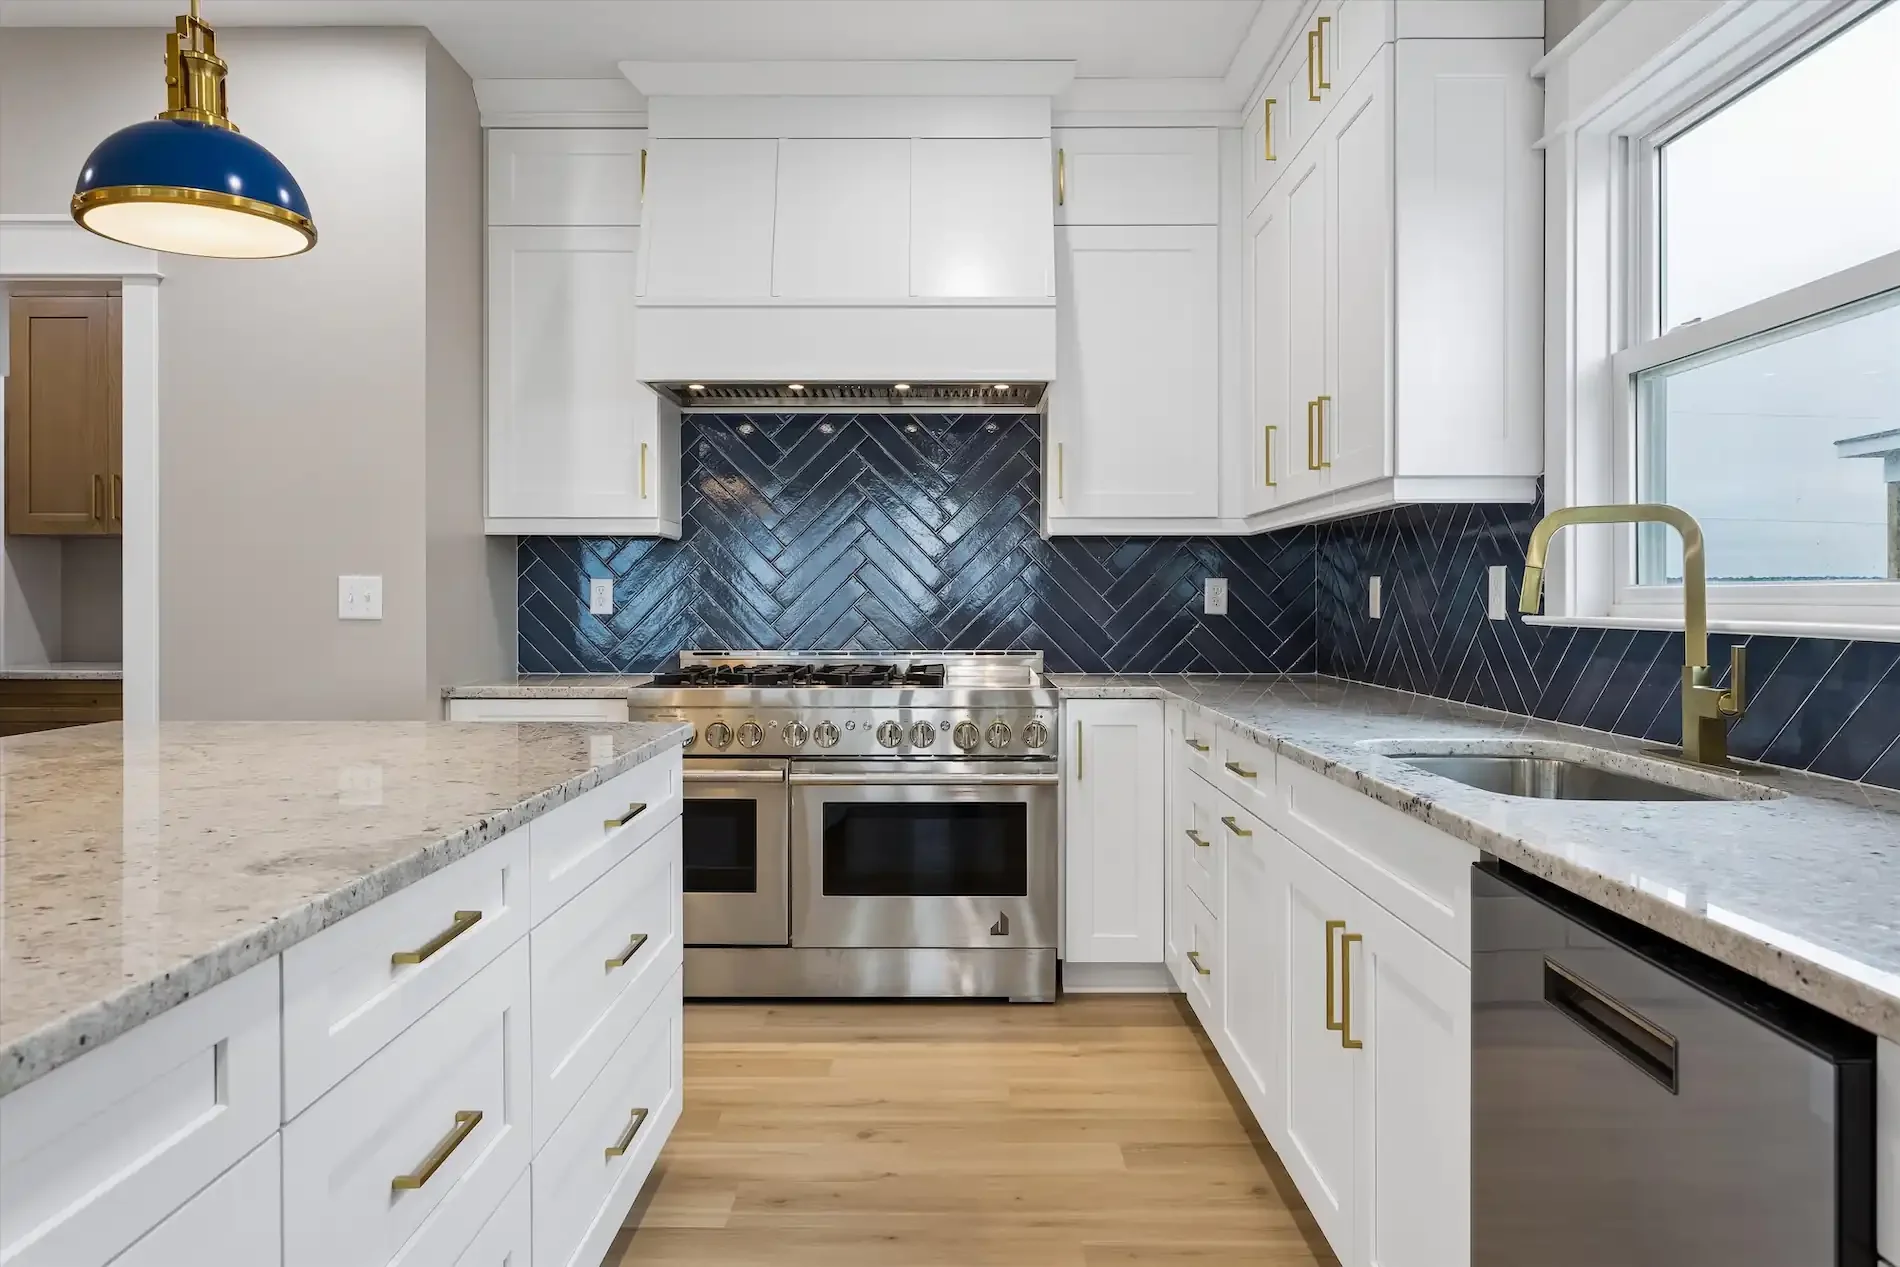
Kitchens with breakfast-bar islands, pendant lighting, granite counters, and white shaker cabinets. Primary suites with tiled walk-in showers and dual vanities. Bedrooms with private decks and room for a home office.
Remodel Or Add On With Almond Exteriors Without Refinancing Your Home
Almond Exteriors remodels existing homes and builds home additions across Hampton Roads. If you already own your home and like your mortgage rate, a 2nd lien construction loan pays for the work without touching your first mortgage. If you are buying a home to remodel or refinancing anyway, a first lien renovation loan rolls it all into one.
2nd Mortgage Construction-To-Permanent
Many homeowners locked first mortgage rates between 2.5 and 4.0 percent in 2020 and 2021. A cash-out refinance would trade that rate on the entire balance, which can cost more over time than the project itself.
Our 2nd lien construction loan funds the project in inspected draws, then converts to a fixed-rate, closed-end second lien. Only the new money carries a new rate. There is no set maximum; each project is reviewed case by case.
Renovation Loans On A Purchase Or Refinance
Buying a home to expand, or refinancing anyway? FHA 203K, FNMA HomeStyle, and VA Renovation roll the project into one first mortgage, and our Jumbo Renovation program goes up to $2.5 million on a first lien, higher with Loan Committee approval.
Ilonka Avila is an FHA 203K Specialist and VA Renovation Specialist and can compare these side by side with the 2nd lien option.
Projects These Loans Fit
In-Law Or Guest Suites
A private suite with its own bath for a parent, an adult child, or long-term guests.
Second-Story Additions
More bedrooms and better views without giving up yard space on a tight lot.
Garages With Living Space Above
A large garage with a bonus room, office, or apartment on the floor above.
ADUs On Land You Own
A detached unit of at least 400 square feet, permanently affixed, for family or rental use.
Primary Suite Additions
A new primary bedroom with a walk-in closet and a full bath with a tiled shower.
Kitchen And Bath Remodels
Opened walls, new islands, and updated baths on a home you plan to keep.
Subject to credit qualification, property eligibility, lien position, available equity, appraisal, and applicable program guidelines. Loan amounts above standard program limits require Loan Committee approval. Rates and terms vary by borrower and property and are not guaranteed. Local zoning and permitting govern what may be built on any property. Contact your banker for applicable rates, terms, and conditions.
Save Up To 30% On Real Estate Commissions When You Sell A Home Or Buy A Lot
Building with Almond Exteriors often comes with another transaction: a current home to sell, or a waterfront lot to buy first. Qualified borrowers can save up to 30% on real estate commissions on those transactions through our participating agent network in all 50 states, applied as a closing cost credit or toward a rate buy-down.
Selling Your Current Home
Moving into a new custom home usually means selling the one you live in now. A share of that commission back is real money at closing.
Buying An Agent-Listed Lot
Buying a waterfront or in-town lot listed with an agent? The network can represent that purchase, and the savings apply there too.
Credit Or Rate Buy-Down
Take the savings as a credit toward closing costs or put it toward a lower rate. Ilonka can run both and show which helps more.
What this covers and what it does not. The benefit applies only to agent-represented transactions: selling an existing home, buying an existing listed home, or buying land listed with an agent. It does not apply to building a home with Almond Exteriors or to buying a finished home directly from them. Those are direct agreements with a registered builder, with no commission involved.
No money changes hands between us and the agents in either direction. We do not pay them, they do not pay us, and we earn nothing when a borrower uses one. Paying or receiving fees for referrals of federally related mortgage loans is prohibited by law, and we do not do it.
Commission savings are available to qualified borrowers through a participating real estate agent network, subject to agent availability, program terms, and applicable state law. Savings apply to the fee received by the participating brokerage representing the borrower and are applied toward closing costs. Actual savings vary by property, sale price, and agreement. This benefit does not apply to the direct purchase or construction of a new home from a builder. No referral, affiliate, or other fee is paid or received by BuildBuyRefi.com or The Federal Savings Bank in connection with this benefit.
Meet Ilonka Avila, The Banker Assigned To Almond Exteriors Clients
Ilonka Avila
Top Rated® National Vice President
BuildBuyRefi.com, powered by The Federal Savings Bank | NMLS ID# 47252
Ilonka Avila is a U.S. Air Force veteran who went straight from active duty into the mortgage industry, and she has more than 35 years of mortgage experience. She is the assigned banker for Almond Exteriors clients, and because our bank lends in all 50 states, she works with buyers already in Hampton Roads and with families relocating to the Peninsula.
Her first goal with every client is a strong working relationship and a process that stays transparent from start to finish, whether you are building for the first time or adding on to a home you have owned for years.
Her designations line up with how Almond Exteriors clients build. New Construction and Construction Loan Specialist covers ground-up custom homes on the water and off it. Veteran Lending Specialist matters in a region with a military community this large, and she has worn the uniform herself. FHA 203K and VA Renovation Specialist cover remodels and additions on a home you already own.
Away from work, Ilonka hits the gym and does CrossFit, loves to cook, and cheers on her favorite college football team. With longer time off, she plans to get back into traveling and scuba diving.
What Ilonka handles for an Almond Exteriors client: choosing between One-Time Close, Two-Time Close, and Hybrid for your build, matching a second home, investment, or multi-family project to the right program, applying lot and land equity, comparing a renovation loan with a 2nd lien on a remodel or addition, and keeping draws in step with the Almond Exteriors schedule. Read Ilonka's full bio.
Seaford · Chesapeake Bay BeachfrontCheck Your Eligibility To Build With Almond Exteriors
A few questions show which programs fit your land, your plans, and your loan size. No credit pull, no Social Security number, and no obligation. Your answers go to Ilonka Avila and to Almond Exteriors.


Schedule A Call With Ilonka Avila
Pick a time that works. Bring your lot address and flood zone if you know it, a rough budget, or the Almond Exteriors plan you are considering, and Ilonka will walk through which programs fit.
Frequently Asked Questions About Almond Exteriors And Construction Loans In Hampton Roads
The questions homeowners ask most before building a custom or waterfront home with Almond Exteriors, answered plainly.
Where does Almond Exteriors build?
Almond Exteriors builds custom homes in Hampton, Newport News, Poquoson, and York County, Virginia, both on and off the water. That includes homes on private lots, in established developments, and on developed or pre-developed sites. Our financing is available in all 50 states, so buyers relocating to Hampton Roads can qualify too.
Can Almond Exteriors build on land I already own?
Yes. Almond Exteriors builds on client-owned land, in approved subdivisions, and on developed or pre-developed property. Land you own can be applied toward the down payment, and in qualifying scenarios the equity can cover it entirely.
Can I finance a waterfront home in a flood zone?
Yes. Raised and waterfront homes are financed under the same construction programs as any custom home. Foundation and elevation work written into the build contract can be part of the loan. If the lot sits in a FEMA special flood hazard area, flood insurance is required, and the home is valued by an independent appraiser.
Are Almond Exteriors floor plans custom or pre-designed?
Both. Clients can start from an existing Almond Exteriors floor plan and customize it, or work with an architect on a fully custom design. Either way, the final plans and specifications are what underwriting and the appraiser review.
Can I build with zero down?
In qualifying scenarios, yes. Eligible veterans with full entitlement can receive up to 100% financing on VA construction. For other borrowers, land equity is the path to zero down: land you own, or buy at closing, can be applied toward the down payment and can cover it entirely when the equity is sufficient.
What credit score do I need for a construction loan?
The minimum is 640 on Conventional, FHA, and VA construction. Jumbo construction requires 720, ITIN construction requires 680, and investment construction requires 680 to 700 depending on loan-to-value. Ilonka Avila can review where you stand before you apply.
Can I finance a remodel or home addition with Almond Exteriors?
Yes. Almond Exteriors remodels existing homes and builds home additions. Our 2nd Mortgage Construction-to-Permanent loan funds the work during construction and converts to a fixed-rate, closed-end second lien when it is done, so your first mortgage keeps its rate and balance, with no set maximum and each project reviewed case by case. If you are buying or refinancing, FHA 203K, FNMA HomeStyle, VA Renovation, and Jumbo Renovation up to $2.5 million on a first lien are also available.
Can I build a second home, investment property, or duplex with Almond Exteriors?
Yes. Second home construction is available through our Conventional and Jumbo programs. Investment construction covers 1 to 4 unit site-built properties through our Two-Time Close, with a 700 score allowing up to 75% loan-to-value. Owner-occupied duplexes are eligible, and larger multi-unit residential projects are reviewed case by case.
Why does it matter that Almond Exteriors is already a registered builder?
A lender with no history with your builder has to collect the builder's financials, review them, and set up its draw process before your loan can move, and many builders are slow to repeat that for a new lender. Almond Exteriors is already registered with our bank, so that work is finished. The only approval left is yours, which improves and speeds up the closing process.
What is the difference between a One-Time Close and a Two-Time Close construction loan?
A One-Time Close sets the permanent terms at a single closing, and the loan converts when the home is finished with no second appraisal or re-qualification. A Two-Time Close uses separate closings, so the permanent rate is set at completion. Our Hybrid Construction Loan sits between them: both document sets are prepared upfront so it runs like one closing, while the permanent rate stays flexible until completion.
Contact Almond Exteriors And Your Banker
The fastest way to reach Almond Exteriors from this page is the eligibility check above. It goes to Almond Exteriors and to Ilonka Avila at the same time, so the building and financing conversations start together.
Almond Exteriors
Custom home builder, founded in 2000
Serving: Hampton, Newport News, Poquoson, and York County, Virginia
Builds: Raised coastal and waterfront homes, custom homes on client lots, homes in developments and on prepared sites, remodels, and home additions
Ilonka Avila
Top Rated® National Vice President
BuildBuyRefi.com, powered by The Federal Savings Bank
NMLS ID# 47252
The Federal Savings Bank, NMLS #411500. FDIC insured, veteran owned, federally chartered, and licensed in all 50 states.
Why homeowners choose Almond Exteriors. More than two decades of building in Coastal Virginia, homes designed for the specific lot instead of a production plan, real experience with raised and flood-zone construction, and clients who say the communication never drops off. Almond Exteriors answers the building questions. Ilonka Avila answers the financing questions, and both conversations can happen before a dollar is committed.
Where Almond Exteriors Builds In Coastal Virginia
Almond Exteriors builds across 4 communities on the Virginia Peninsula, from in-town lots to waterfront sites in York County communities like Seaford.
For homeowners searching for a custom home builder in York County or Poquoson, waterfront home builders in Hampton Roads, construction loans in Newport News or Hampton, home remodeling and additions in Hampton Roads, or a Hampton Roads mortgage lender that finances new construction, this is the area Almond Exteriors covers.
On the lending side there is no geographic limit. BuildBuyRefi.com is licensed in all 50 states, so financing works anywhere in Almond Exteriors' service area and for buyers relocating to Virginia from anywhere in the country.
More Registered Builders Serving Virginia
Almond Exteriors is one of nearly 2,000 builders and dealers registered with our bank. Ilonka Avila can narrow the options quickly once she knows the land, the plan, and how the home will be used.
Financing Resources
As Seen In